The beat goes on, another week of stock market record highs, in the US, South Korea, Japan and the U.K. overcoming the recent bond market and precious metals frenzy. We saw five green days in a row for S&P 500 (+1.6%) with institutions accumulating, going long or covering deltas, The pattern was clear across all markets, failed breakdown, spitting lows, flushing stops, grabbing liquidity and from there recovering and squeezing. When does that pattern fail is the big question.
Economic data reinforced expectations of a continued easing cycle. While the August PPI came in slightly hotter than expected (0.4%; consensus: 0.3%), and Core CPI met expectations at 0.3%, a 27,000 spike in initial jobless claims to 263,000 (consensus: 240,000), their highest level since October 2021, bolstered the market’s current rate cut expectations through the end of the year.
This week was led by the tech-heavy Nasdaq Composite (+2.0%) with Dow Jones Industrial Average (+1.0%), Russell 2000 (+0.3%) and S&P Midcap 400 (-0.4%) all lagging. The S&P 500 Equal Weight Index (+0.3%) lagged underscoring the influence of the largest components.
The Week Gone By:
S&P500 gained 1.6% (up 11.9% y-t-d),
Dow rose 1.0% (up 7.7%).
Nasdaq100 advanced 1.9% (up 14.7%).
S&P 400 Midcaps dipped 0.4% (up 5.2%),
Small cap Russell 2000 added 0.3% (up 7.5%).
Utilities increased 1.7% (up 11.3%).
Transports slipped 0.6% (down 1.7%).
Banks rallied 2.0% (up 18.8%),
Broker/Dealers jumped 2.4% (up 30.6%).
Semiconductors surged 4.2% (up 20.5%).
Biotechs fell 2.4% (up 5.4%).
With bullion rising another $56, the HUI gold index jumped 4.1% (up 103%).
Gold futures settled $12.80 higher (+0.3%) at $3,686.40/oz Friday, extending weekly gains to +0.9%.
The U.S. Dollar Index flat at 97.56 Friday, shedding 0.2% for the week.
Crude oil finished the week with a slim gain of under $1/bbl
Treasury Yields: 2-yr yield recorded its lowest close in three years Friday
2-yr: +3 bps to 3.56% (+5 bps this week)
3-yr: +4 bps to 3.53% (+5 bps this week)
5-yr: +5 bps to 3.63% (+5 bps this week)
10-yr: +5 bps to 4.06% (-3 bps this week)
30-yr: +3 bps to 4.68% (-10 bps this week)
Benchmark Fannie Mae MBS yields reversed 19 bps lower to 5.14% (down 70bps YTD).
Mega cap stocks had an outsized impact on the broader equity market led by the information technology sector (+3.1%) with broad optimism in semiconductor names. The Vanguard Mega Cap Growth ETF (+2.0%) and PHLX Semiconductor Index (+4.2%) reflecting this. Oracle’s (+25.5%) remarkable mid-week surge following its RPO update ignited technology with volatility across the “magnificent seven,” emphasizing their outsized influence. Tesla (TSLA, +12.9%) and Broadcom (AVGO +7.5%) stood out here. In other corporate news, Paramount Skydance’s (+25.3%) potential acquisition of Warner Bros. Discovery (+55.8%) propelled both stocks higher despite regulatory concerns.
Apparent anomalies in how markets are responding to rash and sudden developments may have sound explanations and could stabilize, versus extrapolating these developments with extreme and premature views such as how they finally represent the end of longstanding dollar dominance and US exceptionalism. Today’s critical issue is untenable market structure engulfed by speculative leverage, a culture of speculation and egregious financial excess,. All this with potentially problematic derivative strategies, and high-risk lending.
Week Ahead Catalysts:
Geopolitical: Chaos Ramps Up
Market volatility is likely to persist into the coming weeks as markets grapple with whether temporary or more profound forces of change are upon financial markets due to unintended effects
US administration appeal to the U.S. Supreme Court after the appeals court left the emergency tariffs in place until Oct. 14, anticipating that the Supreme Court could weigh in by then
Next moves with Russian leader Vladimir Putin and European and Ukraine leaders.
For global central banks, decisions will be delivered by the Federal Reserve, Bank of Canada, Bank of England, Bank of Japan, Norges Bank, and central banks in Brazil, Taiwan, Indonesia and South Africa.
The Q2 earnings season continues in earnest this week with results
Key indicators:
US main data focus Tuesday’s retail sales figures just before the Fed the next day. Other key releases include foreign trade prices, housing starts and building permits, business inventories, the NAHB Housing Market Index, net long-term TIC flows, and regional manufacturing surveys from New York and Philadelphia.
UK Job market conditions (Tuesday) and CPI (Wednesday) will both be updated before the Bank of England’s policy decision.
Canada CPI for August on Tuesday, the day before the BoC delivers its policy decision. Manufacturing shipments and wholesale sales in July (both Monday). Existing home sales will try to make it four monthly gains in a row (also Monday). Housing starts on Tuesday. Retail sales
Europe In Germany, ZEW Economic Sentiment Index, producer prices & wholesale prices. Euro Area, industrial production, trade balance. In France, the manufacturing climate index. Trade balances for the Euro Area, Italy, & Switzerland.
China Industrial production, retail sales unemployment and housing price figures. Vice Premier He Lifeng is expected to meet with a US delegation in Spain to discuss economic and trade issues, including tariffs.
Japan trade figures, CPI
India wholesale prices, trade and unemployment data
Taiwan
South Korea
South America Monthly economic activity updated by Peru and Brazil (Monday) and Colombia (Wednesday).
Australia& NZ Australia’s job market situation on Wednesday. NZ’s Q2 GDP growth on Wednesday
Off-calendar risk could be resurrected with Israel and Iran. The China, Russia Noth Korea 3 stooges.
Traders and investors had become increasingly fearless and in such a mood reshape the narrative to fit with a bullish or bearish mantra. In this vein stocks have moved on from tariff panic, faced with political fatigue have largely taken President Trump, gaffes and all in it’s stride.
Highlights Last Week
Last week’s key U.S. Economic Reports:
The preliminary University of Michigan Consumer Sentiment reading for September checked in at 55.4 (consensus: 59.2) versus the final reading of 58.2 for August. In the same period a year ago, the index stood at 70.1. Fading economic views among lower-income and middle-income consumers.
Consumer credit increased by $16.0 billion in July (consensus: $10.5 billion) following a downwardly revised $4.3 billion decline (from +$7.4 billion) in June. The expansion in consumer credit was driven by revolving credit, which saw the largest jump since January 2024. That might be construed as a sign that consumers are using credit cards more to fund everyday purchases in the face of higher costs, but noticing the jump in nonrevolving credit in July suggests that may not be fully accurate in a broad sense.
The NFIB Small Business Optimism Index rose to 100.8 in August from 100.3 in July
Weekly MBA Mortgage Applications Index 9.2%; Prior -1.2%
August PPI -0.1% (consensus 0.3%); Prior was revised to 0.7% from 0.9%, August Core PPI -0.1% (consensus 0.3%); Prior was revised to 0.7% from 0.9%
August CPI 0.4% (consensus 0.3%); Prior 0.2%, August Core CPI 0.3% (consensus 0.3%); Prior 0.3% Food prices were starkly elevated in August (+0.5%), as were shelter (+0.4%), apparel (+0.5%), transportation services (+1.0%), and gasoline (+1.9%) prices.
Weekly Initial Claims 263K (consensus 240K); Prior was revised to 236K from 237K, Weekly Continuing Claims 1.939 mln; Prior was revised to 1.939 mln from 1.940 mln
The Treasury Budget for August showed a deficit of $344.8 billion compared to a deficit of $380.1 billion in the same period a year ago. The August deficit resulted from outlays ($689.1 billion) exceeding receipts ($344.3 billion). The Treasury Budget data are not seasonally adjusted so the August deficit cannot be compared to the July deficit of $291.1.
NB: The Bureau of Labor Statistics that gathers, analyzes and publishes the price indices has recently advised that a hiring freeze by the Trump administration has resulted in fewer prices being checked. A larger share of the CPI basket is being estimated by prices for comparable products or prices in other regions of the country in lieu of harder data
Central Banks Last Week
Chile’s central bank (BCCh) maintained the Monetary Policy Rate at 4.75%, as broadly expected. In the statement, the Board noted an external scenario with no major changes, though it highlighted elevated uncertainty. One of the few new elements in the statement is the reference to the Fed’s expected rate cut later this month, which the Board says has become “increasingly consolidated”.
Temporary block by a judge last night against Pres Trump’s attempt to fire Federal Reserve Governor Cook.
ECB kept all its policy settings unchanged as expected, leaving the key deposit facility rate at 2.00% for a second consecutive meeting in a unanimous decision. ECB President Lagarde had a hawkish press conference that saw markets scale back their expectations for additional easing from the ECB, particularly as she said that the “disinflationary process is now over for the euro area.” The ECB lifted its 2025 GDP growth forecast to 1.2% from 0.9%, with a small negative revision to 2026 at 1% and unchanged at 1.3% for 2027. Small upward revisions to 2025 and 2026 inflation forecasts were offset by a slightly lower 1.9% call for 2027.
The Board of the Central Reserve Bank of Peru (BCRP) cut its benchmark interest rate by 25 basis points to 4.25% in September, after keeping it unchanged for three consecutive months in line with the market consensus (as reflected in the Bloomberg median). The interest rate differential between the BCRP and the Federal Reserve is now negative—for the time being.
Russia’s central bank disappointed forecasters by cutting by 100bps. Consensus had expected double that amount. Cumulative easing since it began in June now stands at -400bps with the rate set at 17%.
Treasuries are also pressured by the influence the administration is trying to assert on the Fed. The relentless pressure to lower rates and the attacks on Powell unsettle the safe haven component of Treasuries. The demeaning tone towards the Federal Reserve has unappreciated costs such as for global investors concerns on the Trump administration Federal Reserve “reform” effort which drags the Fed into the political cesspool. Thus far the rabid leveraged speculating community appears to ignore the assault on Fed independence.
What that community sees is the inflating price levels, and bathing in it. By last week the Nasdaq100 has returned 18% since the Fed began cutting rates (9/18/24). Money Market Fund Assets have inflated $769 billion, or 15% annualized. Gold has surged 30.6%, Silver 25.1%, Platinum 40.2%, and Copper 33.0%. Bitcoin prices have almost doubled.
This helps us understand the fact that global bond markets are signaling a new paradigm of market yields increasingly disconnected from central bank policy rates. This has been notably since the Fed’s rate cutting cycle last year, long before Trump. Loose monetary policies are no longer automatically transmitted to lower bond yields. There are multiple reasons here; surging bond issuance, mounting debt levels, and structurally elevated inflation risk via tariffs, though this has not come to the fore yet (and may not).
Epic Monetary Inflation
With this week’s plethora of central banks scheduled to wax lyrical it’s a great time to look at the leader of the pack with the Fed’s data released for the second quarter, and what a testament to the epic monetary inflation we are witnessing it is.
The Fed’s ever-expanding role has been a direct consequence of a cycle of ever-more destabilizing speculative deleveraging and bursting Bubbles. The Fed is today trapped by Bubble dynamics and have been held hostage for years. Having taught economic history at Yale, specifically “Twentieth Century Financial Booms and Busts”, the 2007-2009 financial crisis, and hedge fund history and practice, Treasury Secretary Bessent has acute awareness. (see his interview below) Lamenting “mission creep,” he is intimately aware of the role speculative leverage and associated fragilities played in the “Fed’s growing footprint,” “expanded powers,” and “extending its remit.”
Bessent’s concern is “the central bank’s balance-sheet policies directly influence which sectors receive capital” Worth remembering though & many hedge fund and Wall Street finane groups and politicians have reaped billions. All this at the expense of social cohesion and stability, and trust in our institutions, including the Fed.
There is large speculative positions in the US markets, we know that from the basis trade. Last quarter’s Z.1 CBB highlighted “Real Economy Sphere vs. Financial Sphere” analysis. The overheated financial sectors posted another quarter of booming growth this quarter. We also suspect large levered speculative positioning in French and British bonds, to that end European debt generally. Deleveraging risk comes into play if banks positioning is pressured, also snapbacks if there is political intervention of some sort.
Federal Reserve Q2 2025 (Epic)
Outstanding Treasury securities closed June at $28.5 TN. Agency Securities $12.4 TN. Total Non-Financial Debt (NFD) $78 TN. Total (Debt and Equities) Securities $163 TN . Household Net Worth inflated from $40 TN to $176 TN.
Money Market Fund Assets (MMFA) $7.5 TN. System Repo Assets $7.8 TN. Bank Deposits $21.3 TN – Banking system Assets $28.6 TN. Broker/Dealers Assets $6.0 TN. Rest of World (ROW) holdings of U.S. financial assets have ballooned from $7 TN to $60 TN.
Overall NFD growth slowed to a seasonally adjusted and annualized (SAAR) $2.324 TN, down from Q1’s SAAR $2.681 TN and Q2 2024’s $2.783 TN. System Credit growth was held back by a temporary drop in federal borrowings (SAAR $471bn vs. $1.057 TN). At SAAR $1.257 TN, growth in financial sector borrowings was down somewhat Q/Q but remains quite elevated (2023 $346bn and 2024 $575bn). The highly levered Banks and Broker/Dealers further expanded hefty securities portfolios.
The Z.1 category “Domestic Financial Sectors” (DFS) surged $5.117 TN, or 14.1% annualized, during Q2 to a record $150 TN. DFS inflated $10.230 TN y-o-y and $42.069 TN, or 39%, over 22 extraordinary quarters.
Outstanding Debt Securities increased nominal $436 billion during Q2 to a record $63.149 TN, with one-year growth of $3.037 TN (5.1%). Total Equities surged $9.375 TN (41.5% ann.) to a record $99.797 TN. Equities inflated $12.611 TN y-o-y (14.5%) and $48.987 TN, or 96%, over six years. Equities-to-GDP rose to a non-Covid record 329%. This compares to 249% to end 2019, and cycle peaks 188% (Q3 2007) and 210% (Q1 2000). At $162.9 TN, Total (Debt and Equities) Securities ended June at a (non-Covid) record 537% of GDP. This compares to previous cycle peaks 376% (Q3 2007) and 357% (Q1 2000) – and the end of the eighties’ (“decade of greed”) 175%.
System “Repo” Assets jumped $291 billion, or 15% annualized, to a record $8.080 TN. Repo Assets inflated $1.090 TN, or 15.6% y-o-y, and $3.267 TN, or 68%, over 22 quarters.
Money Market Fund Assets expanded $83 billion (4.5% annualized) to a record $7.481 TN, with one-year inflation of $933 billion (14.2%) and 22-quarter ballooning of $3.479 TN, or 87%. Money Market Repo holdings surged $284 billion, or 40.3% annualized, to $3.105 TN. Repo holdings inflated $490 billion, or 18.8%, y-o-y and $1.863 TN, or 150%, over 22 quarters. Treasury holdings declined $267 billion during Q2 to $2.614 TN, while Agency Securities increased $90 billion to a record $993 billion. Money Market Fund Agency Securities holdings grew $252 billion, or 34%, y-o-y and $501 billion, or 102%, over 11 quarters.
Bank Asset growth moderated somewhat to $301 billion, or 4.3% annualized, to a record $28.576 TN. Loan growth surged to $316 billion, or 8.4% annualized – the fastest growth since Q4 2022 – to a record $15.353 TN (up $633bn y-o-y, 4.3%). Loans NEC (“not elsewhere classified”/chiefly business) expanded $217 billion (16.4% ann.) to a record $5.513 TN, with y-o-y growth of $519 billion (10.4%) and 22-quarter ballooning of $1.603 TN (41%).
Mortgage loans increased $67 billion to a record $7.114 TN, the largest quarterly increase in two years. Consumer Credit increased $30 billion (4.5% ann.) to $2.696 TN, the strongest expansion in six quarters. Repo Assets gained $35 billion to $817 billion, with one-year growth of $164 billion, or 25% (strongest since 2019).
Banking system Debt Securities holdings expanded $106 billion to a four-year high $6.336 TN (up $364bn y-o-y, 6.1%). Treasury holdings surged $108 billion, or 24.9% annualized, to a record $1.849 TN. Treasury holdings were up $245 billion, or 15.3% y-o-y, and an unprecedented $970 billion, or 110%, over 22 quarters.
On the Liability side, Bank Repos expanded $67 billion to $814 billion. Total Deposits increased $111 billion to a record $21.256 TN. Deposits were up $886 billion y-o-y (4.4%), with 22-quarter growth a historic $5.730 TN, or 37%.
Broker/Dealer Assets expanded another $259 billion, or 18% annualized, to a record $6.018 TN. Assets surged $849 billion, or 16.4%, y-o-y; $1.594 TN (36%) over 11 quarters; and $2.076 TN, or 53%, in 22 quarters. Broker/Dealer Loan assets jumped $75.4 billion (40.6% ann.) to $818 billion – the strongest quarterly growth in four years. Loans expanded $143 billion y-o-y, or 21.2%.
Broker/Dealer Debt Securities holdings surged $106 billion, or 36.3% annualized, to a record $1.279 TN. Debt Securities inflated $316 billion, or 32.8% annualized, over the past year, and $677 billion, or 112%, over 11 quarters. Treasury holdings increased $26 billion (21.3% ann.) during Q2; $155 billion (43%) y-o-y; and $287 billion (127%) over 11 quarters. Ballooning Agency Securities holdings (to a record $624 billion) were even more notable: Q2 $57 billion (40.6% ann.); one year $479 billion (332%); and 11 quarters $557 billion (815%). The only comparable period was the two-year doubling of Agency Securities into the 2008 crisis.
Broker/Dealer Miscellaneous Assets surged $109 billion (27% ann.) to $1.745 TN (high since Q3 2008). One-year growth increased to $173 billion, or 11%, with 22-quarter ballooning of $511 billion, or 41%. After Q1’s blistering $241 billion expansion, Repo Asset growth slowed to $75 billion – to $1.855 TN. Repo Assets expanded $147 billion y-o-y (8.6%) and $525 billion, or 39%, over 11 quarters.
How did the Broker/Dealers finance such monstrous asset growth? Growth slowed, though the $15 billion increase pushed “Repo” Liabilities to $2.713 TN – the high since Q3 2008 – following Q1’s monster $362 billion surge. This put one-year growth at $333 billion, or 14%, with 11-quarter ballooning of $1.100 TN, or 68%. Miscellaneous Liabilities jumped $147 billion during Q2 to $1.265 TN – the high since pre-crisis Q3 2008. It was the strongest quarterly growth since Q2 2007. The liability Loans increased $69 billion (24% ann.) to $1.248 TN, with one-year growth of $208 billion, or 20%.
“Other Financial Businesses” – formerly “Funding Corps” – “Includes funding subsidiaries, custodial accounts for reinvested collateral of securities lending operations.” Assets expanded $76.8 billion, or 24% annualized, to $1.353 TN – the high back to Q4 2008. One-year growth accelerated to $266.7 billion, or 24.4%, with 22-quarter growth of $726 billion, or 115%. It’s worth noting that “Funding Corp” Assets surged $267 billion, or 22%, in the nine quarters preceding the 2008 financial crisis. Funding Corps invest a portion of incoming balances (i.e., proceeds from short sales) into Open Market Paper (commercial paper), with the increase in Funding Corp holdings accounting for $63 billion of the total $71 billion Q2 gain in system Open Market Paper.
System Asset-Backed Securities (ABS) increased $32 billion (7.6% ann.) to $1.728 TN – the high since Q1 2013. At $179 billion (11.6%), one-year growth was the strongest in three years. ABS inflated $467 billion, or 37%, over four years.
Exchange Traded Funds (ETF) inflated $1.123 TN, or 43.3% annualized, during Q2 to a record $11.492 TN, with one-year growth of $2.349 TN, or 25.7%. ETFs ballooned $7.721 TN, or 205%, over the past 25 quarters. Domestic Equities ETFs surged $788 billion during Q2, or 47.2% annualized, to a record $7.468 TN. Equities ETFs ballooned $1.530 TN, or 25.8% y-o-y, and an incredible $5.277 TN, or 241%, over the past 25 quarters.
Ballooning financial sector is most consequential in the Household sector.
Household Assets inflated $7.269 TN during Q2, the largest gain since coming out of the Covid crisis (Q2 2021).
Assets were up $10.446 TN, or 5.6%, y-o-y, with 21-quarter growth of $69.818 TN, or 54.8%. Household Liabilities increased $183 billion (3.5% annualized), the largest increase since Q4 2022. Household Net Worth (Assets less Liabilities) jumped $7.086 TN, or 16.8% annualized, to a record $176.293 TN. Net Worth was up $10.133 TN over one year (6.1%); $29.996 TN over three years (19.7%); and $65.388 TN, or 59%, over 21 quarters. Household Net Worth rose to (a non-Covid record) 581% of GDP, which compares to 534% to end 2019 and previous cycle peaks 487% (Q1 2007) and 443% (Q1 2000).
Inflating Household wealth comes from all directions. Real Estate holdings increased $1.236 TN (9.5% ann.) to a record $53.224 TN – with 21 quarter growth of $19.042 TN, or 55.7%.
Household Financial Assets inflated $5.847 TN, or 18.2% annualized, during Q2 to a record $134.590 TN. Financial Assets increased to 443% of GDP. This compares to Q4 2019’s 428%, and previous cycle peaks 372% (Q3 2007) and 353% (Q1 2000). Household Debt Securities holdings expanded $93 billion to a record $5.844 TN. Debt Securities holdings gained $277 billion y-o-y (4.9%) and $2.720 TN over three years (86%).
Household Equities surged $3.734 TN (39% ann.) to a record $41.790 TN – with three-year growth of $14.980 TN (56%), and a 21-quarter surge of $25.456 TN, or 156%. With Mutual Fund holdings rising to $12.759 TN, Total (mostly) Equities expanded to a record $54.549 TN, or 180% of GDP. This compares to Q4 2019’s 142% and previous cycle peaks 105% (Q3 2007) and 116% (Q1 2000).
Household Treasury holdings gained another $58 billion to a record $2.751 TN, expanding $253 billion (10.1%) over one year and $2.048 TN (291%) over three years. Money Market (MM) holdings jumped $53.4 billion during Q2 to a record $4.876 TN. MM holdings inflated $682 billion (16.3%) y-o-y and $2.036 TN over three years (72%). The expansion of total Treasuries, Agency Securities, Bank Deposits and Money Fund holdings slowed to $102 billion during the quarter – with one-year growth of $1.418 TN (6.5%) and unprecedented 21-quarter inflation of $6.986 TN (43%).
Household Assets-to-GDP rose to 650% (previous cycle peaks 584%, 513%). Financial Asset holdings increased to 443% of GDP, up from Q4 2019’s 428%, and the previous cycle peaks 372% (Q3 2007) and 353% (Q1 2000). In the most consequential of these ratios, Household Net Worth jumped to (non-Covid GDP contraction record) 581% of GDP, up from 2019’s 534% and previous peaks 487% (Q1 2007) and 443% (Q1 2000).
Federal Reserve Assets declined $51 billion during Q2 to $5.737 TN. Total Fed Liabilities contracted $54 billion to $6.632 TN.
Life Insurance Assets inflated $336 billion for the quarter to a record $10.719 TN, with one-year growth of $721 billion, or 7.2%.
Finance Company Assets expanded $32 billion to $1.728 TN, with one-year growth of $180 billion, or 11.6%.
Federal expenditures of SAAR $7.340 TN were up 6.9% versus Q2 2024, with Receipts of SAAR $5.593 TN increasing 10.3%.
Rest of World (ROW) U.S. financial assets holdings surged
Rest of World (ROW) holdings of U.S. financial assets surged a quarterly record $4.136 TN, or 29% annualized, during Q2 to an all-time high $60.637 TN. This put one-year growth at $6.878 TN, or 12.8%, with 19-quarter ballooning of $21.921 TN, or 56.6%.
Debt Securities holdings gained $286 billion (7.6% ann.) during Q2 and $1.405 TN, or 10.1%, y-o-y. U.S. Corporate Bond holdings jumped $189 billion, or 17.2% annualized, to a record $4.597 TN, with one-year growth of $468 billion, or 11.3%.
Treasury Securities increased $96 billion during the quarter to a record $9.146 TN, with one-year growth of $896 billion (10.9%) and 19-quarter ballooning of $1.892 TN, or 26%. Agency holdings flatlined at $1.366 TN (up $20bn y-o-y). Repo Assets expanded $34 billion to a record $1.528 TN (up $153bn y-o-y, 11%), with 19-quarter ballooning of $668 billion, or 78%.
ROW Total Equities (Equities & Mutual Funds) inflated $2.000 TN, or 45% annualized, during Q2 to a record $19.648 TN. Total Equities holdings ballooned $2.970 TN, or 17.8% y-o-y, and $9.541, or 94%, over 19 quarters.
On the ROW Liabilities side, Repo Liabilities jumped $84 billion, or 17.6% annualized, to a record $1.980 TN. Repo Liabilities inflated $322 billion, or 19.4%, y-o-y and $774 billion, or 64%, over 19 quarters.
Treasury Secretary Scott Bessent, Wall Street Journal (“The Fed’s ‘Gain of Function’ Monetary Policy), September 5, 2025:
“Overuse of nonstandard policies, mission creep and institutional bloat threaten the central bank’s independence. The Fed must change course. Its standard tool kit has become too complex to manage, with uncertain theoretical underpinnings. Simple and measurable tools, aimed at a narrow mandate, are the clearest way to deliver better outcomes and safeguard central-bank independence over time.”
“Successive interventions during and after the financial crisis of 2008 created what amounted to a de facto backstop for asset owners. This harmful cycle concentrated national wealth among those who already owned assets. Within the corporate sector, large firms thrived by locking in cheap debt, while smaller firms reliant on floating-rate loans were squeezed as rates rose. Homeowners saw their property values soar, largely insulated by fixed-rate mortgages. Meanwhile, younger and less affluent households, shut out of ownership and hit hardest by inflation, missed out on appreciation. By failing to deliver on its inflation mandate, the Fed allowed class and generational disparities to widen. Its pursuit of a wealth effect to stimulate growth backfired.”
“The Fed’s growing footprint has profound implications for independence. By extending its remit into areas traditionally reserved for fiscal authorities, the Fed has blurred the lines between monetary and fiscal policy. The central bank’s balance-sheet policies directly influence which sectors receive capital, intervening in what should be the domain of markets and elected officials. Entanglement with Treasury debt management creates the perception that monetary policy is being used to accommodate fiscal needs. Expanded powers have fostered a culture in Washington that relies on the Fed to bail out the government after poor fiscal choices. Instead of accountability, presidents and Congress have expected intervention when their policies falter. This ‘only game in town’ dynamic has created perverse incentives for irresponsibility.”
“At the heart of independence lies credibility and political legitimacy. Both have been jeopardized by the Fed’s expansion beyond its mandate. Heavy intervention has produced severe distributional outcomes, undermined credibility and threatened independence. Looking ahead, the Fed must scale back the distortions it causes in the economy. Unconventional policies such as quantitative easing should be used only in true emergencies, in coordination with the rest of the federal government. The U.S. faces short- and medium-term economic challenges, along with the long-term consequences of a central bank that has placed its own independence in jeopardy.”
Worth noting Secretary Bessent’s from his years at Quantam with Jim Rogers and George Soros and then as an independent hedge fund manage has mastered “reflexivity” and Bubble analysis like few others.
From his January 2024 Key Square Capital Management letter: “We believe that this inappropriately easy policy inflated the dot-com equity bubble…” “Our base case is that a re-elected Donald Trump will want to create an economic lollapalooza and engineer what he will likely call ‘the greatest four years in American history’… In this scenario, the greatest risk factor, in our opinion, would be a sudden rise in long-end rates.”
Meanwhile in America U.S. markets were remarkably calm in the face of European turmoil and the Trump v Fed Governor Cook has become another Partisan megaphone. The left calls it an unprecedented threat to Fed independence. The center right simply points out to financial malfeasance from someone who oversees it. Keep it mind two Fed Governors resigned over insider stock trading a few years ago, Kaplan & Rosengren, so this is not upreceented by any means.
The Fed sees a shift in the balance of risks of a weaker labor market against inflation following the revision to payrolls and higher unemployment, likely warranting an adjustment to monetary policy that will translate to a 25bps rate cut in the upcoming September decision. Additionally, traders still have bets of three total rate cuts this year, supporting non-yielding precious metals.
Powell at Jackson Hole: “In the near term, risks to inflation are tilted to the upside, and risks to employment to the downside—a challenging situation. When our goals are in tension like this, our framework calls for us to balance both sides of our dual mandate. Our policy rate is now 100 bps closer to neutral than it was a year ago, and the stability of the unemployment rate and other labor market measures allows us to proceed carefully as we consider changes to our policy stance. Nonetheless, with policy in restrictive territory, the baseline outlook and the shifting balance of risks may warrant adjusting our policy stance. Monetary policy is not on a preset course.”
An upside inflation surprise could really stuff things up. Despite lower energy prices, tariffs coupled with an uptick in growth raise the odds of higher inflation. There were inklings in the July CPI data, and more than inklings in elevating producer prices. The administration’s most likely argument will soon shift from “no evidence” to tariff-related price increases being one-off and not inflationary.
With the loose financial conditions and markets booming the market hasn’t had a pronounced downturn despite political negativity of late. Strong economic numbers and the absence of Tariff damage yet combined with the historic AI arms race have spurred surges in market activity. Financial conditions have loosened further and the FOMO backdrop is increasingly manic.
“A massive wall of debt coming due, an unpredictable US leader and falling yields have compelled corporate borrowers to sell debt this year at the fastest clip since the pandemic debt binge of 2020. August 5 – Bloomberg (Ethan M Steinberg)
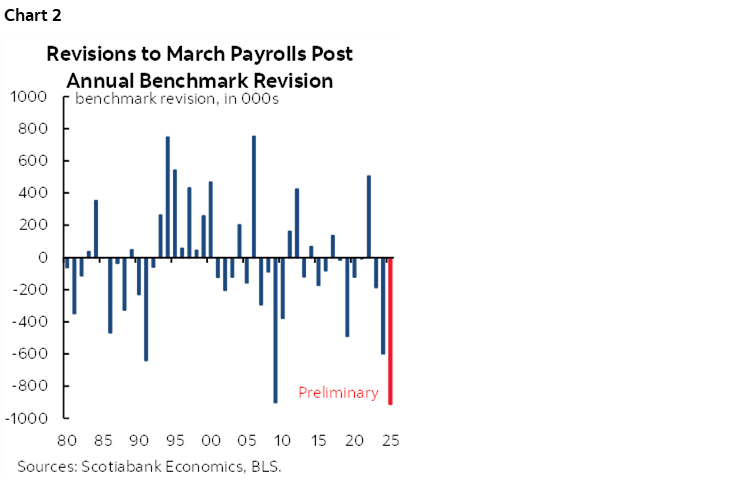
It has been clear for a while that economic and market analysts have got it all wrong so far, tends to happen when all follow each other and are doused with political bias. Now even worse the data collection and reporting has been greatly exaggerated, or plainly wrong. With the effects of loose financial conditions fueling upside surprises in economic activity and inflation, what is correct? Meanwhile the markets have blinkers on as loose financial conditions fuel the moves, until last Friday’s jobs bomb dropped, but that took just a weekend to forget. The economy has been performing much better than projected by the experts and inflation much tamer than also projected by those experts. Powell had been basing his rates policy on that, turns out the jobs situation isn’t as it seemed.
Treasuries are also pressured by the influence the administration is trying to assert on the Fed. The relentless pressure to lower rates and the attacks on Powell unsettle the safe haven component of Treasuries. The demeaning tone towards the Federal Reserve has unappreciated costs such as for global investors concerns on the Trump administration Federal Reserve “reform” effort which drags the Fed into the political cesspool. Thus far the rabid leveraged speculating community appears to ignore the assault on Fed independence.
What that community sees is the inflating price levels, and bathing in it. By August the Nasdaq100 had returned 18% since the Fed began cutting rates (9/18/24). Money Market Fund Assets have inflated $769 billion, or 15% annualized. Gold has surged 30.6%, Silver 25.1%, Platinum 40.2%, and Copper 33.0%. Bitcoin prices have almost doubled.
This helps us understand the fact that global bond markets are signaling a new paradigm of market yields increasingly disconnected from central bank policy rates. This has been notably since the Fed’s rate cutting cycle last year, long before Trump. Loose monetary policies are no longer automatically transmitted to lower bond yields. There are multiple reasons here; surging bond issuance, mounting debt levels, and structurally elevated inflation risk via tariffs, though this has not come to the fore yet (and may not).
Tariff Watch
Update Aug 31, 2025:The Federal appeals court ruled on Friday that most of the tariffs Trump has imposed so far using a 1977 law, IEEPA to impose tariffs on an emergency basis is invalid. That affirmed a May 28 ruling by a lower court, but the 7-4 appeals court decision tossed out a part of that ruling striking down the tariffs immediately, allowing his administration time to appeal to the U.S. Supreme Court. The appeals court left the emergency tariffs in place until Oct. 14, anticipating that the Supreme Court could weigh in by then.
The president vowed to take the fight to the Supreme Court. “If allowed to stand, this Decision would literally destroy the United States of America,” he wrote on his social media platform.
The case outcome and timing of a decision is uncertain. This leaves importers facing a chaotic situation likely to weigh on the economy for the rest of the year and possibly well into 2026. Emergency tariffs account for 78% of the new tariff revenue importers are paying, according to the Tax Foundation. As a rule of thumb, the emergency tariffs are the “reciprocal” tariffs Trump has levied on imported goods from virtually every nation. Those range from 10% to 50%, with the biggest change being in an increase of more than 30% in the tax on goods from China, the second-largest source of American imports.
“While existing trade deals may not automatically unravel, the administration could lose a pillar of its negotiating strategy, which may embolden foreign governments to resist future demands, delay implementation of prior commitments, or even seek to renegotiate terms,” Ashley Akers, senior counsel at the Holland & Knight law firm and a former Justice Department trial lawyer, said before the appeals court decision.
How markets reacted following the Aug 1 Tariff implementation:
High yield CDS (Credit default swap) prices surged 22.4 that week to 336 bps, the largest weekly move since the (“liberation day”) week of April 4th (62 to 439bps).
Friday’s 13 bps jump was the biggest daily increase since May 21st (reports of Israel preparation for strikes on Iran’s nuclear facilities).
Investment-grade CDS rose four this week to 54 bps, the most since the week of May 23rd. Friday’s 2.8 bps was the largest daily increase since May 21st.
High yield spreads widened 23 bps Friday to a five-week high of 301 bps, the biggest upside move since April 4th (up 40 to 427bps). The week’s 27 bps widening was the most since the week of April 4th (87bps).
Investment-grade spreads widened four Friday (to 80bps), the largest since the seven bps jump on April 7th (to 116bps).
Leveraged loan prices dropped 0.22 this week to 97.31, the largest drop since the week of April 11th (down 0.26 to 94.75).
White House Thurs released Reciprocal Tariffs rates covering imports scheduled to take effect in 7 days, at 12:01 a.m. Washington time August 1
Minimum tariff rate for imports from most countries not listed below set at 10%.
Some incl China, Canada & Mexico covered under different order
On Sunday July 17 it was announced that a U.S.–EU trade deal was reached:
📜 Key terms of the deal via Illimar Mattus @IllimarM
15 % import tariff imposed on most EU goods entering the United States—down from a previously threatened 30 % across-the-board rate.
50 % tariffs remain in place on steel and aluminium from the EU, though these may later be shifted to quota-based measures .
Certain strategic categories — including aircraft components, semiconductors, generic pharmaceuticals, selected chemicals, critical raw materials and some agricultural goods—will be granted zero tariffs from both sides (“zero-for-zero” approach).
The EU commits to purchase approximately $750 billion in U.S. energy (notably LNG) over the term of Trump’s second term—roughly $250 billion per year—and invest $600 billion in U.S. assets, including military equipment.
The EU agrees not to impose retaliatory tariffs on U.S. goods and will adopt U.S. industrial and auto standards in certain sectors.
• The agreement was timed to avoid an imminent tariff escalation set for August 1, when the U.S. had planned to raise tariffs on EU goods to 30–50 %, depending on category.
Trump’s cascade of tariff orders has begun generating tens of billions of dollars a month in new revenue for the U.S. government. U.S. customs duties revenue topped $100 billion in the federal fiscal year through to June, according to U.S. Treasury data on Friday. However there isa price to pay, the tariffs have also strained diplomatic relationships with some of the closest U.S. partners.
Japanese Prime Minister Shigeru Ishiba said last week that Japan needed to lessen its dependence on the U.S. The fight over tariffs has also prompted Canada and some European allies to reexamine their security dependence on Washington, with some looking to purchase non-U.S. weapons system. This week we got more ‘tariff letters’ as Trump returned to a more aggressive trade posture with latest tariff threats
There is little doubt President Trump is pumped with success, the danger is does this come off the rails or does his grand plan, assuming there is one, come together? He has seen the passage of the Big Beautiful Bill budget, judicial victories, and achieving a ceasefire between Israel and Iran. Next up is the center piece initial chapter in its dramatic changes of America’s foreign economic policy. The 90-day hiatus since Liberation Day has come to an end and tariff letters are flying.
Despite Chairman Powell’s warnings the impact of the tariffs so far seems limited. We have seen some preliminary signs of pass through, April and May US import prices, excluding oil, rose by an average of 0.3%. In the previous four quarters, they rose by an average of 0.1%. Federal Reserve Chair Powell, who seems to be threatened daily by trump or by one of his ‘cronies’ has said that if it weren’t for the tariffs, the Fed likely would have continued to cut rates this year.
The continued resilience of the US labor market underscores the rationale of the Fed’s patience. If tariffs don’t reap inflationary damage a September rate cut remains the most likely scenario. The other big market news, after stock market records, is the falling US dollar largely in a recognition that the Federal Reserve will be resuming its rate cuts around the time other G10 countries finish their easing cycle, or nearly so. This in a market world were the majority came in the year long dollars.
The frontloading of tariffs and the increasing bitter domestic and geopolitical scenes has impacted the economic calendar. We saw a decline in consumer confidence in June, a surge in durable goods orders in May, a dip in weekly initial jobless claims, a downward revision to Q1 GDP, and a decline in real personal spending and an uptick in the year-over-year rates for the PCE Price Index and core-PCE Price Index in May.
A continuous question is will the Mid East ceasefire hold or do we see a deepening war? A deepening war would directly impact Iranian oil output vulnerability and a knock-on effect to China. That, and Russia in Ukraine add to the overarching message from Fed Chair Powell at his press conferences is that the Fed is going to stick by its wait-and-see stance, with a still robust labor market and tariff uncertainty.
Risk On Risk Off
We saw with the Israel attacks that risk is being played with blinkers on, FOMO is paramount for the herd. Those within the oil market were warning of inherent risks. Israel was basically telegraphing the attacks as was the US removing staff from the region the day before, yet crude options did not reflect this, either did futures markets, clearly to move 13% in one foul swoop.
There are today two notably powerful countervailing forces. The “risk on” squeeze dynamic is spurring speculative leveraging and the perception of abundant liquidity. At the same time global bond markets signal waning demand and fledgling liquidity issues. (the JGB and gilt issues were less than two weeks ago) Strong risk market gains, the perception of liquidity abundance, and attendant complacency work to mask mounting risks to Treasury and global bond market stability.
What also hasn’t changed is the concentration of ‘bets’. magnificent 7 or MAG7 related margin debt, options, and other related derivatives have produced extraordinary liquidity effects (money market fund assets up another $67bn the week ahead of the bombing, despite the TSLA nosedive). It all becomes self-fulfilling, until it doesn’t. Rising stock prices fuel self-reinforcing liquidity creation, while sell-offs heighten risks of illiquidity, deleveraging, and market dislocation. FOMO trumps all at his time.
The egregious Treasury “basis trade” leveraging drives unprecedented overall hedge fund leverage. Household market participation is unparalleled, with the proliferation of online accounts, options trading, and herd-like speculation creating extraordinary market-moving power.
“Citadel’s… CEO Ken Griffin said… it is ‘unfathomable’ that a financial instrument to protect against an eventual U.S. default is being priced at levels close to some European countries. ‘I never thought in my life I would see the U.S. priced higher in risk cost than a number of countries like Spain, Germany or France,’ he said… ‘You gotta be kidding me.’ Griffin said the credit default swap (CDS) market has some issues with liquidity which impact prices, but still he considered that conversations around how close the swaps are trading are ‘unfathomable’… ‘The United States’ fiscal house is not in order. You cannot run deficits of six or 7% at full employment after years of growth. That’s just fiscally irresponsible,’ he said.” June 5 – Reuters (Carolina Mandl and Davide Barbuscia)
From April 25th ‘24 lows to July 10th 24’ highs, the Bloomberg MAG7 Index surged 38%.
From July 10th highs to August 5th ’24 lows, MAG7 dropped 22%.
From August 5th lows to December 18th highs, the index surged 51%.
From December 18th highs to April 7th ’25 lows, MAG7 sank 33%.
From April 7th lows to Friday’s (June 6th) close, the index has rallied 35%.
Gambit [ˈɡambət] noun“a device, action, or opening remark, typically one entailing a degree of risk, that is calculated to gain an advantage’
Crises of Confidence:
The reasons are many, investor anxiety over U.S. fiscal health increased following the passage of a substantial tax-and-spending bill in the House, which is projected to significantly increase the national debt. This followed Moody’s downgrade of the U.S. credit rating and a weak Treasury bond auction fueling weakness in the U.S. dollar, enhancing gold’s appeal. The concern is the tax bill would add trillions of dollars in coming years to already ballooning budget deficits at a time when investor appetite is waning for US assets across the globe.
Committee for a Responsible Federal Budget: “The Congressional Budget Office (CBO) released its first comprehensive estimate of the House’s Fiscal Year (FY) 2025 reconciliation bill – the One Big Beautiful Bill Act – finding that before accounting for interactions, the bill would add $2.3 trillion to deficits over the next decade. Incorporating our estimates of interactions and the adjustments announced by House leadership Monday, we estimate the bill would add $3.1 trillion to the debt as written.” May 21
Geopolitical contagion impacts
The consequences of inflationism and monetary disorder have been fundamental to the rapidly shifting financial markets but also the geopolitical landscape. We had this week Russia’s Putin, North Korea’s Kim bookending China’s Xi in a massive military parade and claiming “new world order”.
“North Korean leader Kim Jong Un and Russia’s Vladimir Putin flanked Xi Jinping at a massive parade of military might in Beijing…, capping a week of diplomatic grandstanding by the Chinese president and his allies against the West. In unprecedented scenes, Xi shook both their hands and chatted with the pair as they walked down a red carpet by Tiananmen Square, with Putin to Xi’s right and Kim to his left. The event, ostensibly to mark 80 years since the end of World War II, was a chance for Xi to put on an extravaganza to showcase China’s military prowess and bring together friendly leaders to send a message to the rest of the world. Kicking off the parade, President Xi warned the world was still ‘faced with a choice of peace or war’, but said China was ‘unstoppable’. China’s enormous new intercontinental ballistic missile DF-5C, with a range of 20,000 kilometres, counted prominently among the tonnes of hardware on display.” September 3 – AFP
Prospects for inflation are both troubling and highly uncertain. The trade war with China will accelerate decoupling between the world’s great consumer and producer economies, a dynamic conducive to supply-chain problems and ongoing inflationary pressures. A seizing up of global markets has the potential to unleash the forces of economic depression and deflation. Globalization has been a powerful force for lower goods prices., something that in rebuilding the U.S. industrial base would see a high-cost producer replace a low-cost producer.
April 16 – Financial Times (William Sandlund and Chan Ho-him): “Donald Trump’s on-off tariffs have pushed currency volatility to multiyear highs and boosted demand for foreign exchange hedging products as companies struggle to adjust to market swings. Currency volatility has surged in recent days to levels last reached during the collapse of Silicon Valley Bank and Credit Suisse in March 2023… The uncertainty around Trump’s tariffs has created more demand for FX hedging products to offset sudden fluctuations in exchange rates that are hitting businesses with global operations, according to banks and executives at multinational companies.”
April 8 – Bloomberg (Vassilis Karamanis): “Currency traders are positioning for turbulence in currency markets to get even worse as an escalating trade war shakes up the global economic order. The dollar and its peers have been whipsawed by some of the sharpest price swings since the 2008 financial crisis… Options volumes surged to a record last week and uncertainty around the trade war has now pushed expectations for volatility in the next month to a two-year high. ‘Volatility in FX has been completely insane,’ Brent Donnelly, president of Spectra FX Solutions LLC., wrote… ‘We saw one of our biggest weeks ever on the trading side as volumes are gigantic and everyone is doing all kinds of stuff.’”
A dangerous market for those not trading with discipline and booking profits. Not one with emotion and preset views dictated by hope, politics or a talking head’s opinion.
We have seen the basis trade burst as crisis dynamics gain momentum. At this juncture the Fed and global central bank community will be faced with having to aggressively expand their balance sheets to accommodate speculative deleveraging and counteract acute systemic stresses. Markets seem to be taking the proven bet that the Fed will be forced into another aggressive round of QE despite elevated inflation risk to counter global market instability and deleveraging.
Stress remains almost across the board with “carry trades”, “basis trades” and especially the “swaps” derivatives marketplace. We have seen some unwinding the massive “basis trade” in Treasuries. To reiterate what we saw last week volatility so far seems about price discovery in the wake of US policy shocks rather than signs of market dysfunction
Debt …. Keeps Building
An overheating economy, coupled with tariff and trade war risks, creates a bond market challenge.
“Several Southern California cities have the most credit card debt per household in the U.S., a new WalletHub study found. Santa Clarita ranked first out of 181 U.S. cities, with a household average of about $22,753 in credit card debt, and a total of about $1.7 billion in debt for its 228,000 residents, according to data taken from the U.S. Census Bureau and TransUnion… Chula Vista was second, with an average of $20,567 in credit card debt per household, and a total of $1.8 billion among its 275,000 residents.” March 21 – Los Angeles Times (Sandra MacDonald)
“AI and its blood and oxygen — chips, data, energy — are producing an economic super-stimulant strong enough to prop up the entire country. Wall Street and retail investors are enabling and encouraging more… more… more. More chips, more data centers, more energy, more investment. The big companies and big investors are the early winners. A wild cycle is unfolding. The biggest companies in history are spending a stunning amount of money to fuel the AI revolution, driving demand for more chips, more energy and more capital… The big (Nvidia, Microsoft, Apple, Alphabet/Google, Amazon and Meta) are getting bigger and burrowing deeper into direct investment and ownership of the products feeding into their AI. They’re buying up land, building data centers, sucking up chips, investing in energy sources. Microsoft and Nvidia together are worth about $2.5 trillion more today than they were a year ago. Alphabet, Google, Amazon and Meta together will spend nearly $400 billion this year on capital expenditures, largely to build AI infrastructure…” August 4 – Axios (Jim VandeHei and Mike Allen):
Meta taps Private Credit to Fund AI
Complimenting booming investment-grade and junk bond markets, “private credit” bubble inflation has intensified. This all looks familiar to previous tech booms such as Y2K and Dot Com, meaning it’s hard to overstate ramifications for the historic AI arms race tapping into the “private Credit” high-risk lending boom.
“The heavy hitters of private credit have been waiting for this moment for years. Major lenders, which often cater to companies with dented credit, talk endlessly about the opportunities in investment-grade debt and in financing the breakneck growth of artificial intelligence. They’ve done smaller deals, but this week they caught the biggest fish yet: a $29 billion financing package for Meta Platforms Inc.’s massive data center in Louisiana… ‘Private credit has been itching to get into this space,’ said John Medina, senior vice president on the global project and infrastructure finance team at Moody’s Ratings. ‘This deal is one of the first of its kind for private credit and if it is successful, we would expect to see more.’ The biggest technology companies are in an AI arms race now, and they need cash to win.” August 8 – Bloomberg (Carmen Arroyo and Olivia Fishlow)
Was DeepSeek the beginning of the end of the AI Speculative Bubble?
Google response to DeepSeek
Alphabet’s Google launched two new AI models on March 12 for robotics applications on its Gemini 2.0 model. Last month robotics startup Figure AI exited its collaboration agreement with ChatGPT-maker OpenAI after it made an internal breakthrough in AI for robots.
Gemini Robotics is an advanced vision-language-action model that will have physical actions as a way to provide output. The second model, Gemini Robotics-ER, will enable a robot to have an advanced understanding of the space around it and lets developers run their own programs using reasoning abilities offered by Gemini 2.0.
Google said its models are designed for robots of all form factors including humanoids and other types used in factories and warehouses. Apptronik raised $350 million in a funding round last month led by B Capital and Capital Factory, with participation from Google to scale production of AI-powered humanoid robots.
Discipline with your trading rules, especially as liquidity falls
There is a reason we have strict trading rules here based on psychology, math, experience and avoiding false narratives and dribble out there. That said pay attention to the time of year, the bonus pay dates (no we aren’t being cynical), tax markings and look the previous run ups into Dec 31. Don’t let the grifters out their sway you, VIX is historically low, what does that tell you? Protection is cheap and the market is complacent with no fear. Here endeth the lesson.
Two paths to bankruptcy: gradually and suddenly. – Ernest Hemingway
Where is the Fear in Instability?
Leveraged speculation, including “basis trades,” “carry trades” and run deep and why the yen and Mexican peso are deeply relevant to this whole structure.
Compressed risk premiums and CDS prices are indicative of complacency. Markets behave this way when there is some underlying monetary disorder (dislocation in liquidity creation). What all this does for markets is keep risk measures on, we see in the vicious VIX fails and short-term option volumes. It is when the risk avoidance measures, or tolerance fails this can trip up the whole structure of buying and cycling through risk assets.
In the backdrop we have war abroad in the Ukraine and Middle East, unsettled relations between Taiwan and China. At home in the US universities and cities to the North have become a quagmire of protest, illegal immigration placement and political vitriol that have deeply divided these regions. The cost of living through it all has sent many working through middle class families to the brink and beyond, insurance costs have risen over 100% in a year in some cases to name just one inflation cost that politicians lie about. While complacency reigns supreme in equities, bonds are awake to the risk out there.
The CBOE Volatility Index is trading at its lowest level since February, as market participants are backing off pursuits to use options to hedge against downside risk after the better than feared.
“We have a market trying to interpret the Fed who is trying to find out how they can interpret their long-only portfolio at a risk parity where rates cannot rise.”– MoneyNeverSleeps
Our weekly reminder for risk, timely given the V shape to ATH. The downside is clear with the absence of moral hazard from repeated Federal Reserve market bailouts in an environment of some would say obscene liquidity pumps. Pure greed is the other part, not wanting to miss out on fees. The obvious question is, how deeply ingrained is this attitude through the markets? How do we ween the markets off this continuous dip feed? At this point the Central Banks have kicked that answer down the road.
Our take remains the Fed is not just focused on inflation but risks such as the commercial real estate debacle, the high US dollar and the massive Federal debt refunding cost.
We need to grasp all the risks to be wary of but not ignore price reaction. We always talk here about expect the unexpected and now that is front and center, gage the market’s reaction, the market is always right and that’s why we focus on the crowd psychology aspect.
Unsuspecting investors in their millions have or will lose meaningful amounts of their savings. They bought into the mania, threw caution to the wind, and will suffer the consequences regardless of the warnings of unsustainability. The reason we started TradersCommunity was for situations like this many moons ago. Beware of those ‘experts’ who never saw the sell off and chided you for believing it now claim to be gurus measuring risk. It’s a bit late when some of these stocks and markets are down 50-90%. Beware of those who claim long term investment when it all goes wrong. Anyhoo..
Oh China
China has gone from bad to worse. Back in September 2024 Xi Jinping promised to spend whatever it takes to reach growth targets as he tapped the reflation panic button. A Reuters article placed Beijing’s stimulus at $1.4 TN. On top of a system locked in massive credit expansion, upwards of $5 TN annually. He is pushing hundreds of billions to the stock market, hundreds of billions to the festering local government sector, hundreds of billions to the to attempt to arrest the slide in the apartment markets.
January 31 2025 – Bloomberg: “China’s residential sales resumed falling in January… The value of new-home sales from the 100 biggest real estate companies dropped 3.2% from a year earlier to 227.6 billion yuan ($31.4bn), after being flat in December… Beijing is struggling to revive the property market amid weak domestic demand and a worsening job situation. While the housing sector has picked up modestly on the back of government support, improvements have mostly been in the second-hand market as buyers remain concerned about developers’ ability to finish projects on time.”
January 27 2025 – Financial Times (Thomas Hale and Chan Ho-him): “Leading Chinese property developer Vanke has forecast a $6.2bn annual loss and announced the sudden resignation of its top leadership, reigniting concerns over funding and confidence across China’s economically critical real estate sector. The developer, partly owned by local authorities in Shenzhen, is the latest focal point of a cash crunch that began with the collapse of peer Evergrande in 2021 and has since engulfed a host of other developers including Country Garden. After weeks of swirling concerns over the health of Vanke, the company said… chair Yu Liang had resigned for ‘work adjustment reasons’. It said chief executive Zhu Jiusheng had departed for ‘health reasons’. The ‘sudden and simultaneous’ resignations were ‘unprecedented in recent memory’ for a big participant such as Vanke, said Foreky Wong, founding partner at Hong Kong advisory company Fortune Ark Restructuring.”
January 28 2025 – Bloomberg: “China Vanke Co. has been thrown a lifeline by state authorities, a rare show of support that signals the developer may be too big to fail even after dozens of property firms defaulted amid China’s punishing housing slump. As part of an overhaul unveiled late Monday, Vanke’s two top veteran executives stepped down after the company warned of a record $6.2 billion loss. An official from Shenzhen Metro Group Co., its largest state shareholder, will take over as chair.”
Meanwhile;
December 18 – Financial Times (Demetri Sevastopulo): “China has increased its arsenal of operational nuclear warheads to 600 from 500 in just a year, as the People’s Liberation Army continues a rapid expansion of its forces, according to the US defense department. In its annual ‘China Military Power Report’, the Pentagon said the PLA had expanded its arsenal by 20% in the 12 months from mid-2023 and was on track to have 1,000 operational warheads by 2030. The Pentagon has in recent years warned that the US will soon face two nuclear peers as China’s arsenal grows closer in size to the US and Russia.”
December 16 – Reuters: “China’s capital markets outflow reached a record high of $45.7 billion in November, according to official data tracking cross-border payments, as Donald Trump’s U.S. presidential election win roiled global portfolio flows. Cross-border receipts from portfolio investments were $188.9 billion, while payments totaled $234.6 billion, resulting in the biggest monthly deficit on record…”
Any pushback to fledgling tightening these days ensures excessively loose financial conditions.
With bullion rising another $56, the HUI gold index jumped 4.1% (up 103%).
W/E Sep 12, 2025
S&P 500 stocks August 2025
Highlights – Europe Stocks
U.K.’s FTSE equities index added 0.2% (up 12.7% y-t-d).
France’s CAC40 rallied 2.0% (up 6.0%).
German DAX equities index increased 0.4% (up 19.0%).
Spain’s IBEX 35 equities index jumped 3.1% (up 32.0%).
Italy’s FTSE MIB index recovered 2.3% (up 24.5%).
Highlights – Asia Stocks
Japan’s Nikkei 225 Equities Index surged 4.1% (up 12.2% y-t-d)
South Korea’s Kospi surged 5.9% (up 41.5%).
India’s Sensex equities index gained 1.5% (up 4.3%).
China’s Shanghai Exchange Index advanced 1.5% (up 15.5%).
Highlights – Emerging Markets Stocks
Brazil’s Bovespa index slipped 0.3% (up 18.3%),
Mexico’s Bolsa index rose 2.1% (up 24.8%).
Turkey’s Borsa Istanbul National 100 index dropped 3.3% (up 5.5%).
Highlights – Australian Stocks
Australia’s ASX 200: Friday +0.7% to 8864.9. (+0.44% on the week) (+0.23% for Month)
YTD 2025 +8.65% 1 Year +9.77%. The benchmark is up around 25% from its April lows.
Friday: The financials sector was among the best performers on the ASX, with all the major banks recording gains. Commonwealth Bank added 1.3% to $169.97, Westpac rose 1.4% to $38.48, ANZ firmed 1.1% to $33.19 and National Australia Bank increased 1.2% to $43.54. Energy was the only sector in the red, following a lower crude oil price. Woodside Energy lost 3.45% to $24.22 and Karoon dropped 2.75% to $1.595.
Commonwealth Bank (ASX)
The stock of Commonwealth Bank has been bouncing around after testing the weekly Tenkan on Friday added 1.3% to $169.97, . CBA is down from its intraday record of $192.
Daily: The SPX has traded like clockwork hitting the 78.6% extension right on cue into election.
Background: The move fueled by the violent ABC for the 5 waves up for SPX continue right into bottom of the median line to give us an (a) or C of a 4. with impulse after completing 5. Reversed hard with energy fueled from the power impulse down from near +1/8 ATH. On the way up (just like down) It accelerated after it broke the Tenkan through the rejected Kijun and then the Kijun to close back over the median and 8/8. Bulls this was a (ii) of a 5. Bears this is a a-b of a C off a completive V of degree. We watch if this low was a (iii), (a) or C. Will determine if sharp ABC completed off all-time highs. We have to respect the number of alternatives of degree of 5. With such trends keep it simple support is Tenkan and Kijun and watch for ABC. No fear is the driving element.
The break up was from above the 200dma. The balance from sharp reversal after the initial 3 wave down from the SPX wave 5 extension as Covid19 fed impulse accelerated under the Tenkan. From there we had seen the ABC or 1-2-3 spinning around the 61.8% of the move. Support began at the October 2019 lows. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in
Weekly: The weekly confirms the daily sequence into the 78.6% extension.
Background: The reenergized SPX tripped in 3 to test recent break up at Tenkan from there we had had a powerful rally to ATH. Again notice what happened “Each new high has evolved after testing Tenkan key support which is the next line after Friday’s dump & minor bounce.” We watch for a spit of a spit Extensions are difficult to time, keep it simple.
Key for the impulse higher was the spit or retest of MM 8/8 and Tenkan San, which held with the previous highs and Tenkan. To repeat “We look for 3 waves down and reactions to keep it simple with the alternatives in the daily.” Keep an eye on the put/call ratio with recognition to the sheer size of contracts AND keep in mind the stimulus distortion. The spit per channel fractal and Adams rule launched back over the cloud where we were encased AND we back tested it. Watch if a spit or clear break support as Chikou rebalances
Dow Jones
NVIDIA (NVDA) and Sherwin-Williams (SHW) replaced Intel (INTC) and Dow Inc. (DOW) in the Dow Jones Industrial Average starting on Friday, November 8, 2024
NASDAQ 100
The Nasdaq100 (NDX) declined 2.4% this week, closing at 19,281, only 56 points, or 0.3%, above the March 13th close. From March 13th lows to this week’s (Tuesday) high, the NDX rallied about 6%, a so far notably unimpressive rally from the previous steep one-month decline (from the 22,223 February 19th high). The Bloomberg MAG7 Index closed the week only slightly above March 11th intraday lows, with the S&P500 ending the week 1.4% off March 13th trading lows. At this critical market juncture, further weakness risks acute instability. – March 28
Background: Fuel was after it broke and held the weekly Tenkan to see a spit of a spit fail which is completive of 5 of some degree with Chikou rebalancing. From there we sold off right to Tenkan (as did SPX) and bounced hard Support Tenkan to Kijun. Watch Chikou for divergence for continuation or failure. Divergence with Russell also a clue.
Russell 2000
The small cap Russell RUT broke out of multi-year flag and then spat the previous high. Unlike SPX and NDX we could not get to new ATH until near the end of this cycle after it got through Tenkan and Kijun on the bounce. This is the index showing more of the fast money crowd and is trading like it. Needs to get traction in here for bulls. Support +1/8 through 7/8 (cloud base)
US Stocks Watch
Investors (and algos) will focus on the conference calls and outlooks. Last quarter everyone expected the worse, we saw critical updates on production in coronavirus impacted regions and if there is extended halting of operations weighing on multi-nationals.
NVidia $NVDA
Nvidia Shares are up roughly 28-fold in the past five years. They completed a potential double top spitting the 4.618 fib extension. That said timing the impulse is one of patience, discipline and usually hindsight.
The surprise here was it came over the Luna New Year break. The Chinese AI DeepSeek was listed for free and went top of the Apple & Google app stairs. Panic ensued and NVidia finished down 17% Monday, the biggest loss of market capitalization in history with a $560 billion evaporation. The Semiconductor index sank 9%. NVDA shares performed a dead cat bounce at best and closed 15.8% lower at the end of the week.
The impact was amplified given trading had boomed in products that allow investors to amp up bets on the world’s most popular equities, with investors pouring a record of more than $6.5 billion into such “single-stock ETFs”, vehicles that track just a single company but use derivatives to intensify bullish or bearish wagers. A major winner in this category was a fund from GraniteShares, which provides two times the daily returns of market powerhouse Nvidia Corp. The strategy, which trades under the ticker NVDL, saw assets explode to a peak of $6.7 billion in late November 2024, with returns in excess of 350% that year. Funds tracking MicroStrategy, Tesla Inc. and Coinbase Global Inc. have followed similar paths.
The move tracked by the KnovaWave extension model followed the announcement of NVDA 4/1 split come levels off the energy break NVidia hadn’t looked back with many gaps below until it hit the 2.618 target of the exhaustion phase. We saw another power move off the $200 retest (old $800) & earnings off $300 which retested. It is a clear leader of SOX SMH look for cues there and ABC failures for changes.
Apple $AAPL
Apple gently motored up to new ATH over the massive $160 then $170 thru to $180 gamma level to new ATH. These levels will be key energy levels. Support from previous highs, resistance now Fibs and Murrey Math levels. Remember the impact $AAPL has, at least short term on all the major indices.
Tesla $TSLA
In the second half, mom and pop then ditched financial companies en masse – only for the cohort to ride the “Trump trade” wave and become the S&P 500’s biggest gainers between July and November 2024. And like many investors during the brief market crash in August, the retail crowd panic-sold some of their hottest assets, including Nvidia and Tesla – all at the lows. That proved painful. Shares of Elon Musk’s EV-maker, for example, have almost doubled since then.
Wrong-sided positioning like this has pushed the retail group’s gains in 2024 to a mere 9.8%, according to Emma Wu, a quantitative and derivatives strategist at JPMorgan, and colleagues. That’s their second-weakest performance in any year when the index posted a positive return since 2015.
Exxon Mobil $XOM
Freeport – McMoRan $FCX
Gold Miners ETF $GDX
Part B: Bond Markets
Global Bonds This Week
Highlights – Treasuries
U.S. Treasuries retreated Friday with longer tenors leading the slide, though even with Friday’s underperformance, 10s and 30s added to their gains from the first week of September while 5s and shorter tenors finished the week in negative territory.
Long bond still logged a strong gain for the week.
Crude oil finished the week with a slim gain of under $1/bbl while the U.S. Dollar Index finished flat at 97.56, shedding 0.2% for the week.
Total money market fund assets (MMFA) inflated another $44 billion to a record $7.303 TN. MMFA were up $996 billion, or 15.9%, y-o-y – and have ballooned a historic $2.719 TN, or 59.3%, since October 26, 2022.
Total Commercial Paper slipped $2.3 billion to $1.401 TN. CP has expanded $313 billion y-t-d and $164 billion, or 13.2%, y-o-y.
Yields at W/E:
2-yr: +3 bps to 3.56% (+5 bps this week)
3-yr: +4 bps to 3.53% (+5 bps this week)
5-yr: +5 bps to 3.63% (+5 bps this week)
10-yr: +5 bps to 4.06% (-3 bps this week)
30-yr: +3 bps to 4.68% (-10 bps this week)
NB: At Close 9/12/25
Relentless pressure on the Fed to lower rates and the attacks on Powell unsettle the safe haven component of Treasuries. The demeaning tone towards the Federal Reserve has unappreciated costs such as for global investors concerns on the Trump administration Federal Reserve “reform” effort which drags the Fed into the political cesspool. Thus far the rabid leveraged speculating community appears to ignore the assault on Fed independence.
What that community sees is the inflating price levels, and bathing in it. By last week the Nasdaq100 has returned 18% since the Fed began cutting rates (9/18/24). Money Market Fund Assets have inflated $769 billion, or 15% annualized. Gold has surged 30.6%, Silver 25.1%, Platinum 40.2%, and Copper 33.0%. Bitcoin prices have almost doubled.
“Bundesbank President Joachim Nagel said a strong US Treasuries market is good for everyone, even as investors have turned to German bunds. ‘It is not good news that there is a lot of doubt regarding the safe haven of US Treasuries,’ he told Bloomberg Television… ‘We need a good US Treasuries market. This is so important for the financial markets worldwide.’” April 23 – Bloomberg (Jana Randow, Mark Schroers and Lisa Abramowicz)
This helps us understand the fact that global bond markets are signaling a new paradigm of market yields increasingly disconnected from central bank policy rates. This has been notably since the Fed’s rate cutting cycle last year, long before Trump. Loose monetary policies are no longer automatically transmitted to lower bond yields. There are multiple reasons here; surging bond issuance, mounting debt levels, and structurally elevated inflation risk via tariffs, though this has not come to the fore yet (and may not).
Central Banks are NOT Controlling Yields
What should be clear by now the Fed is not in control of the monetary inflation process. Indeed the QE experiment means the Fed has for decades accommodated history’s greatest Bubbles, with that come unprecedented leveraged speculation.
It is not just the Fed,
The ECB has cut rates 100 bps so far this year (to 2.15%), German yields have jumped 36 bps y-t-d.
The Bank of England policy rate was reduced 50 bps (4.25%), though gilt yields are up five bps.
The Bank of Canada has cut 50 bps (2.75%), and 10-year yields rose 28 bps.
The Reserve Bank of Australia has reduced rates 50 bps (3.85%), with 10-year yields down only four bps.
Japanese yields have surged 42 bps so far in 2025, after a 25 bps increase in the policy rate.
Inflate or deflate, Bubble dynamics will and have dictated the course of Federal Reserve policies. It would seem the Fed’s balance sheet is the only option for stabilizing system liquidity in the event of major speculative deleveraging. Though we have been hearing that since the 2008 bailout, the Fed for their part appears to whistle past the grave during periods of speculative excess and the resulting marketplace liquidity flooding.
Highlights – Federal Reserve
Federal Reserve Credit was little changed last week at $6.557 TN. Fed Credit was down $2.333 TN from the June 22, 2022, peak. Over the past 313 weeks, Fed Credit expanded $2.830 TN, or 76%. Fed Credit inflated $3.746 TN, or 133%, over the past 670 weeks.
Fed holdings for foreign owners of Treasury, Agency Debt sank $24.4 billion last week to $3.141 TN – the low back to December 2016.
“Custody holdings” were down $173 billion y-o-y, or 5.2%.
Updated 9/12/25
Highlights – Mortgage Market
Freddie Mac 30-year fixed mortgage rates bps to a 10-month low of 6.5% (up 1bps y-o-y).
Fifteen-year rates bps to 5.6% (up 1bps).
Bankrate’s survey of jumbo mortgage borrowing costs had 30-year fixed rates bps to a one-year low of 6.6% (down 1bps).
Updated 9/12/25
Fannie Mac & Mae IPO’s
President Trump working on taking Fannie Mae and Freddie Mac public, “want to be clear, the U.S. government will keep its implicit guarantees” via Truth Social May 27
Update August 8: Fannie Mae and Freddie Mac soared after the Wall Street Journal said Trump is preparing initial public offerings for each of the agencies as early as this year. The sales could raise around $30 billion and value the firms at roughly $500 billion or more together, the WSJ reported.
“The Fannie Mae 30-year current-coupon spread to the 5/10-year blend widened 6 bps to +160 as the U.S. Treasury 10-year yield rose 11 bps to 4.29% and volatility rose. The spread was the highest in more than 13 months. Volatility was the highest in about 18 months.” April 11 – Bloomberg:
“Mortgage rates slingshot higher as tariff uncertainty roils markets.”
“Brutal Week Sees Junk Debt Refinancing Costs Double in 2025.”
“Cracks Are Forming in CLO Market as ETFs on Record Selling Spree.”
“Investors lose $25bn in leveraged ETFs in sector’s biggest meltdown.”
“The World Is Different Now’: Market Convulsions Hit Wall Street.”
The Fed is effectively throwing additional fuel on historic speculative manias. Central banks have been adding liquidity to avoid systematic failure.
Highlights – European Bonds
Italian 10-year yields added two bps to 3.52% (unchanged bps y-t-d).
Greek 10-year yields rose three bps to 3.37% (up 16bps).
Spain’s 10-year yields gained four bps to 3.29% (up 23bps).
German bund yields rose five bps to 2.72% (up 35bps).
French yields jumped six bps to 3.51% (up 31bps).
French to German 10-year bond spread widened one to 79 bps.
U.K. 10-year gilt yields increased three bps to 4.67% (up 10bps).
Updated 9/5/25
Highlights – Asian Bonds
Japanese 10-year “JGB” yields added a basis point to 1.59% (up 49bps y-t-d).
Japan’s 30-year yield traded to a record high 3.21% in August, while 10-year JGB yields rose five bps this week to 1.63% – a new high back to 2008.
Updated 9/12/25
August 22 – Japan’s 30-year yield traded to a record high 3.21% in Friday trading, while 10-year JGB yields rose five bps this week to 1.63% – a new high back to 2008.
July 23 – Reuters (Rocky Swift and Gregor Hunter): “Japanese government bonds tumbled on Wednesday, sending benchmark yields to near 17-year highs, as traders priced in increased political risks and a hazy outlook for the central bank’s policy normalisation path. In a sign of how nervous markets are, the Ministry of Finance’s first sale of super-long government debt since a bruising electoral defeat for Prime Minister Shigeru Ishiba logged the weakest demand in almost 14 years… The 10-year JGB yield jumped as much as 10 bps to 1.6%, marking its biggest move in months and the highest level since October 2008. Super-long term JGB yields hit record highs in May and are back near those levels… ‘We’re seeing a possible buyers’ strike playing through,’ said Chris Weston, head of research at broker Pepperstone.”
Japanese Bonds Surged May 27 on signs that finance ministry may be prepared to adjust debt issuance following a rout in JGB market. Japan’s 20-year bond yield slid as far as 2.31%, down from 2.6% on Friday. The yield on the 30-year tenor dropped 18 basis points to 2.855%, after reaching the highest level since inception last week.
Quietly, China is pumping out record quantities of (globally impactful) Credit.
“A selloff in China’s bond market is accelerating, sending futures on ultra-long debt to a four-month low as a bull run in local stocks builds momentum. Futures on 30-year sovereign notes fell as much as 0.7% Thursday, extending this week’s drop to 1.5% at the low as a gauge of onshore equities reached its highest point since October.” August 13 – Bloomberg (Julia Zhong and Shulun Huang)
China’s state-directed banks increased total assets $1.915 TN during Q1 to a record $63.920 TN, the strongest growth in two years. This pushed one-year growth to over $4.0 TN, or 6.7%.
Aggregate Financing, China’s metric for system Credit, expanded a stronger-than-expected $586 billion during June, up from May’s $319 billion and June ‘24’s $460 billion. First-half growth of $3.185 TN was up 26% from comparable 2024. Record one-year growth of $5.159 TN exceeds even pandemic 2020’s $4.852 TN. Historic Credit expansion belies all the China deflation talk.
Corporate Loan growth of $246 billion (up 8.9% y-o-y) was up from May’s $75 billion and June ‘24’s $227 billion, with first-half growth of $1.608 TN up 5% from comparable 2024. Consumer Loans increased $83 billion (up 3.0% y-o-y), up from May’s $8 billion and June ‘24’s $80 billion. Government Bonds surged $188 billion for the month, easily surpassing June ‘24’s $119 billion. Year-to-date growth of $1.067 TN more than doubled comparable 2024. Record one-year growth of $2.177 TN compares to pandemic 2020’s $1.162 TN.
Junk Bond Market Euphoria
Financial conditions have loosened dramatically since April’s market tumult.
“US leveraged-loan issuance skyrocketed in July as junk-rated borrowers flocked to the market largely to reprice debt, saving companies millions in interest expenses. July set a fresh record with $222.2 billion in loans launched, surpassing the prior $206.7 billion high set in January, according to data compiled by Bloomberg. During the month, more than 180 new leveraged-loan tranches came through the market, the data showed.” BBG
July 21 – Bloomberg (Rachel Graf): “About $61 billion of US leveraged loans hit the market Monday, the second-most ever…, as junk-rated borrowers continue rushing to lower borrowing costs by repricing existing loans. There were 33 launches…, with all but six of them repricings. The largest was a $7.57 billion offering for medical supplies giant Medline, the bulk of which will be used to reprice a term loan.”
July 25 – Bloomberg (Gowri Gurumurthy): “US junk bonds are headed for their second week of gains after steadily rising for six straight sessions… The broad gains were… partly fueled by large cash inflows into US high yield funds in 11 of the past 12 weeks. The funds reported a cash haul of more than $900m for the week ended July 23… CCC yields, the riskiest tier of the junk bond market, dropped to a three-week low of 10.66% after steadily declining for four sessions. CCCs are on track to rack up their seventh week of gains, the longest streak since October… The market priced nearly $9bn in four sessions this week, making it the busiest week since mid-May. The month’s volume is $27.5b. This will be the busiest July since at least 2021.”
July 24 – The Bond Buyer (Jessica Lerner): “Fears about changes to the tax exemption, shifting macroeconomics, growing capital needs and inflation-induced added costs to complete projects… led state and local government issuers to bring debt at a record pace, with issuance already on track to break 2024’s record $500-plus billion. The volume currently stands at $310.166 billion, up 17.4% from $264.151 billion at the same time last year. Now that the second half is underway, several firms revisited their supply projections for the year…”
After spiking to 453 bps, junk bond spreads sank 24 bps this week (4 sessions!) to 268 bps, the narrowest since February 20th.
Investment-grade spreads narrowed eight to 77 bps, matching the low back to December 18th – and closed Thursday only three bps above multi-decade lows.
Leveraged loan prices closed the week at highs since February 27th.
Bank CDS prices have dropped back to March levels – at home and abroad. JPMorgan CDS traded back down to 41.5 bps (April 9th high 71), the low since March 10th. At 99.25 bps,
European (subordinated debt) Bank CDS are down from an April 7th 169 bps high – to the lowest level since March 5th.
July 4 – Bloomberg (Gowri Gurumurthy): “US junk bonds racked up gains for the 10th straight session as investors poured cash into the asset class… Yields hit a nine-month low of 6.99%… US high-yield funds took a cash haul of $3.5b for week ended June 25, the largest weekly inflow in 18 months. It was the ninth consecutive week of cash flows into these funds… The market has already priced $6.6b in just three sessions this week after a flurry of issuance in June made it the busiest month since September 2021.”
July 1 – Financial Times (Euan Healy): “Sales of risky European corporate debt surged to their highest ever level in June, as lowly rated companies take advantage of a capital flight out of US markets… Issuance by high-yield, or junk-rated, companies — many of which have previously struggled to access the market — rose to about €23bn in June, according to JPMorgan… That beats the previous monthly record, set in June 2021, by roughly €5bn. June also saw the greatest number of deals on record at 44… ‘The market is drowning in new deals,’ said an investor at a European credit hedge fund.”
Cocoa and coffee brought inflation to the consumers drinking and and eating habits as companies passed on the price rises.
Cocoa
Cocoa futures were the best performing in 2024, surging by 176% for the year. Since then, we have had a vicious pullback. of around a 1/3 or $4,000. Cocoa a great example of how controlled or limited surplus can determine price. Africa produces 60% of global cocoa and nearly half of the world’s cocoa comes from just two West African countries, Côte d’Ivoire and Ghana.
The surge in 2024 cocoa prices was due to political and weather disruptions in West Africa. The crops were already struggling thanks to underinvestment in cocoa farms with growers struggling to replant diseased trees.
Coffee
Coffee futures followed cocoa higher and was up 73% for 2024, reaching a 47-year high as markets grappled with persistent supply concerns in key growing regions. While it has corrected off those highs in 2025, not to the extent of cocoa. The premium bean, arabica futures price doubling in 2024. Extreme weather in Brazil and Vietnam affected supply whilst demand was pressured by booming demand in markets like China.
Orange Juice OJ
BDI Freight Index
The Baltic Exchange’s dry bulk sea freight index, which tracks rates for vessels transporting dry commodities, rose about 0.7% to its highest since July 28 at 2,126 on Friday, after decreasing by 0.1% in the prior session.
The capesize index, which typically transports 150,000-ton cargoes such as iron ore and coal, rose about 1% to 3,070 points;
The panamax index, which usually carries 60,000-70,000 tons of coal or grain, went up 0.4% to its highest in over a year at 2,006 points.
Among smaller vessels, the supramax index rose about 0.5% to 1,492 points. For the week, the benchmark index advanced by 7.4%, its strongest weekly performance since July 21.
Copper is the bellwether industrial metal and moves on supply risks and hopes for global recovery in demand. Disruptions at major mines and Chinese plants which produce more than half of the world’s refined copper impact price.
“U.S. copper futures plunged roughly 20% in late trading Wednesday after President Trump unveiled 50% tariffs on copper products but not on the raw material itself. It is the latest example of how Trump’s gyrating trade policies have whipsawed financial markets… U.S. copper prices surged to records and well above global prices this month after Trump said he would impose a 50% import tax on the metal…” July 30 – Wall Street Journal (Ryan Dezember)
“The world’s top commodity traders are rushing to ship copper to the US from as far afield as Asia as Donald Trump’s threat of import tariffs on the metal creates a huge opportunity for profit. The gap between copper prices in the US and the rest of the world widened sharply after the president… ordered the Commerce Department to examine potential levies on the metal. On Wednesday, prices on New York’s Comex surged as much as 4.9% to trade more than $1,000 a ton above the London Metal Exchange benchmark, which rose 1.2% to about $9,500 a ton.” February 26 – Bloomberg (Alfred Cang, Archie Hunter and Mark Burton)
Gold
Gold futures trade with investors safety amid growing global uncertainties. The rally was fueled by the Fed’s cautious tone on inflation and economic risks, which dampened rate hike expectations. Rising geopolitical tensions, especially U.S.-China trade frictions and steady central bank demand, particularly from countries diversifying away from the dollar, reinforced gold’s appeal as a safe-haven asset. “Gold’s trajectory of late has been increasingly shaped by growing expectations of imminent Federal Reserve rate cuts, concerns about the institution’s independence, lower real yields, and a US dollar teetering near the lower end of its recent range.”
“The People’s Bank of China increased its gold holdings in August for a 10th month, in a continued push to diversify its reserves away from US dollars. Bullion held by the central bank rose by 0.06 million troy ounces to 74.02 million troy ounces last month… China began this round of gold purchases in November, accumulating a total of 1.22 million troy ounces over the period.” September 6 – Bloomberg
“Bullion held in warehouses linked to the Shanghai Futures Exchange has jumped to an all-time high, another sign of resilient demand for gold investments in China. More than 36 tons of gold bars have been registered for delivery against futures contracts, a quantity that has almost doubled over the past month. The build-up in stockpiles reflects a surge in arbitrage activity triggered by heavy demand for futures, which are trading at a large premium to the physical metal.” August 5 – Bloomberg (Yihui Xie)
“Investor appetite for gold remains undeterred by prices that have soared to record highs against a backdrop of geopolitical instability and weakening confidence in the US dollar. Global gold demand rose 3% year on year in the three months to June…, said the World Gold Council, which represents gold miners… Inflows into gold exchange traded funds remained strong, with global demand during the first half of the year at its highest since 2020.” July 30 – Financial Times (Camilla Hodgson)
“Central banks are increasingly looking to bolster their gold reserves. And they are turning to mines in their backyard to source the yellow metal. Besides being cheaper, securing gold directly from mines helps support local industry and bolsters reserves without weighing on foreign exchange reserves, experts said. While countries such as the Philippines and Ecuador have been doing this for years, more central banks with access to domestic gold mines have started, increased, or are considering direct local purchases, according to the World Gold Council July 15 – CNBC (Lee Ying Shan)
“China added to its official gold reserves for an eighth straight month in June, as prices of the precious metal traded near a record high. Bullion held by the People’s Bank of China rose by 70,000 troy ounces last month… Its gold reserves have climbed by 1.1 million troy ounces — or about 34.2 tons — since the current run of purchases began in November last year.” July 7 – Bloomberg (Sybilla Gross
“A record share of the world’s central banks plans to accumulate more gold over the next 12 months, drawn by bullion’s performance during times of crisis and protection against inflation. In a survey of 72 monetary authorities, 43% said they expected their gold reserves to increase, up from 29% a year earlier and the highest figure in eight years… Central banks have been one of the most important drivers of a long-running gold rally that has seen prices double since late-2022. The pace of buying doubled after the invasion of Ukraine…” June 16 – New York Times (Jack Ryan)
“China expanded its gold reserves for a sixth straight month in April, underlining its push to boost holdings of the precious metal as prices trade near a record and the trade war rumbles on. Bullion held by the People’s Bank of China rose by about 70,000 troy ounces last month… In the latest six-month span, volumes have climbed by close to 1 million ounces, or about 30 tons.” May 7 – Bloomberg (Yihui Xie)
Shanghai Futures Exchange trading volumes of gold highest levels in a year. Investors and industry players (refineries, traders and retailers) have ramped up hedging activities as global markets gyrate in response to trade policy changes in the US and China.
Physical demand for gold has been strong this week, and in China buyers are paying a significant premium for the metal over international spot prices, a sign of strong demand.
UBS raised its gold price forecast in April for the second time this year, to $3,500 per troy ounce over the next 12 months, up from the $3,000 forecast made at the start of the year. “We expect additional demand from central banks, institutions and investors following current events,” UBS analysts wrote in a note to clients.
Gold hit record highs as inflation, safe haven, and Russia and China buying to avoid sanctions pushed it higher last year. The price rose against multiple currencies, including the U.S. dollar. The structural driver is higher demand from central banks, while a cyclical lift would come from flows to exchange-traded funds as the Federal Reserve cuts.
Silver
Silver jumped to $39 per ounce, following the Jackson Hole Powell speech, approaching the 14-year high of $39.5 touched in the end of July amid the outlook of rate cuts by the Fed. Markets assessed the demand for silver’s industrial uses. Solar cell exports from China grew over 70% in the first half of the year, supported by stronger photovoltaic demand from India. This was after China installed over 93 gigawatts capacity of solar panels in May, a 300% surge annually to a fresh record high before a new set of policy changes would make it more difficult to attach panels to grids.
Platinum
“A years-long supply crunch in platinum has come to a head, with banks scrambling for dwindling stocks in London as buyers in China and the US hoover up much of the available metal. The market tightness has made platinum one of the best-performing commodities this year and fueled sky-high borrowing costs for the precious metal. Tariff fears have funneled large volumes to US warehouses, while Chinese imports continue to exceed estimated domestic consumption.” August 5 – Bloomberg (Sybilla Gross, Jack Ryan, and Yihui Xie)
Energy
“China’s thirst for oil drove global demand for decades. Now a government campaign to curb that addiction is nearing a milestone, with national consumption expected to peak by 2027, then begin to fall. Chinese officials have long worried that the U.S. and its allies could hamstring the nation’s economy by choking off its supply of foreign oil. So China has poured hundreds of billions of dollars into weaning itself off the imported stuff… ‘The energy rice bowl must be held in our own hands,’ Chinese leader Xi Jinping has said. Across China, fleets of gas-guzzling Volkswagen and Hyundai taxicabs are being replaced by electric models designed and produced locally. Last year, nearly half of passenger vehicles sold in the country were either all-electrics or plug-in hybrids, compared with 6% in 2020.” July 21 – Wall Street Journal (Brian Spegele):
Oil prices in 2024 traded in a relatively stable range given the world conflicts in energy supply related regions. Intraday Brent prices stayed within a $24/b range, between $68/b and $93/b the narrowest trading range since 2019. Adjusting for inflation, 2024 was the narrowest since 2003. A moribund world economy working against Middle East and Russian tensions. The selling has continued in 2025.
U.S. energy companies played the smart card pushing production higher familiar with the cycle of oil prices. Natural gas demand grew as did record U.S. production, we saw increased electricity consumption, driven by the AI mania.
“President Donald Trump may be teeing up the worst conditions for the oil business so far this century, outside of the 2020 pandemic shock… The International Energy Agency just slashed its forecast for oil demand growth this year by 29% from last month’s projection, to just 730,000 barrels a day. Its initial projections for 2026 continue the theme, with even lower growth of just 690,000 barrels per day. Both figures would represent a slowdown from 2024 and the 20-year average annual increase of almost 1 million barrels per day…” April 15 – Bloomberg (Liam Denning)
Oil and Iran
US Crude Oil (WTI)
Daily: WTI Crude Oil gave back all its rally that evolved from retesting the pennant breakout last December after completing the correction in 3 waves. from there it has fallen to new lows and the upside burst has effectively rinsed short and trapped new speculative buyers with the market now rinsing them as it falls to test support. The market has behaved as expected as we have said being in a completive mode for bulls with the upside impulse, it was a question of degree on the topside, as it will be on the downside. Use the Murrey math 240/60 grid. Was oil completing a C or IV? Support is previous lows and the bull flag. The bear case is the high was a complete 5.
Weekly: WTI crude oil futures held the support line from July 2021, having plunged around 50% off 2022 highs. The market is now back testing it. The break to the topside of its sphere of influence to close out the quarter over Kijun and Tenkan failed, and which are now resistance. Risk support is the grid. Resistance weekly channel, Murrey Math levels and previous breaks (off monthly). Bear case is Wave 5 complete.
What we broke……. Crude Oil in the past quarter built a huge bull flag. We watch if the recent break was false, or we fail. Very clear pattern.
The key is crowd behavior to help tell the story which in energy is often around geopolitics. A great example of why we watch ABC corrections and from here we get the energy from the break being balanced. This move that was powered by 50 dma Tenkan spit of a spit – hence the fractal energies reverberations.
Refinery closures in Europe and US expected to reduce net capacity by 75,000 barrels per day this year.
In China, the refining industry is at a “crossroads as demand approaches its peak,” with 840K b/d of capacity at risk of closing before the end of 2028, according to BMI. Most of the expected reduction in capacity is likely to come from state-owned refiners, although independent processors are also under pressure.
via BloombergNEF tracking of more than 60 assets around the globe.
Daily: US Natural Gas futures are a great example of rebalancing mania. The market is still correcting the manic 5 post the Ukraine invasion and beyond. Since the breakdown of the correction channel with failed breakups we have continued to multi year lows in a pennant formation after holding the daily 1/8. We now look at our Adam’s theory fractal rules with fractal spits powering these moves lower. Two clear alternatives, we are correcting the highs 5 or that was a 3 and we go higher. Resistance is heavy: 2/8 and cloud above. Kijun, 50 dma and cloud. Support is previous lows. Important to watch how this energy was built for shape correlation.
Like the larger wave on the way up it accelerated through previous highs (flat topped triangle energy) and over the resistance at 8/8 and new highs. We successfully tested that break in a pennant ABC. Previous highs (flat topped triangle energy) and 8/8 and new highs underscore the structure that fed the move and is key longer term in the collapse lower.
Weekly: Natural gas has been busy correcting the past months when it blew through all levels of support after breaking the weekly 50wma and the Kijun gave a kiss of death. From there we formed an island reversal which has resolved to the topside, trapping shorts and bears. Recall it broke down out of the corrective channel (Wave 4 or IV) to new multi-year lows. The instability and volatility stem from the sharp reversals that have failed indicative of speculative fervor like the previous impulsive spikes. Support is the flat Kijun and Tenkans. Resistance the near highs and previous uptrend. Bulls need all the damage down to be rebuilt. Kijun became the accelerator given energy lower and now higher came from a clean break of the Kijun
John Maynard Keynes, 1920: “There is no subtler, no surer means of overturning the existing basis of society than to debauch the currency. The process engages all the hidden forces of economic law on the side of destruction and does it in a manner which not one man in a million is able to diagnose.”
For the week ended Sept 12, 2025, the U.S. Dollar Index slipped 0.2% to 97.55 (down 10.1% y-t-d).
On the upside, the Norwegian krone increased 1.8%, the Mexican peso 1.5%, the Australian dollar 1.4%, the South African rand 1.1%, the Brazilian real 1.1%, the New Zealand dollar 1.1%, the Swedish krona 0.8%, the British pound 0.4%, the Swiss franc 0.2%, the euro 0.2%, and the Singapore dollar 0.1%. The Chinese (onshore) renminbi increased 0.11% versus the dollar (up 2.45% y-t-d).
On the downside, the South Korean won declined 0.5%, the Japanese yen 0.2%, and the Canadian dollar 0.1%.
The Dollar from Flex to Sell
“The US dollar had its worst start to the year since 1973, as Donald Trump’s trade and economic policies prompt global investors to rethink their exposure to the world’s dominant currency. The dollar index… tumbled 10.8% in the first six months of 2025, the worst start to the year since the end of the gold-backed Bretton Woods system. ‘The dollar has become the whipping boy of Trump 2.0’s erratic policies,’ said Francesco Pesole, an FX strategist at ING.” – June 30 – Financial Times (Ian Smith)
June 23 – Reuters (Yoruk Bahceli and Dhara Ranasinghe): “The custodians of trillions of dollars of global central bank reserves are eyeing a move away from the greenback into gold, the euro and China’s yuan as the splintering of world trade and geopolitical upheaval spark a rethink of financial flows. The survey of 75 central banks… gives a first snapshot of the repercussions of U.S. President Donald Trump’s April 2 Liberation Day tariffs that sparked market turmoil and a slide in the safe-haven dollar and U.S. Treasuries. Gold, which central banks have already been adding at a record pace, was seen benefiting even further longer term, with a net 40% of central banks planning to increase gold holdings over the next decade. ‘After years of record-high central bank gold purchases, reserve managers are doubling down on the precious metal,’ OMFIF said.”
May 20 – Reuters (Saqib Iqbal Ahmed and Laura Matthews) “Trade-related uncertainties, ballooning fiscal debt and weakened confidence about enduring U.S. exceptionalism have weighed on U.S. assets, with the dollar one casualty. Investors see the currency losing more of its luster as the greenback comes back to earth from lofty valuations. The Trump administration’s tariffs salvo this year prompted investors to cut exposure to U.S. assets after a long period of overperformance… ‘There’s plenty of room for further depreciation, purely from a valuation perspective,’ said George Vessey, lead FX and macro strategist at payments firm Convera. The ‘sell America’ trade was back in focus after Moody’s U.S. credit downgrade, he said.”
Where is all this liquidity coming from fueling this one asks. Well simple really and a reminder of why we watch the carry trade so intently. With greed overshadowing risk and again why breakeven or break up tests are so important, again look at our notes on the stock indices, bitcoin and forex, even gold. The index of carry returns hit a seven-year high in late May Bloomerg reported. Asset managers boosted long positions in developing-nation currencies in recent weeks, our ols favorite Mexico peso reaching a nine-month high. Other, riskier EM carry trades have been the Chilean peso and South Korean won in this run.
The move has coincided with the collapse of the VIX, the strategy performs best in periods of low volatility. JPMorgan Chase’ ‘s gauge of global currency volatility dropped to 8.7% on Friday from as high as 11% in early April. Recall the swoon last year in August with most carry trades funded in the ultra-low-yielding yen being wrecked after the Bank of Japan interest-rate hike that triggered a surge in the yen and with-it losses on the currency, forwards spreads. This was well telegraphed and a reminder to be proactive not reactive and note when scenarios have run their course risk wise. Expect the unexpected.
Another big fillip was NVIDIA’s (NVDA) better-than-expected earnings report and outlook after Wednesday’s close. It should be noted that in a somewhat amazing mis report from NVDA where it was initially reported as a miss at .81 EPS and then corrected to .96 EPS, after there was heavy selling and causing shorts to cover and rebuy added to the strength, Intentional, doubtful but the price affect real. You could argue the same on the tariff on and off effect on trade. Squeeze the shorts, buy the dips like with intent. There was more sources of strength came from stronger 2-yr, 5-yr, and 7-yr note Treasury auctions, improved consumer confidence, and some confusing action on the tariff/trade front.
Talking about tariff on and off market affects; on Wednesday, the U.S. Court of International Trade ruled that the president did not have the legal authority to enforce reciprocal tariffs. On Thursday, the U.S. Court of Appeals granted the White House’s request to temporarily reinstate the tariffs. On Friday, President Trump said China had violated the preliminary trade agreement worked out in Switzerland and noted “So much for being MR. NICE GUY!” before adding later that day that he hopes to be able to work things out with President Xi.
The carry trade in less liquid currency brings risk, as alpha strategy do, currency risk is real. Remeber all the punters that bought the Turkish Lira? The Taiwan dollar surged early May as currency gains saw a stampede to exit positions using it as a funding currency. The Hong Kong dollar back tested the weak end of its trading band in late May as falling local interest rates helped traders to use the currency as a funding vehicle Bloomberg reported. The trade war and the PBOC talking of more easing monetary-policy further in China is seeing the yuan becoming an attractive funding currency,
With inflation falling back with growth falling after high interest rates in many emerging-market economies real yields on their bonds are relatively attractive. Don’t forget the currency risk, see above! Brazil’s real features is being pushed by as an attractive longs at investment banks such as Goldman Sachs Group and ING Groep NV. Something to remeber the BRL fell to record lows earlier in the year against the US dollar and recovered from record support from Brazil’s central bank.
Extraordinary late-cycle resilience is only fitting of history’s greatest Bubble. Explanations include Credit system might that comes from steadfast $2 TN or so of annual federal debt growth – the reckless expansion of money-like Treasury debt. What’s more, Trillions of Treasury/Agency market speculative leverage create a hardier market structure than, say, levered positions in more suspect corporate debt or risky mortgages. And it’s worth noting the recent comments of the robustness of private Credit and private markets more generally.
Key Currencies Versus the US Dollar
Australian Dollar – AUDUSD
The Australian dollar has recovered back to last year’s breakdown. It has corrected off a 5 year low in the New Year after it continued lower after breaking a three-month low of US65.1¢ on news of a Donald Trump’s US election victory before rebounding to US66.51¢ on hopes of fresh China stimulus.
The Aussie dollar had been correcting since completing a 5 at the psych 80 level to fall under the weekly cloud in emotive fashion. The Australian dollar fell to test of the August lows of 0.7106 with Omicron fears. When that double bottom support broke it retested the Murrey Math Levels. Resistance the Cloud, Tenkan and Kijun like many commodities. From there it has been a combination of a stronger US dollar, a collapsing Chinese economy & concerns over the US economy.
Japanese Yen – USDJPY
USDJPY is consolidating the break after weakness with Treasury yields to rush to +2/8 and channel convergence. It came a long way from that 108.00 massive support for dollar-yen back through the top of the flat-topped triangle at 151/152 whcih it spins around in 2025. Any change will come from the weekly Kijun. Use your USDJPY Murrey 7/8 8/8 grid for now. EURJPY AUDJPY will determine risk on/off.
Yen weakness provided key support to dollar melt-up dynamics with BOJ slow-motion “normalization” in a world of fast-moving dynamics. The dollar yen traded 160.17 this cycle, the first time above 160 since April 1990. Governor Kazuo Ueda on that move basically ceded the yen fragility issue to the Ministry of Finance (MOF), affirming it wasn’t in the BOJ’s purview. He conveyed little concern for yen weakness, while downplaying its inflationary impact. The market accordingly took the yen out to the woodshed.
Hong Kong Dollar – USDHKD
June 25 – Financial Times (William Sandlund): “Hong Kong’s de facto central bank has intervened again in foreign exchange markets to defend the city’s currency peg, in a move that threatens one of the world’s most attractive carry trades. The Hong Kong Monetary Authority said it used HK$9.4bn ($1.2bn) of its reserves to buy Hong Kong dollars on the open market… The move will drain liquidity from the banking system and pushed up interbank lending rates on Thursday, potentially threatening a carry trade that has allowed investors to borrow cheaply in the city’s currency before investing in higher-yielding US debt securities.”
Chinese Yuan – USDCNH
China has been battling a weak economy for years and has been flooding its economy with liquidity to no avail, the result, falling yields and a record low for the Yuan against the US dollar. So far it has been defended at a triple top.
“People’s Bank of China Governor Pan Gongsheng laid out in the clearest terms yet his vision for the future of a new global currency order after decades of dollar dominance, predicting a more competitive system will take root in the years to come. ‘In the future, the global monetary system could continue to evolve toward a situation where a few sovereign currencies co-exist, compete and check and balance each other,’ Pan said… Pan said there have been discussions around the world on how to reduce excessive reliance on a single currency, adding that the yuan’s global status has risen in recent years. Confidence in the US is waning after months of President Donald Trump’s erratic policymaking.” June 17 – Bloomberg
“Doubts over US exceptionalism are giving China a much needed break from strongly defending its currency, as the yuan’s strength allows it to dial back support via its daily reference rate. The gap between the People’s Bank of China’s daily reference rate versus narrowed to 675 pips on Monday, the least since early December. While the so-called fixing remains near the strongest level since November, its smaller spread with estimates signals weakening official support for the currency.” March 10 – Bloomberg (Iris Ouyang)
To begin 2025 the onshore yuan weakened past the level that China had been defending throughout December. The yuan breached the psychological milestone of 7.3 per dollar for the first time since late 2023, amid concerns over China’s economic struggles and a widening bond yield discount to the US. The move came even as the central bank maintained its support for the currency with its daily reference rate that Friday.
February 26 – Reuters: “Chinese authorities are rolling out fresh measures to limit capital flight, including increased scrutiny of overseas investments, as the yuan currency comes under mounting pressure. President Donald Trump’s tariffs threats are heightening Sino-U.S. tensions and discouraging inbound foreign investment… China has increased scrutiny of overseas investments by domestic companies and their use of proceeds from Hong Kong share sales… Meanwhile, China’s commercial banks sold the most foreign exchange to their clients since July last month… The conversion ratio – a gauge that measures households and corporates’ willingness to sell dollars for yuan – fell to the lowest level in seven months. Xinquan Chen, an economist at Goldman Sachs, said the current account showed sizeable currency outflows in January.”
January 12 – Bloomberg: “China has ramped up its support for the yuan with tweaks to its capital controls and a vow to crack down on market disruption, after the currency dropped close to a record low against the dollar in offshore trading. The People’s Bank of China and other regulators pledged to strengthen their management of the foreign-exchange market, deal with any behavior that may disrupt the market and prevent the risk of a large move in the yuan… The PBOC also adjusted its rules for cross-border flows…, allowing firms and financial institutions to borrow more from overseas, which may help increase capital inflows and support the yuan.”
South Korean Won – USDKRW
The won has slightly appreciated so far this year after tumbling since October 2024 by a cumulative 12% depreciation to the dollar both on domestic political developments and external concerns related to a less dovish Federal Reserve and trade policy risks. It had dropped to its weakest level in 15 years.
The Americas
The Canadian dollar and Mexican dollar weakened and retraced some since the mention of Trump tariffs on the two countries.
Canadian Dollar – USDCAD
The Loonie has been in a steady downtrend since 2021, on yield pressures, weakening economic metrics and political uncertainty. The USDCAD hit a 3 year high in June and corrected that in 3 waves led by the AUD and NZD with oil price impacting direction from there the selling of the Loonie resumed. From there it broke the 2020 highs and tested 1.48 before reverting back on tariff gamesmanships in 2025.
Mexico Peso – USDMXN
Mexico’s currency is part of a carry trade that involves investors borrowing in currencies that have low interest rates, such as the Japanese yen or Swiss franc, and buying higher yielding ones such as the Mexican peso or, recently, the U.S. dollar. It has boomed in popularity as interest rates have diverged around the world and market volatility has stayed low. after the Mexican election this year the peso had a dramatic fall against the yen – it dropped 4.4% on that Monday in its biggest daily decline since the COVID-19 crisis.
The peso had climbed to the strongest in almost nine years driven by relatively high local interest rates and low currency volatility until, that sell off.
Brazilian Real – USDBRL
December 19 – Bloomberg (Martha Beck, Vinícius Andrade, Maria Eloisa Capurro and Leda Alvim): “As the currency craters in Brazil, thrusting the country’s markets into the international spotlight for the first time in years, a grim reality is setting in for top economic aides to President Luiz Inacio Lula da Silva. They are, they fear, powerless to do much to stop the panic… The central bank has ramped up intervention in currency markets to try to stem the losses amid what Governor Roberto Campos Neto called an ‘atypical’ outflow. It has stepped in either directly or through swaps almost every day for the past week, spending close to $14 billion to give some support to the real… On Thursday alone it sold $8 billion in back-to-back spot auctions — that’s the biggest daily sale of dollars since at least 1999, when Brazil adopted a floating exchange rate regime…”
Europe
Euro – EURUSD
Euro continued to bump up against that downtrend line from 2020 and spinning around the 50% of that year’s panic sell. The euro trades in what seems like eternal flags in the channel. We watch if Kijun (pink) testing Tenkan (orange) creates any impulse as EURUSD consolidates under the cloud and break up level from 2022. Watch 3 waves to see development for continuation and for impulse off Chikou rebalance. Governed by EURGBP and Bund volatility.
British Pound – GBPUSD
British pound rose in a classic rising wedge since its late 2022 spike classic retest until its daily break late 2024 which brought a weekly kiss of death. From there a weekly cloud break with magnet pulls of cloud twist after ABC correction – will need Tenkan to break through Kijun for more strength. The upcoming months will be heavy on UK data and EU, Ukraine speculation which could mean an eventful time for the British pound.
Swiss Franc USDCHF
Turkey Lire USDTRY
Political instability erupted in Turkey at the hand of its autocratic and antidemocratic president on March 19. The Turkish lira immediately collapsed 12%, though record ($9bn) intervention reduced the day’s loss to 3.2%. Turkey’s central bank boosted short-term rates two percentage points to 46%. Yet the lira’s 3.1% loss was the largest weekly decline in almost two years. Turkish stocks were slammed 16.6%, with “banking stocks experiencing their worst weekly drop since at least 2001” (Bloomberg). Turkey’s local currency bond yield spiked 293 bps to 29.16%. “Turkish Lira Rout Sours Lucrative Carry Trade.” “Turkey’s Erdogan Warns Opposition Over Calls for Mass Protests.”
March 28 – Bloomberg (Ugur Yilmaz): “Ekrem Imamoglu, the Turkish opposition figure whose detention this month triggered mass protests and a market selloff, criticized Western leaders for their muted response to his arrest. In a piece published in The New York Times…, President Recep Tayyip Erdogan’s main political rival accused the US and Europe of prioritizing geopolitical interests over democratic values. ‘Their silence is deafening,’ Imamoglu wrote of world governments. ‘Washington merely expressed ‘concerns regarding recent arrests and protests’ in Turkey. With few exceptions, European leaders have failed to offer a strong response.’”
Cryptocurrenices
Bitcoin
Bitcoin is the world’s biggest digital asset; it had already staged a remarkable comeback in 2023. Then in January the approval of US Bitcoin exchange-traded funds was a further catalyst for gains. Donald Trump’s victory in November turbocharged BTC, sparking a record-breaking rally over the $100,000 level. Along the way, traders poured more than $100 billion into the ETFs, paving the way for similar crypto-related investment vehicles. At the opposite extreme, activity in memecoins, which often trade for a fraction of a cent, exploded.
Trump galvanized the digital-asset community with promises to reverse a US crypto crackdown under President Joe Biden and make America the center of the industry. In the weeks after the election, he announced the newly created post of czar for AI and crypto, and named industry proponent Paul Atkins to replace crypto nemesis Gary Gensler at the Securities and Exchange Commission.
This year also set a record for US ETF fund flows, with Trump’s presidential victory giving already emboldened investors even more incentive to double down. Funds that track the S&P 500 took the most flows, one of this year’s most notable new entrants was BlackRock’s Bitcoin ETF drawing the third-most inflows this year.
Bitcoin is performing technically to perfection. Impulse begets impulse. To understand panic, understand greed. Bitcoin exploded higher following its correction impulsively upon completing 5 waves up at +2/8. Each Tenkan and Kijun tap saw an explosive kiss of death until we completed 3 waves to around 28,000. From there we have seen extreme volatility to a new record high and retest.
We have seen what you would expect from a 5-wave impulse peak and ABC correction, a violent correction and completion. Use Murrey Math levels for corrections and targets as algorithms control the herd here, support is the cloud and sharp ABC, 1-2 moves. From there prices agitated towards those ATHs as news of a Bitcoin ETF fueled the rally, sound familiar? But this time it wasn’t signaling we are in a 3 high probability but a 5.
Solana
Ethereum
On the Risk Radar
Geopolitical Tinderbox Radar
The Week Ahead – Have a Trading Plan
WatchEarnings, Central Bankers and Geopolitics speeches, reportsandrate moves.
Next Week’s Risk Dashboard
Global Week Ahead Highlights
Powell and moral hazard
Tariffs put the US productivity miracle at risk
Firing the BLS head is a disturbing development
Watch the rumour mill for Fed Governor candidates…
Federal Reserve to cut 25bps…
…and increase implied easing in the dots…
…as it gambles on the balance of dual mandate risks…
…amid concern over political meddling
BoC to cut — cases for and against
Why the BoC should just leave CORRA alone
Canadian CPI — a high bar to derail a cut
BoE on extended hold?
UK jobs, CPI unlikely to influence BoE’s decision
BoJ to wait it out at least until fresh forecasts
Norges Bank’s cut guidance may have to wait longer
CBCT in no rush
BI could surprise amid political turmoil
BCB on an extended hold
SARB — what did you say your target was?
Aussie jobs — establishing a new trend
Other: US retail sales, Aussie jobs, NZ GDP, Canadian & LatAm releases
Tuesday: 6-week bills; $58 bln 3-yr Treasury note auction results at 13:00 ET
Wednesday: 17-week bills; $39 bln 10-yr Treasury note reopening results at 13:00 ET
Thursday: 4-, 8-week bills; $22 bln 30-yr Treasury bond reopening result at 13:00 ET; and August Treasury Budget (prior -$291.1 bln) at 14:00 ET
Central Bank Highlights
Updated July 25, 2025
CENTRAL BANKS
Federal Reserve—It’s All In The Dots—Until Next Time
The two-day FOMC meeting is expected to culminate in a decision to cut the fed funds policy rate by 25bps on Wednesday at 2pmET when the statement lands. The Committee will also release a fresh Summary of Economic Projections including a new ‘dot plot’ of policy rate expectations to provide a complete refresh of the forecasts of individual members. Chair Powell’s customary press conference will commence thirty minutes later and last for probably around 45 minutes, maybe more or less.
Almost all forecasters expect a 25bps rate cut. Fed fund futures are priced for -25bps and a touch more as some market participants retain a low probability of an outsized 50 move. That seems implausible.
On labor markets, Powell’s speech Jackson Hole flagged revisions but more importantly a bias toward erring on the side of ensuring the recent softness does not have further and deeper legs to it and in favor of acting pre-emptively which places the emphasis on the concluding part of this quote:
“This slowdown is much larger than assessed just a month ago, as the earlier figures for May and June were revised down substantially. But it does not appear that the slowdown in job growth has opened up a large margin of slack in the labor market—an outcome we want to avoid.”
Nevertheless, developments since Powell’s abrupt pivot have reinforced the importance of the pivot including:
another weak nonfarm payrolls report with just 22k jobs created in August that might have actually been even weaker than stated (recap here).
a record of just under one million jobs wiped off nonfarm payrolls in the annual benchmarking revisions as at March 2025 (chart 2). That chopped in half the average monthly gain in nonfarm payrolls to about 75k over the April 2024 to March 2025 period and indicated a materially weaker job market even before the Trump administration began tightening immigration.
Throughout it all is rising political pressure on the Federal Reserve that is of deep concern. The Trump administration is stacking the Board with two dovish Governors to date (Waller, Bowman), another waiting in the wings for Monday’s Senate confirmation vote (Miller), risks surrounding another Governor’s stature as courts weigh in on whether Trump can fire Lisa Cook or not especially given the revelation she properly disclosed her mortgage as a vacation property, and ultimately the coming appointment of a shadow Fed chair weeks from now.
Because of the high potential for meddling with the functioning of the Federal Reserve, markets may be wise to fade the dot plot that is offered at this meeting and not just because the further out one goes, the worse the dot plot performs (charts 3, 4). Notable changes from the June dot plot are likely. For one, the seven members who put down no cuts this year are likely to abandon ship in whole or as a majority. A key uncertainty is whether the median shifts 50bps of cuts this year to 75bps or more. With new information since June, it seems more likely than not that the median Committee member will add to easing. 75bps of cuts could imply cutting at each remaining meeting assuming the median member does not support an outsized move along the way. More than 75bps of cuts implies openness to at least one outsized move which seems unlikely.
As for next year, the Committee already had 75bps of cuts in its projections from now to the end of 2026. To leave it at that would be a hawkish signal to markets. More likely is that they will add a little more to easing given developments since June. And once again it’s highly unlikely that we should attached much significance to the Committee’s dispersed views on the neutral rate; the June estimates were all over the map (chart 5).
BANK OF CANADA—WEIGHING THE CUT VERSUS HOLD CASES & WHAT TO DO ABOUT CORRA
We expect the BoC to cut by 25bps on Wednesday and sound open to further easing in keeping with our forecast for 50bps of cuts this year until taking them back later next year. The statement arrives at 9:45amET and will be followed by a press conference hosted by Governor Macklem forty-five minutes later. The next MPR including updated scenarios or forecasts is due at the October decision. The BoC has demonstrated that it does not need an MPR to deliver a rate change.
Be Patient with CORRA
No other major policy shifts are expected at this meeting.
An issue of distant secondary concern relative to what they may do on the policy rate concerns developments across relative rates in funding markets. It may be too early for the BoC to react to the rise of the CORRA market rate above its policy rate to about 6bps (chart 9). As an aside, more ink has been splashed on this one topic by the street than what really matters: the policy rate.
For one thing, the wider spread is a very recent development concentrated in the first few days of this month. The BoC isn’t that reactionary. Further, they could be at risk of overreacting to a temporary situation if they roll out more aggressive policy options and therefore at risk of compounding funding market distortions and uncertainties.
The BoC may see the CORRA overshoot as a function of funding market developments amid rising speculation in Favour of pricing rate cuts as it did when this issue flared in 2024 and earlier this year. They issued staff research papers in 2024 explaining their staff’s position that the earlier distortions were due to market positioning (here and here). One of the authors (Boran Plong) is now employed on Scotiabank’s fixed income team. The synchronous increase in pricing for rate cuts and widening of the CORRA spread suggests something similar has happened now.
BANK OF ENGLAND—PAUSING AMID UNCERTAINTY
Markets and consensus unanimously expect the Bank of England to leave Bank Rate unchanged at 4% on Thursday. One reason is that the BoE has adopted the gradual mantra that has been executed by an alternating series of cuts and holds since August of last year. The extension of this pattern after cutting in August is a hold now.
It’s unlikely that fresh figures on jobs and inflation this week will influence this pattern (see data section later). Still, inflation remains too warm with ongoing heat across services. Governor Bailey expressed frustration toward the mixed set of activity and inflation readings after 125bps of cuts to date when he emphasized what is “now considerably more doubt about exactly when and how quickly we can make those further steps.” Markets have no further easing priced for this year’s remaining three meetings.
Other MPC members have expressed similar caution. Megan Greene noted signs that the “disinflationary process is slowing down.” Catherine Mann noted that “a more persistent hold on Bank Rate is appropriate right now.” Alan Taylor noted “we are in a fragile moment.” Deputy Governor Lombardelli said that neutral may be at the upper end of the 2–4% range estimated by the BoE and with Bank Rate already at 4%.
NORGES BANK—ABOUT THAT GUIDANCE…
Norges Bank may cut by 25bps on Thursday. Consensus mostly leans that way, but markets are somewhat on the fence between a hold and a cut. Why?
At its August meeting, the bank guided that “if the economy evolves broadly as currently envisaged, the policy rate will be reduced further in the course of 2025”, with June forecasts indicating “one or two additional rate cuts in the course of the year.” Chart 19.
With three meetings left this year, Norges may opt to retain some optionality on its prior guidance and whiff this time.
Further, since this guidance was offered, CPI inflation was sticky with August’s readings for total and underlying CPI inflation both above 3% y/y. GDP growth strongly exceeded expectations for Q2 (0.6% q/q SA nonannualized, 0.3% consensus, upward revisions).
BANK OF JAPAN—PAUSE FOR REFLECTION
Consensus and markets unanimously expect the Bank of Japan to leave its target rate unchanged at 0.5% on Friday. Markets begin to more significantly lean toward pricing a hike by the December meeting or later. Hints in favour of an ongoing tightening bias are also likely.
One uncertainty is underlying progress on core inflation. The Tokyo core CPI gauge was quite strong in earlier months before pressures subsided in June, July and August (chart 20). Yen appreciation since January stumbled over the period since Spring and further time may be taken to evaluate import price pressures, tariff effects, and oil prices as key drivers of inflation. The BoJ may also wish to have clearer indications about the next Shunto spring wage negotiations and give some distance from Prime Minister Ishiba’s resignation to evaluate future potential policy measures from government before its next full forecast update on October 30th after the last one in July.
BCB—OK, WE LISTENED!
Banco Central do Brasil is widely expected to remain on hold at a Selic rate of 15% on Wednesday.
The reason is simple. Its prior guidance stated a desire to remain on hold for a “very prolonged period” following 450bps of hikes since September of last year. Progress is being made on inflation but more is needed (chart 21).
That’s not the same as saying nothing interesting is happening to the outlook. Political risk and tariff risk remain acute not least of which after former President Bolsonaro was found guilty of an attempted coup and sentence to 27 years in prison. That invited threats from the Trump administration to retaliate in defence of Trump’s kindred spirit.
CBCT—IN NO RUSH
The Central Bank of China Taiwan is widely expected to be on hold on Thursday at a benchmark rate of 2%. It has been on hold since March of 2024. Since its last decision in June, the TWD has weakened, lessening some prior concern about its strength, but CBCT may wish to give more time to evaluate tariff effects and dollar stability since the TWD is still about 9% weaker to the dollar since April. Further, core inflation has risen and Q2 GDP growth was 8% y/y.
BANK INDONESIA—NERVOUS HOLD
Everyone in consensus expects Bank Indonesia to hold its policy rate at 5% on Wednesday. Uh oh.
This is one central bank with a proclivity toward surprises (chart 22). Bank Indonesia is expected to pause its easing cycle on Wednesday, after delivering back-to-back 25bps surprise rate cuts. The currency has been slightly weakening of late partly due to anti-government protests that sparked market turmoil. The catalyst was the firing of Indonesia’s finance minister in the wake of social unrest caused by long simmering inequality concerns and policy missteps including tone deaf housing allowances given to lawmakers. Cut to inject some confidence, or hold to stabilize the currency?
SARB—WHAT’S YOUR TARGET?
The South African Reserve Bank issues a policy decision on Thursday with consensus somewhat divided. A majority of forecasters expect the repo rate to hold at 7% but a sizeable minority expects a 25bps cut.
SARB’s July Quarterly Projection Model showed rates bottoming out at the current level after it cut by 25bps. It then muddied the waters with confusing guidance on its inflation target that may be further clarified at this meeting. Still, after Q2 GDP growth exceeded expectations, it may take a sharp surprise in Wednesday’s CPI update for August to motivate a cut.
Commentary via Scotiabank, Bloomberg
US Earnings Highlights
Monday: Dave & Buster’s Entertainment (PLAY), Radiant (RLGT).
Tuesday: Ferguson (FERG), Evolution Petroleum (EPM), Flux Power Holdings (FLUX).
Wednesday: General Mills (GIS), Nano Dimension (NNDM), Manchester United (MANU), Cracker Barrel (CBRL), Red Cat (RCAT)
Klarna among 6 large deals set to IPO in the coming week, some small deals may also join the calendar throughout the week.
E-commerce payments platform Klarna (KLAR) plans to raise $1.2 billion at a $13.7 billion market cap. The company is perhaps best known for its buy-now-pay-later plans, including its four-part interest-free payment plan. It also offers its own “Klarna Card” in partnership with Visa, and its own app offering cashback on e-commerce purchases made through it. Klarna posted strong revenue growth in 2024, and achieved a positive EBITDA margin, but its credit losses have increased substantially, and it faces significant competition.
Systems service provider Legence (LGN) plans to raise $702 million at a $2.8 billion market cap. The company provides engineering, installation, and maintenance services for mission-critical systems in buildings, specializing in designing, fabricating, and installing complex HVAC, process piping, and other mechanical, electrical, and plumbing systems for new facilities, and upgrading HVAC, lighting, and building controls in existing facilities. Legence has demonstrated growth through M&A, and could benefit from rising data center spend, but is highly levered, and its fixed-price contracts expose it to cost overruns.
Blockchain-based lending platform Figure (FIGR) plans to raise $500 million at a $4.5 billion market cap. The company offers a vertically integrated suite of blockchain-based solutions that powers its marketplaces across lending, trading, and investing, originating loans directly to borrowers while also enabling mortgage originators, servicers, banks, brokers, and credit unions to originate and distribute loans through its partner-branded technology platform. Figure has substantially grown loans originating from its platform, and revenue, and could benefit from interest rates cuts. However, it has a short track record of profitability in a somewhat commoditized and cyclical market.
Public transit services platform Via Transportation (VIA) plans to raise $450 million at a $3.8 billion market cap. The company develops technology for public transit agencies and operators to plan, manage, and optimize services such as microtransit, school transport, and paratransit. Its platform combines scheduling, dispatch, compliance, passenger booking, and data analytics, with optional services like fleet procurement and call center support. Via has posted strong revenue growth, and improving margins, but has a sizable accumulated deficit, and remains unprofitable.
Winklevoss-backed crypto exchange Gemini (GEMI) plans to raise $300 million at a $2.3 billion market cap. The company is a regulated cryptocurrency exchange serving retail and institutional clients in over 60 countries, offering spot and derivatives trading, staking, OTC trading, custody, a stablecoin, and other crypto-related products. Gemini’s trading volumes have jumped substantially, and the regulatory environment surrounding crypto is becoming clearer, but the company remains highly dependent on volatile crypto prices and volumes, and still has a small market share with a history of losses.
Coffee chain Black Rock Coffee (BRCB) plans to raise $250 million at an $813 million market cap. The company operates drive-thru and sit-in coffee bars, offering various types of caffeinated beverages. It has 158 locations spanning seven states as of June 30, 2025. Black Rock has posted strong unit growth and same store sales growth in recent periods, but faces rising costs due to inflation and tariffs, and remains geographically concentrated in a handful of states..
Source: Renaissance Capital
Focus on yourself and what YOU CAN INFLUENCE, set your trading plan and goals in be set for 2025.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.