March 29, 2025
FEAR NOT Brave Investors
Where have we been and where are we going? Join our weekly market thread on Traders Community…

Market Dynamics and Instability
The Week That Was – What Lies Ahead?
Fear and Greed Feed Volatility
Contents
Click on the links below to navigate to the relevant section.
- Part A: Stock markets
- Part B: Bonds
- Fed and Banks
- Part C: Commodities
- Energy – Oil and Gas
- Gold and Silver
- Part D: Foreign Exchange
- Geopolitics and Economics
- Economy Week ahead

Editorial
Early in the week stock markets continued higher from last week’s test of the breakdown, however multiple concerns saw that reverse ending with notable losses across major indices. At this critical market juncture, further weakness risks acute instability. The market narrative views market weakness as reflecting tariff angst and nervousness ahead of “liberation day.” The unappreciated, yet overarching, issue is one of a looming day of reckoning. Significantly the S&P 500 spat it’s 200-day moving average after closing above it early in the week. The index finished the week down 1.5%, the Dow Jones Industrial Average fell by 1%, and the Nasdaq Composite down 2.6%.
Again, we saw convergence of rising inflation after the Core PCE data, declining consumer confidence, and trade policy (tariffs) uncertainties. President Trump announced a 25% tariff on all imported passenger vehicles starting April 3. He also said reciprocal tariffs will go on for all countries, but that the U.S. will be very lenient.
Stagflation
Stagflation risks came back to the fore hurting markets after the Personal Consumption Expenditures report was good on the income side, but the spending side is just hanging in there (real PCE up just 0.1%) and was bad on the inflation side with the uptick in the core-PCE Price Index (the Fed’s go to) by 0.4%, bringing the annual rate to 2.8%. Potentially mixing toxic cocktail to stir some stagflation angst for the Fed in a wait-and-watch mode on rates.

With all the negative press, job and inflation worries the Consumer Confidence Index understandably revealed a fourth consecutive decline. The Expectations Index fell to its lowest level (65.2) in 12 years, with future employment prospects and inflation concerns weighing.
Following the affective dead cat bounce in Tech stocks the same stocks peppered the reversals back down. The S&P technology sector was down 3.7%. The Bloomberg MAG7 Index closed the week only slightly above March 11th intraday lows, with the S&P500 ending the week 1.4% off March 13th trading lows. NVIDIA (NVDA) dropped 6.8%, Microsoft (MSFT) dropped 6.8%, and Amazon.com (AMZN) dropped 1.8%. The equal-weighted S&P 500 fell 1.2%. Just four S&P 500 sectors finished higher on the week with consumer staples best with a 1.7% gain.
Treasury bonds rallied hard after the week’s data with the 5-yr yield back below its 200-day moving average (4.069%) to its lowest settlement in nearly three weeks while the 10-yr yield finished the day just above the 200-day moving average of 4.223%. This week’s outperformance in shorter tenors widened the 2s10s spread by five basis points to 35 bps.
Transitory
After the most recent FOMC during his press conference, Fed Chairman Powell brought the ‘Transitory word back and reiterated there is no rush to adjust policy. “Transitory” was spoken five times during the post-meeting press conference, twice by Chair Powell. He warned that it is “going to be very difficult to have a precise assessment of how much inflation is coming from tariffs.” He indicated that it’s “kind of the base case” that inflationary pressures from tariffs would be transitory, adding that the last time tariffs were imposed, the increase in prices was transitory. The market remains on high alert about the specter of reciprocal tariffs being announced on April 2.
Chair Powell: “As I’ve mentioned, it can be the case that it’s appropriate sometimes to look through inflation if it’s going to go away quickly without action by us, if it’s transitory. And that can be the case in the case of tariff inflation. I think that would depend on the tariff inflation moving through fairly quickly and critically, as well on inflation expectations being well-anchored, longer-term inflation expectations being well-anchored.”
Central banks are hamstrung by elevated inflation and trade war risks. No time like the present, no less than eleven global central banks will weigh in with monetary policy updates this week. This includes three of the big dogs, the Federal Reserve, Bank of Japan and the Bank of England. Patience is required given the uncertainty and the many possible burifications from how they act and communicate. No doubt, whether as an excuse or because they genuinely are, less confidence in the path forward will feature prominently in the communications.
A dangerous market for those not trading with discipline and booking profits. Not one with emotion and preset views dictated by hope, politics or a talking head’s opinion.
Quick Look at The Week Gone By:
- Dow Jones Industrial Average: -2.3% YTD
- S&P 500: -5.1% YTD
- S&P Midcap 400: -6.6% YTD
- Russell 2000: -9.3% YTD
- Nasdaq Composite: -8.4% YTD
- Gold futures settled $23.40 higher (+0.8%) at $3,114.30/oz Friday, up about +3.1% on the week.
- 2-yr: -9 bps to 3.91% (-4 bps this week)
- 3-yr: -10 bps to 3.90% (-3 bps this week)
- 5-yr: -12 bps to 3.98% (-3 bps this week)
- 10-yr: -11 bps to 4.26% (+1 bp this week)
- 30-yr: -10 bps to 4.63% (+3 bps this week)
- This week’s outperformance in shorter tenors widened the 2s10s spread by five basis points to 35 bps.
- Crude oil narrowed this week’s gain to just over $1/bbl Friday
- The U.S. Dollar Index fell 0.3% to 104.02 Friday, shedding 0.1% for the week.
Geopolitical contagion impacts were generally subtle
Political instability erupted in Turkey at the hand of its autocratic and antidemocratic president.
The Turkish lira immediately collapsed 12%, though record ($9bn) intervention reduced the day’s loss to 3.2%. Turkey’s central bank boosted short-term rates two percentage points to 46%. Yet the lira’s 3.1% loss was the largest weekly decline in almost two years. Turkish stocks were slammed 16.6%, with “banking stocks experiencing their worst weekly drop since at least 2001” (Bloomberg). Turkey’s local currency bond yield spiked 293 bps to 29.16%. “Turkish Lira Rout Sours Lucrative Carry Trade.” “Turkey’s Erdogan Warns Opposition Over Calls for Mass Protests.”
Some key EM currencies reversed lower. For the week, the Mexican peso declined 1.5%, the Colombian peso 1.1%, the Polish zloty 0.9%, and the Indonesian rupiah 0.9%. Brazil’s real (up 0.2%) was supported by a 100 bps increase in the main policy rate to 14.25% – the high back to October 2016. EM CDS spiked to the high since August 6th. “Chinese Stocks in Hong Kong Cap Worst Two-Day Drop Since October.” “Trump’s ‘Big One’ on Tariffs Has Emerging Market on Edge.”
Leveraged loan new deal volume last week was the slowest of 2025. According to Bloomberg, there have been six offerings “pulled from syndication in the last few weeks…” It’s worth noting that the stocks of leading public “private credit” firms have been under heavy selling pressure. Apollo Global Management is down 18.4% y-t-d, Blackstone 17.6%, and KKR 23.3%. “Subprime” Credit Bubble instability has a tendency to erupt quickly, with wide ramifications.
Mega cap stocks had an outsized impact on the broader equity market.
Central Banks This Week
- San Francisco Fed President Daly (non-voter) expects two rate cuts this year, according to Reuters.
- European Central Bank Policymaker De Guindos spoke favorably about inflation returning to target
- Bank of England Governor Bailey said that inflation risks in the U.K. remain elevated.
- Japan’s Prime Minister Ishiba floated a plan to offer liquidity support to companies impacted by tariffs. The Bank of Japan’s summary of opinions from its March meeting showed that the central bank will need to downshift its accommodative stance to a neutral one.
- Reserve Bank of Australia Governor Bullock warned against premature easing.
This week’s key U.S. Economic Reports:
- Japan’s Flash Manufacturing PMI for March (48.3; prior 49.0) showed a deepening contraction while readings from Australia (52.6; prior 50.4) and India (57.6; prior 56.3) showed an acceleration in activity.
- Eurozone flash March Manufacturing PMI 48.7 (expected 48.3; last 47.6) and flash Services PMI 50.4 (expected 51.2; last 50.6). Germany flash March Manufacturing PMI 48.3 (expected 47.1; last 46.5) and flash Services PMI 50.2 (expected 52.3; last 51.1) U.K. flash March Manufacturing PMI 44.6 (expected 47.3; last 46.9) and flash Services PMI 53.2 (expected 51.2; last 51.0). France flash March Manufacturing PMI 48.9 (expected 46.2; last 45.8) and flash Services PMI 46.6 (expected 46.3; last 45.3)
- US flash March S&P Global Manufacturing PMI – Prelim 49.8; Prior 52.7, March S&P Global US Services PMI – Prelim 54.3; Prior 51.0
- January FHFA Housing Price Index 0.2%; Prior was revised to 0.5% from 0.4%. January S&P Case-Shiller Home Price Index 4.7% (consensus 4.6%); Prior 4.5%
- March Consumer Confidence 92.9 (consensus 94.2); Prior was revised to 100.1 from 98.3. The decline in consumers’ outlook was driven by worries about inflation and future employment prospects, the latter of which hit a 12-year low.
- February New Home Sales 676K (consensus 680K); Prior was revised to 664K from 675K
- Weekly MBA Mortgage Applications Index -2.0%; Prior -6.2%
- February Durable Orders 0.9% (consensus -1.2%); Prior was revised to 3.3% from 3.1%, February Durable Goods – ex transportation 0.7% (consensus 0.1%); Prior was revised to 0.1% from 0.0%. But there was a downturn in business spending, evidenced by the 0.3% decline in nondefense capital goods orders, excluding aircraft.
- Q4 GDP – Third Estimate 2.4% (consensus 2.3%); Prior 2.3%, Q4 GDP Deflator – Third Estimate 2.3% (consensus 2.4%); Prior 2.4%
- Weekly Initial Claims 224K (consensus 225K); Prior was revised to 225K from 223K, Weekly Continuing Claims 1.856 mln; Prior was revised to 1.881 mln from 1.892 mln
- February Adv. Intl. Trade in Goods -$147.9 bln; Prior was revised to -$155.6 bln from -$153.3 bln
- February Adv. Retail Inventories 0.1%; Prior was revised to 0.1% from -0.1%
- February Adv. Wholesale Inventories 0.3%; Prior was revised to 0.8% from 0.7%
- February Pending Home Sales 2.0% (consensus 2.9%); Prior -4.6%)
- February Personal Income 0.8% (consensus 0.4%); Prior was revised to 0.7% from 0.9%, February Personal Spending 0.4% (consensus 0.6%); Prior was revised to -0.3% from -0.2%, February PCE Prices 0.3% (consensus 0.3%); Prior 0.3%, February PCE Prices – Core 0.4% (consensus 0.4%); Prior 0.3%
- March Univ. of Michigan Consumer Sentiment – Final 57.0 (consensus 57.9); Prior 57.9. Expectations Index has dropped more than 30% since November 2024. The decline in March featured a clear consensus across all demographic and political affiliations, citing worsening expectations for personal finances, business conditions, unemployment, and inflation.
Tariff Tampering
FOMC Presser Chair Powell said this:
- “It is going to be very difficult to have a precise assessment of how much is coming from tariffs. Goods inflation moved up this year but it’s very challenging to trace it back to non-tariff inflation versus tariff inflation. In terms of looking through, it’s too soon to say that. Sometimes it’s appropriate to do that. That would depend on tariff inflation moving through pretty quickly and longer-term inflation expectations being well anchored.”
- He went on to note that “We were getting closer and closer to price stability but we were not at that. The arrival of further tariff inflation could delay this. The forecast does show us getting into the low 2s further out.” And so the message is that for now they are erring on the side of caution by raising inflation and becoming more patient on timing further easing.
The trade war deepened after President Trump announced that the US will impose a 50% tariff on Canadian steel and aluminum imports, starting Wednesday, instead of the originally proposed 25%. The escalation followed a retaliatory measure by Ontario, which imposed a 25% tariff on exports of electricity to the U.S. in response to the originally planned 25% tariffs on Canadian imports.
President Donald Trump also announced a potential 200% tariff on European beverage imports, including wines and spirits. This move was in response to the European Union’s recent tariffs on American whiskey.
The prior week we saw 25% tariffs for Canada and Mexico go into effect and tariffs on China rose by 10% to 20%, and the countries responded with retaliatory measures. The 25% tariff for Canada and Mexico were revised, such that all USMCA compliant goods from Canada (~38%) and Mexico (~50%) will be exempt from tariffs until April 2.
China: Plans appear to undercut “MAG seven,” stocks that dominate U.S. indices and companies that spend hundreds of billions. DeepSeek the first meaningful shot across the bow. Expect plays to disrupt the USA by advancing plans for Taiwan “unification”. USA is not unaware given the TSMC deal this week for example.
- “China’s top diplomat chided the Trump administration and said efforts to contain the country’s rise were destined to fail, presenting Beijing as a force for global stability in a rejection of U.S. policy under President Trump. ‘No country should harbor the illusion that it can suppress and contain China while simultaneously building good relations with China,’ Foreign Minister Wang Yi said… ‘Such two-faced methods are not only detrimental to the stability of bilateral ties but also make it impossible to build mutual trust.’ Wang’s strident comments reflected Beijing’s determination to stand up to U.S. pressure…” March 7 – Wall Street Journal (Brian Spegele and Austin Ramzy)
- “More than anything, China’s embrace of open-source artificial intelligence systems will be what tips the scales in its favor in the heated tech race with the US. Washington and Silicon Valley now have a limited window to adapt and respond, or risk a future where Chinese AI overwhelmingly powers the products and applications used by the global industries of tomorrow. The DeepSeek shock earlier this year provided the first wake-up call… But the second came this week, in the closely read policy report released at the National People’s Congress in Beijing.” March 6 – Bloomberg (Catherine Thorbecke)
Canada: Outwardly most sectors of the economy are likely to escape US tariffs if they can prove to be CUSMA compliant. Over 40% of trade is already CUSMA-compliant and the sense is that the majority of the rest could quickly become CUSMA-compliant.
- Risk is tariffs on steel and aluminum, 10% tariffs on energy products and potash that fall outside of CUSMA preferences and if Trump carries through on his threat to impose reciprocal tariffs on dairy and lumber.
- There is likely to be high pass through of tariffs into US prices in sectors like aluminum, given Quebec’s dominance and lumber, given the large market share of Canadian producers and the spillover effects into broader lumber prices that has already been occurring. Americans will simply have to pay more.

*** Economic summaries via Briefing
Geopolitical: Chaos Ramps Up
Greenland
- President Trump (March 27, 2025): “So we’ll, I think, we’ll go as far as we have to go. We need Greenland. And the world needs us to have Greenland, including Denmark. Denmark has to have us have Greenland. And, you know, we’ll see what happens. But if we don’t have Greenland, we can’t have great international security.”
- President Trump (March 28, 2025): “We need Greenland, very importantly for national security. We have to have Greenland. It’s not a question of, ‘Do you think we can do without it?’ We can’t… Greenland’s very important for the peace of the world. And I think Denmark understands, and I think the European Union understands it. And if they don’t, we’re going to have to explain it to them.”
South China Sea
- March 28 – Daily Mail (Geoff Earle): “Defense Secretary Pete flexed his muscles in a workout with U.S. troops in the Philippines as he identified China as a threat and called for deterrence. ‘There’s a long line of countries in the past who have attempted to test U.S. resolve… We are resolved at this time… to work with our partners.’ ‘Deterrence is necessary around the world, but specifically in this region, in your country, considering the threats from the communist Chinese,’ he said. Hegseth… called for joining with allies to counter Chinese expansionist threats… ‘What we’re dealing with right now is many years of deferred maintenance, of weakness, that we need to reestablish strength and deterrence in multiple places around the globe,’ Hegseth said in response to a question about whether the U.S. would place a more visible presence in the South China Sea.”
- Hegseth: “What the Trump administration will do is deliver – is to truly prioritize and shift to this region [Asia] of the world in a way that is unprecedented.”
- March 28 – Associated Press (Jim Gomez): “U.S. Defense Secretary Pete Hegseth said… the Trump administration would work with allies to ramp up deterrence against threats across the world, including China’s aggression in the South China Sea. Hegseth… blamed the previous Biden administration for insufficient actions that emboldened aggressors like China over the years. He said the U.S. military was being rebuilt under President Donald Trump and was re-establishing its ‘warrior ethos’ in the region… Hegseth told a news conference with his Philippine counterpart, Gilberto Teodoro, after meeting President Ferdinand Marcos Jr…”
Recap: If Ukraine agrees to the rare earth deal, it helps justify the cost, helps take some China retaliation risk off but the big one it makes Ukraine less vulnerable to Putin’s stated aim of taking all of Ukraine. Why? Much of the critical minerals are in the Eastern regions of Ukraine (Donbas) captured by Russia. This makes it more palatable to the U.S to support and protect and Trump has got the response he wanted from the EU, increase your share of the military cost of NATO. Now we will see if these assumptions are correct over the coming weeks.
Market Response to German Change in Military infrastructure Spending
What (should) matters to traders and investors is the markets response
- “German Bonds Cap Worst Week Since Before Country’s Unification.” Bund yields surged 43 bps to 2.84%. Despite the historic yield spike, there was little indicating notable instability in the realm of levered speculation – i.e., “basis” and “carry trades.” “Basis trades” (levered long cash bonds versus short futures) are largely immune to yield gyrations. Importantly, the big peripheral European “carry trade” (short lower yielding German bunds to finance levered longs in higher-yielding periphery bonds) made it through the week unscathed. Only Spanish yields (up 45bps) rose more than bunds, with Italian and Portuguese yields rising 42 bps, and French and Greek yields jumping 41 bps. European bank and corporate debt CDS increased only moderately.
- The euro posted its best week (up 4.4%) since March 2009. Surging 6.8%, the Swedish krona’s advance was the strongest all the way back to the eighties. Clearly, hedge fund strategies were poorly positioned for the week’s currency market fireworks.
- For the most part, dollar weakness underpinned EM currencies and equities. The Hungarian forint jumped 5.6%, the Polish zloty 5.0%, the Czech koruna 4.9%, the Romanian leu 4.4%, the Bulgarian lev 4.4%, and the Chilean peso 3.7%.
- With this week’s 25 bps (to 2.65%), the ECB has now cut rates 185 bps since June. Meanwhile, bund yields have jumped 32 bps, French yields 57 bps, and Italian yields 13 bps.
- Pain aplenty in European EM bonds. Local currency yields surged 34 bps in Cyprus and Slovakia, 31 bps in Slovenia, 30 bps in Czech Republic, 24 bps in Latvia, and 22 bps in Romania.
- Bond weakness was not isolated to Europe. Yields jumped 13 bps in Canada and 11 bps in Australia and New Zealand. Chinese yields rose seven bps (“worst slide this year”) to a three-month high of 1.85%.
- The Bloomberg “MAG 7” index, having now given up the entire post-election rally, sank 4.5% this week, boosting its y-t-d decline to 10.7%.
- A $439 billion rally in Chinese tech megacaps has seen the ‘7 titans’ by Societe Generale SA equal-weighted basket of China’s seven tech heavyweights including Alibaba Group Holding Ltd. and Tencent Holdings Ltd. gain more than 40% this year. That compares with the 10.7% drop in the Magnificent Seven stocks, whose slump has pushed the Nasdaq 100 Index to the brink of a correction.
- The KBW Bank Index sank 8.8%, with the Broker/Dealers down 5.2% this week. Ominously, financial stocks were hammered. While financial conditions remain loose, the shock to consumer and business confidence portends economic and Credit vulnerability.
- “Leveraged loan prices took a notable leg lower as growth fears rekindle credit risk concerns. US loan prices… posted their biggest drop since August on Tuesday, showing how quickly the repricing in this asset class can be. The loan market has been on fire in recent months, with prices rising to the highest since 2022 and year-to-date issuance swelling to the highest since Bloomberg began tracking the data in 2013.” March 6 – Bloomberg (Tatiana Darie)
Week Ahead Catalysts
- In the week ahead US reciprocal tariffs, Russia and Ukraine talks, and US budget negotiation will dominate developments. The market narrative views market weakness as reflecting tariff angst and nervousness ahead of “liberation day.” The unappreciated, yet overarching, issue is one of a looming day of reckoning.
- Mon: Optical Fiber Communication Conference in San Francisco, four-day event is seen by analysts being relevant to Broadcom (AVGO), Marvell Technology (MRVL), Coherent (COHR), Credo Technology (CRDO), Lumentum (LITE). Intel (INTC) will hold its two-day Intel Vision event
- Tue: Deliveries from Tesla (TSLA), Nio (NIO), XPeng (XPEV), Rivian Automotive (RIVN), Li Auto (LI), ZEEKR Intelligent (ZK), Polestar Automotive (PSNY), and Lucid Group (LCID). Quarterly sales reports from General Motors (GM), Ford Motor (F), and Toyota (TM). Monthly Macau gross gaming revenue release, the monthly update on Class 8 truck orders, firearm background check data from the FBI, and discount broker DARTs reports. Bloomberg will publish its OPEC production survey for March.
- Wed: “Liberation Day” Details of the U.S. reciprocal tariffs will be announced. Nintendo (OTCPK:NTDOY) is holding a reveal event for the Nintendo Switch 2. National Retail Federation State of Retail & the Consumer 2025 event. BJ’s Wholesale Club (BJ) CEO Bob Eddy, Walmart (WMT) U.S. President John Furner, and Tapestry (TPR) CEO Joanne Crevoiserat speak.
- Thu: The U.S. will start collecting duties on imported vehicles and auto parts. The tariff applies to all imported cars and light trucks not manufactured in the United States, as well as foreign-made auto components. Meeting of NATO foreign ministers could have implications for the defense sector
- Fri: March U.S. Jobs Report will be released. Warner Bros.’ (WBD) Minecraft movie will premiere in the U.S. forecast to bring in between $55M to $75M during its opening weekend and see a total global haul of over $1 billion. McDonald’s (MCD) is looking to cash in on the buzz with various menu promotions tied to the movie. Microsoft (MSFT) special media event at its headquarters in Redmond to celebrate its 50th anniversary. New consumer AI and Copilot announcements are expected. Federal Reserve Chairman Jerome Powell will speak at the SABEW conference in Arlington, Virginia.
Debt …. Keeps Building
An overheating economy, coupled with tariff and trade war risks, creates a bond market challenge.
“Chuck E. Cheese owner CEC Entertainment is struggling to drum up enough demand for a $660 million high-yield bond sale to refinance debt it has due next year, according to people familiar… JPMorgan… and Goldman Sachs…, the banks leading the deal, had not obtained sufficient orders from investors… One of the people attributed the difficulties to a broader market rout stemming from concerns about the Trump administration’s tariff policies as well as the US economy… Other transactions in the leveraged finance market that are vulnerable to a dip in consumer spending, including casino operator Mohegan Tribal Gaming Authority, have faced investor pushback lately partly because of concerns about the US economy.” March 28 – Bloomberg (Aaron Weinman and Gowri Gurumurthy):
“Several Southern California cities have the most credit card debt per household in the U.S., a new WalletHub study found. Santa Clarita ranked first out of 181 U.S. cities, with a household average of about $22,753 in credit card debt, and a total of about $1.7 billion in debt for its 228,000 residents, according to data taken from the U.S. Census Bureau and TransUnion… Chula Vista was second, with an average of $20,567 in credit card debt per household, and a total of $1.8 billion among its 275,000 residents.” March 21 – Los Angeles Times (Sandra MacDonald):
A Reminder: U.S. and global yields surged higher as the Fed began its easing cycle:
- Ten-year Treasury yields, closing September 17th at 3.65%, ended the year 92 bps higher at 4.57%.
- EM bonds were taken behind the woodshed. For the quarter, spikes in dollar-denominated yields included Panama 177 bps, Brazil 137 bps, Mexico 99 bps, Peru 87 bps, Chile 85 bps, Indonesia 83 bps, Philippines 75 bps, Saudi Arabia 71 bps, and Turkey 58 bps.
- The spike in local currency bond yields was even more dramatic: Brazil 272 bps, Colombia 177 bps, Mexico 109 bps, Turkey 87 bps, Chile 85 bps, Romania 78 bps, Poland 64 bps, Indonesia 54 bps, and the Czech Republic 42 bps.
Was DeepSeek the beginning of the end of the AI Speculative Bubble?
Googles response to DeepSeek
- Alphabet’s Google launched two new AI models on March 12 for robotics applications on its Gemini 2.0 model. Last month robotics startup Figure AI exited its collaboration agreement with ChatGPT-maker OpenAI after it made an internal breakthrough in AI for robots.
- Gemini Robotics is an advanced vision-language-action model that will have physical actions as a way to provide output. The second model, Gemini Robotics-ER, will enable a robot to have an advanced understanding of the space around it and lets developers run their own programs using reasoning abilities offered by Gemini 2.0.
- Google said its models are designed for robots of all form factors including humanoids and other types used in factories and warehouses. Apptronik raised $350 million in a funding round last month led by B Capital and Capital Factory, with participation from Google to scale production of AI-powered humanoid robots.
Basis and Carry Trade Sustainable?
Risk Matters: Don’t forget the August 5th, 2024, Carry Trade Shake:
Discipline with your trading rules, especially as liquidity falls
There is a reason we have strict trading rules here based on psychology, math, experience and avoiding false narratives and dribble out there. That said pay attention to the time of year, the bonus pay dates (no we aren’t being cynical), tax markings and look the previous run ups into Dec 31. Don’t let the grifters out their sway you, VIX is historically low, what does that tell you? Protection is cheap and the market is complacent with no fear. Here endeth the lesson.
Two paths to bankruptcy: gradually and suddenly. – Ernest Hemingway
Where is the Fear in Instability?
Leveraged speculation, including “basis trades,” “carry trades” and run deep and why the yen and Mexican peso are deeply relevant to this whole structure.
Thursday and Friday’s (March 27-28) combined 35 bps spike (to 377 bps) was the largest since August 1st and 2nd.
- High yield CDS jumped 28 bps this week – to the highest close since August 7th (382bps). This was the largest weekly gain since the bout of global deleveraging during the week of August 2nd.
- High yield spreads widened 18 bps Friday (23bps wider on the week) to 3.40 percentage points, the largest single-session widening since August 5th – to the high back to August 13th.
- Investment grade CDS rose two bps this week to 62 bps, the high since December 7, 2023.
- Bank CDS (JPMorgan, BofA, Goldman, Citi and Morgan Stanley) all closed the week at highs (at least) back to August.
- Ten-year Treasury yields were down a notable 11 bps in intense Friday safe haven buying, as the implied rate for the December Fed funds rate dropped 10 bps to 3.60% (implying 73 bps of rate reduction).
Compressed risk premiums and CDS prices are indicative of complacency. Markets behave this way when there is some underlying monetary disorder (dislocation in liquidity creation). What all this does for markets is keep risk measures on, we see in the vicious VIX fails and short-term option volumes. It is when the risk avoidance measures, or tolerance fails this can trip up the whole structure of buying and cycling through risk assets.
In the backdrop we have war abroad in the Ukraine and Middle East, unsettled relations between Taiwan and China. At home in the US universities and cities to the North have become a quagmire of protest, illegal immigration placement and political vitriol that have deeply divided these regions. The cost of living through it all has sent many working through middle class families to the brink and beyond, insurance costs have risen over 100% in a year in some cases to name just one inflation cost that politicians lie about.
While complacency reigns supreme in equities bonds are awake to the risk out there. The MOVE (bond volatility) Index rose another five the week prior to the election, to a one-year high 133. The VIX for its’ part was crushed after the election.


“We have a market trying to interpret the Fed who is trying to find out how they can interpret their long-only portfolio at a risk parity where rates cannot rise.”– MoneyNeverSleeps
Our weekly reminder for risk, timely given the V shape to ATH. The downside is clear with the absence of moral hazard from repeated Federal Reserve market bailouts in an environment of some would say obscene liquidity pumps. Pure greed is the other part, not wanting to miss out on fees. The obvious question is, how deeply ingrained is this attitude through the markets? How do we ween the markets off this continuous dip feed? At this point the Central Banks have kicked that answer down the road.
Our take remains the Fed is not just focused on inflation but risks such as the commercial real estate debacle. the high US dollar and the massive Federal debt refunding cost.
We need to grasp all the risks to be wary of but not ignore price reaction. We always talk here about expect the unexpected and now that is front and center, gage the market’s reaction, the market is always right and that’s why we focus on the crowd psychology aspect.
Unsuspecting investors in their millions have or will lose meaningful amounts of their savings. They bought into the mania, threw caution to the wind, and will suffer the consequences regardless of the warnings of unsustainability. The reason we started TradersCommunity was for situations like this many moons ago. Beware of those ‘experts’ who never saw the sell off and chided you for believing it now claim to be gurus measuring risk. It’s a bit late when some of these stocks and markets are down 50-90%. Beware of those who claim long term investment when it all goes wrong. Anyhoo..
Oh China
In September 2024 Xi Jinping promised to spend whatever it takes to reach growth targets as he tapped the reflation panic button. A Reuters article placed Beijing’s stimulus at $1.4 TN. On top of a system locked in massive credit expansion, upwards of $5 TN annually. He is pushing hundreds of billions to the stock market, hundreds of billions to the festering local government sector, hundreds of billions to the to attempt to arrest the slide in the apartment markets.
January 31 – Bloomberg: “China’s residential sales resumed falling in January… The value of new-home sales from the 100 biggest real estate companies dropped 3.2% from a year earlier to 227.6 billion yuan ($31.4bn), after being flat in December… Beijing is struggling to revive the property market amid weak domestic demand and a worsening job situation. While the housing sector has picked up modestly on the back of government support, improvements have mostly been in the second-hand market as buyers remain concerned about developers’ ability to finish projects on time.”
January 27 – Financial Times (Thomas Hale and Chan Ho-him): “Leading Chinese property developer Vanke has forecast a $6.2bn annual loss and announced the sudden resignation of its top leadership, reigniting concerns over funding and confidence across China’s economically critical real estate sector. The developer, partly owned by local authorities in Shenzhen, is the latest focal point of a cash crunch that began with the collapse of peer Evergrande in 2021 and has since engulfed a host of other developers including Country Garden. After weeks of swirling concerns over the health of Vanke, the company said… chair Yu Liang had resigned for ‘work adjustment reasons’. It said chief executive Zhu Jiusheng had departed for ‘health reasons’. The ‘sudden and simultaneous’ resignations were ‘unprecedented in recent memory’ for a big participant such as Vanke, said Foreky Wong, founding partner at Hong Kong advisory company Fortune Ark Restructuring.”
January 28 – Bloomberg: “China Vanke Co. has been thrown a lifeline by state authorities, a rare show of support that signals the developer may be too big to fail even after dozens of property firms defaulted amid China’s punishing housing slump. As part of an overhaul unveiled late Monday, Vanke’s two top veteran executives stepped down after the company warned of a record $6.2 billion loss. An official from Shenzhen Metro Group Co., its largest state shareholder, will take over as chair.”
December 18 – Financial Times (Demetri Sevastopulo): “China has increased its arsenal of operational nuclear warheads to 600 from 500 in just a year, as the People’s Liberation Army continues a rapid expansion of its forces, according to the US defense department. In its annual ‘China Military Power Report’, the Pentagon said the PLA had expanded its arsenal by 20% in the 12 months from mid-2023 and was on track to have 1,000 operational warheads by 2030. The Pentagon has in recent years warned that the US will soon face two nuclear peers as China’s arsenal grows closer in size to the US and Russia.”
December 16 – Reuters: “China’s capital markets outflow reached a record high of $45.7 billion in November, according to official data tracking cross-border payments, as Donald Trump’s U.S. presidential election win roiled global portfolio flows. Cross-border receipts from portfolio investments were $188.9 billion, while payments totaled $234.6 billion, resulting in the biggest monthly deficit on record…”
Any pushback to fledgling tightening these days ensures excessively loose financial conditions.
Geopolitical Tinderbox

PART A – Stock Markets
Highlights This Week – USA
- S&P500 fell 1.5% (down 5.1% y-t-d),
- Dow lost 1.0% (down 2.3%).
- Nasdaq100 slumped 2.4% (down 8.2%).
- S&P 400 Midcaps fell 1.0% (down 6.6%),
- Small cap Russell 2000 declined 1.6% (down 9.3%).
- Utilities were unchanged (up 5.4%).
- The Banks dropped 1.9% (down 5.1%),
- Broker/Dealers slumped 2.3% (up 0.9%).
- Transports were little changed (down 8.2%).
- Semiconductors sank 6.0% (down 14.0%).
- Biotechs fell 2.0% (down 0.6%).
- With bullion jumping $63, the HUI gold index rose 2.0% (up 30.4%).

Highlights – Europe Stocks
- U.K.’s FTSE equities index was little changed (up 5.9% y-t-d).
- France’s CAC40 lost 1.6% (up 7.3%).
- German DAX equities index slumped 1.9% (up 12.8%).
- Spain’s IBEX 35 equities index slipped 0.3% (up 14.8%).
- Italy’s FTSE MIB index declined 0.8% (up 13.3%).
Highlights – Asia Stocks
- Japan’s Nikkei 225 Equities Index declined 1.5% (down 7.0% y-t-d).
- South Korea’s Kospi sank 3.2% (up 6.6%).
- India’s Sensex equities index increased 0.7% (down 1.4%).
- China’s Shanghai Exchange Index declined 0.4% (unchanged).
Highlights – Australian Stocks
- Australia’s ASX 200: Friday +0.5% to 7789.7 (-1.99% on the week) Well Off Record high
- The S&P/ASX 200 Index recording its third-largest weekly loss this year despite a rally in Australian iron ore and gold mining stocks.
- Friday: Seven of 11 sectors were higher, with utilities and miners leading the gains. Major miners tracked a rise in Singapore iron ore futures, which climbed 1.3% to $US103.55. BHP gained 1.1% to $38.65 and Fortescue rose 2.7% to $16.27. Gold miners rallied after gold hit $US2990.02 an ounce – a fresh record and posted its best week of gains this year. Newmont jumped 5.7% to $73.43 and Regis Resources added 5.6% to $3.56.
Commonwealth Bank (ASX)
The stock has reversed hard off new closing record last month after earnings. A sell-off in US banks overnight added to pressure on the sector. The ASX’s financials sector has fallen following a slew of lackluster earnings results from banks including ANZ, Westpac and Bendigo Bank as profits from deposits and loans get crunched.

Highlights – Emerging Markets Stocks
- Brazil’s Bovespa index dipped 0.3% (up 9.7%),
- Mexico’s Bolsa index gained 1.0% (up 7.4%).
- Turkey’s Borsa Istanbul National 100 index rallied 6.8% (down 1.7%).
Global Stock Markets Performance This Week

Technical Analysis
Technical Analysis of key markets via KnovaWave
S&P 500
Daily: The SPX has traded like clockwork hitting the 78.6% extension right on cue into election.
Background: The move fueled by the violent ABC for the 5 waves up for SPX continue right into bottom of the median line to give us an (a) or C of a 4. with impulse after completing 5. Reversed hard with energy fueled from the power impulse down from near +1/8 ATH. On the way up (just like down) It accelerated after it broke the Tenkan through the rejected Kijun and then the Kijun to close back over the median and 8/8. Bulls this was a (ii) of a 5. Bears this is a a-b of a C off a completive V of degree. We watch if this low was a (iii), (a) or C. Will determine if sharp ABC completed off all-time highs. We have to respect the number of alternatives of degree of 5. With such trends keep it simple support is Tenkan and Kijun and watch for ABC. No fear is the driving element.

The break up was from above the 200dma. The balance from sharp reversal after the initial 3 wave down from the SPX wave 5 extension as Covid19 fed impulse accelerated under the Tenkan. From there we had seen the ABC or 1-2-3 spinning around the 61.8% of the move. Support began at the October 2019 lows. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in
Weekly: The weekly confirms the daily sequence into the 78.6% extension.
Background: The reenergized SPX tripped in 3 to test recent break up at Tenkan from there we had had a powerful rally to ATH. Again notice what happened “Each new high has evolved after testing Tenkan key support which is the next line after Friday’s dump & minor bounce.” We watch for a spit of a spit Extensions are difficult to time, keep it simple.

Key for the impulse higher was the spit or retest of MM 8/8 and Tenkan San, which held with the previous highs and Tenkan. To repeat “We look for 3 waves down and reactions to keep it simple with the alternatives in the daily.” Keep an eye on the put/call ratio with recognition to the sheer size of contracts AND keep in mind the stimulus distortion. The spit per channel fractal and Adams rule launched back over the cloud where we were encased AND we back tested it. Watch if a spit or clear break support as Chikou rebalances
Dow Jones
NVIDIA (NVDA) and Sherwin-Williams (SHW) replaced Intel (INTC) and Dow Inc. (DOW) in the Dow Jones Industrial Average starting on Friday, November 8.

NASDAQ 100
The Nasdaq100 (NDX) declined 2.4% this week, closing at 19,281, only 56 points, or 0.3%, above the March 13th close. From March 13th lows to this week’s (Tuesday) high, the NDX rallied about 6%, a so far notably unimpressive rally from the previous steep one-month decline (from the 22,223 February 19th high). The Bloomberg MAG7 Index closed the week only slightly above March 11th intraday lows, with the S&P500 ending the week 1.4% off March 13th trading lows. At this critical market juncture, further weakness risks acute instability. – March 28
Background: Fuel was after it broke and held the weekly Tenkan to see a spit of a spit fail which is completive of 5 of some degree with Chikou rebalancing. From there we sold off right to Tenkan (as did SPX) and bounced hard Support Tenkan to Kijun. Watch Chikou for divergence for continuation or failure. Divergence with Russell also a clue.


Russell 2000
The small cap Russell RUT broke out of multi year flag and then spat the previous high. Unlike SPX and NDX we could not get to new ATH until near the end of this cycle after it got through Tenkan and Kijun on the bounce. This is the index showing more of the fast money crowd and is trading like it. Needs to get traction in here for bulls. Support +1/8 through 7/8 (cloud base)

US Stocks Watch
Investors (and algos) will focus on the conference calls and outlooks. Last quarter everyone expected the worse, we saw critical updates on production in coronavirus impacted regions and if there is extended halting of operations weighing on multi-nationals.
NVidia $NVDA
Nvidia Shares have been well poised for what happened over the Lunar New Year Weekend, they are up roughly 28-fold in the past five years. They had completed a potential double top spitting the 4.618 fib extension. That said timing the impulse is one of patience, discipline and usually hindsight.
The surprise here was it came over the Luna New Year break. The Chinese AI DeepSeek was listed for free and went top of the Apple & Google app stairs. Panic ensued and NVidia finished down 17% Monday, the biggest loss of market capitalization in history with a $560 billion evaporation. The Semiconductor index sank 9%. NVDA shares performed a dead cat bounce at best and closed 15.8% lower at the end of the week.
The impact was amplified given trading had boomed in products that allow investors to amp up bets on the world’s most popular equities, with investors pouring a record of more than $6.5 billion into such “single-stock ETFs”, vehicles that track just a single company but use derivatives to intensify bullish or bearish wagers. A major winner in this category was a fund from GraniteShares, which provides two times the daily returns of market powerhouse Nvidia Corp. The strategy, which trades under the ticker NVDL, saw assets explode to a peak of $6.7 billion in late November 2024, with returns in excess of 350% that year. Funds tracking MicroStrategy, Tesla Inc. and Coinbase Global Inc. have followed similar paths.
The move tracked by the KnovaWave extension model followed the announcement of NVDA 4/1 split come levels off the energy break NVidia hadn’t looked back with many gaps below until it hit the 2.618 target of the exhaustion phase. We saw another power move off the $200 retest (old $800) & earnings off $300 which retested. It is a clear leader of SOX SMH look for cues there and ABC failures for changes.

Apple $AAPL
Apple gently motored up to new ATH over the massive $160 then $170 thru to $180 gamma level to new ATH. These levels will be key energy levels. Support from previous highs, resistance now Fibs and Murrey Math levels. Remember the impact $AAPL has, at least short term on all the major indices.

Tesla $TSLA
In the second half, mom and pop then ditched financial companies en masse – only for the cohort to ride the “Trump trade” wave and become the S&P 500’s biggest gainers between July and November. And like many investors during the brief market crash in August, the retail crowd panic-sold some of their hottest assets, including Nvidia and Tesla – all at the lows. That proved painful. Shares of Elon Musk’s EV-maker, for example, have almost doubled since then.
Wrong-sided positioning like this has pushed the retail group’s gains this year to a mere 9.8%, according to Emma Wu, a quantitative and derivatives strategist at JPMorgan, and colleagues. That’s their second-weakest performance in any year when the index posted a positive return since 2015.

Exxon Mobil $XOM

Part B: Bond Markets
Highlights – Treasuries
- U.S. Treasuries finished the week with solid gains across the curve, turning the 5-yr note and shorter tenors positive for the week that featured an ongoing focus on reciprocal tariffs that will be coming into effect on April 2.
- The Personal Income/Outlays report for February prompted the Atlanta Fed to revise its GDPNow forecast for Q1 GDP to -2.8% from -1.8%, echoing the market’s ongoing growth concerns.
- Treasuries continued climbing into the afternoon, finishing on their highs. The rally sent the 5-yr yield back below its 200-day moving average (4.069%) to its lowest settlement in nearly three weeks while the 10-yr yield finished the day just above the 200-day moving average of its own (4.223%).
- This week’s outperformance in shorter tenors widened the 2s10s spread by five basis points to 35 bps.
- Crude oil narrowed this week’s gain to just over $1/bbl
- U.S. Dollar Index fell 0.3% to 104.02 Friday, shedding 0.1% for the week.
- Total money market fund assets increased $11.8 billion to $7.014 TN. Money funds were up $880 billion over 35 weeks (21.3% annualized) and $968 billion y-o-y (16%).
- Total Commercial Paper gained $7.2 billion to $1.392 TN – the high back to 2009. CP has increased $304 billion y-t-d and $42 billion, or 3.1%, y-o-y.
- 2-yr: -9 bps to 3.91% (-4 bps this week)
- 3-yr: -10 bps to 3.90% (-3 bps this week)
- 5-yr: -12 bps to 3.98% (-3 bps this week)
- 10-yr: -11 bps to 4.26% (+1 bp this week)
- 30-yr: -10 bps to 4.63% (+3 bps this week)
- NB: At Close 3/28/25


Highlights – Federal Reserve
- Federal Reserve Credit declined $8.7 billion last week to $6.704 TN. Fed Credit was down $2.197 TN from the June 22, 2022, peak.
- Over the past 289 weeks, Fed Credit expanded $2.977 TN, or 80%. Fed Credit inflated $3.893 TN, or 138%, over the past 646 weeks.
- Fed holdings for foreign owners of Treasury, Agency Debt declined $7.1 billion last week to $3.297 TN.
- “Custody holdings” were down $44 billion y-o-y, or 1.3%.
Highlights – Mortgage Market
- Freddie Mac 30-year fixed mortgage rates slipped two bps this week to 6.65% (down 14bps y-o-y).
- Fifteen-year rates rose six bps to 5.89% (down 22bps).
- Bankrate’s survey of jumbo mortgage borrowing costs had 30-year fixed rates down three bps to 6.79% (down 52bps).
The Fed is effectively throwing additional fuel on historic speculative manias. Central banks have been adding liquidity to avoid systematic failure.
Global Bonds This Week

Highlights – European Bonds W/E 3/28/25
- Italian 10-year yields dipped three bps to 3.85% (up 33bps y-t-d).
- Greek 10-year yields declined three bps to 3.55% (up 33bps).
- Spain’s 10-year yields fell five bps to 3.36% (down 30bps).
- German bund yields declined four bps to 2.73% (up 36bps).
- French yields dipped three bps to 3.43% (up 24bps).
- The French to German 10-year bond spread was little changed at 70 bps.
- U.K. 10-year gilt yields slipped two bps to 4.69% (up 13bps).
With this month’s (3/8/25) ECB 25 bps cut (to 2.65%), the ECB has now cut rates 185 bps since June. Meanwhile, bund yields have jumped 32 bps, French yields 57 bps, and Italian yields 13 bps. Sound familiar? Yields rose in the US once the Fed started cutting rates
European EM Bond Pain (3/8/25).
- Local currency yields surged 34 bps in Cyprus and Slovakia, 31 bps in Slovenia, 30 bps in Czech Republic, 24 bps in Latvia, and 22 bps in Romania.
- For the most part, dollar weakness underpinned EM currencies and equities.
Highlights – Asian Bonds W/E 3/28/25
- Japanese 10-year “JGB” yields added two bps to 1.54% (up 44bps y-t-d).
Part C: Commodities
Highlights This Week
- Bloomberg Commodities Index added 0.5% (up 7.1% y-t-d).
- Spot Gold jumped another 2.1% to $3,085 (up 17.6%).
- Silver surged 3.3% to $34.1255 (up 18.1%).
- WTI crude gained $1.08, or 1.6%, to $69.36 (down 3%).
- Gasoline rose 1.8% (up 10%),
- Natural Gas added 2.1% to $4.065 (up 13%).
- Copper increased 0.3% (up 27%).
- Wheat dropped 5.4% (down 4%),
- Corn fell 2.4% (down 1%).
- Bitcoin declined $220, or 0.3%, to $84,000 (down 10.4%).


Agriculture Futures
Cocoa and coffee brought inflation to the consumers drinking and and eating habits as companies passed on the price rises.
Cocoa
Cocoa futures were the best performing in 2024, surging by 176% for the year. Since then, we have had a vicious pullback. of around a 1/3 or $4,000. Cocoa a great example of how controlled or limited surplus can determine price. Africa produces 60% of global cocoa and nearly half of the world’s cocoa comes from just two West African countries, Côte d’Ivoire and Ghana.

The surge in 2024 cocoa prices was due to political and weather disruptions in West Africa. The crops were already struggling thanks to underinvestment in cocoa farms with growers struggling to replant diseased trees.
Coffee
Coffee futures followed cocoa higher and was up 73% for 2024, reaching a 47-year high as markets grappled with persistent supply concerns in key growing regions. While it has corrected off those highs in 2025, not to the extent of cocoa. The premium bean, arabica futures price doubling in 2024. Extreme weather in Brazil and Vietnam affected supply whilst demand was pressured by booming demand in markets like China.

Orange Juice OJ


BDI Freight Index
- The Baltic Exchange’s dry bulk sea freight index, which measures shipping rates for vessels transporting dry bulk commodities, decreased for a fourth successive session on Friday, falling about 1.2% to a fresh low since March 12 at 1,602 points. The benchmark index dropped about 2.5% for the week, marking its the second straight decline.
- The capesize index, which transports 150,000-ton cargoes like iron ore and coal, also eased for a fourth session, slumping by 2.2% to 2,472 points;
- Among smaller vessels, the supramax index continued to decline, falling 12 points to 995 points.
- The panamax index, which usually tracks vessels carrying 60,000-70,000 tons of coal or grain, rose about 0.9% to its highest to 1,497 points. The benchmark index dropped about 2.5% for the week, marking its the second straight decline.
- Source: Baltic Exchange 3/28/25

Metals

Copper
Copper is the bellwether industrial metal and moves on supply risks and hopes for global recovery in demand. Disruptions at major mines and Chinese plants which produce more than half of the world’s refined copper impact price.
February 26 – Bloomberg (Alfred Cang, Archie Hunter and Mark Burton): “The world’s top commodity traders are rushing to ship copper to the US from as far afield as Asia as Donald Trump’s threat of import tariffs on the metal creates a huge opportunity for profit. The gap between copper prices in the US and the rest of the world widened sharply after the president… ordered the Commerce Department to examine potential levies on the metal. On Wednesday, prices on New York’s Comex surged as much as 4.9% to trade more than $1,000 a ton above the London Metal Exchange benchmark, which rose 1.2% to about $9,500 a ton.”

Gold
Gold hit record highs as inflation, safe haven, and Russia and China buying to avoid sanctions pushed it higher. The price rose against multiple currencies, including the U.S. dollar. GS ‘reiterating a target of $3,000 an ounce by December 2025. The structural driver of the forecast is higher demand from central banks, while a cyclical lift would come from flows to exchange-traded funds as the Federal Reserve cuts, they said.”

Energy
Oil prices in 2024 traded in a relatively stable range given the world conflicts in energy supply related regions. Intraday Brent prices stayed within a $24/b range, between $68/b and $93/b the narrowest trading range since 2019. Adjusting for inflation, 2024 was the narrowest since 2003. A moribund world economy working against Middle East and Russian tensions. The selling has continued in 2025.
U.S. energy companies played the smart card pushing production higher familiar with the cycle of oil prices. Natural gas demand grew as did record U.S. production, we saw increased electricity consumption, driven by the AI mania.

US Crude Oil (WTI)

Daily: WTI Crude Oil gave back all its rally that evolved from retesting the pennant breakout last December after completing the correction in 3 waves. from there it has fallen to new lows and the upside burst has effectively rinsed short and trapped new speculative buyers with the market now rinsing them as it falls to test support. The market has behaved as expected as we have said being in a completive mode for bulls with the upside impulse, it was a question of degree on the topside, as it will be on the downside. Use the Murrey math 240/60 grid. Was oil completing a C or IV? Support is previous lows and the bull flag. The bear case is the high was a complete 5.

Weekly: WTI crude oil futures held the support line from July 2021, having plunged around 50% off 2022 highs. The market is now back testing it. The break to the topside of its sphere of influence to close out the quarter over Kijun and Tenkan failed, and which are now resistance. Risk support is the grid. Resistance weekly channel, Murrey Math levels and previous breaks (off monthly). Bear case is Wave 5 complete.
What we broke……. Crude Oil in the past quarter built a huge bull flag. We watch if the recent break was false, or we fail. Very clear pattern.
The key is crowd behavior to help tell the story which in energy is often around geopolitics. A great example of why we watch ABC corrections and from here we get the energy from the break being balanced. This move that was powered by 50 dma Tenkan spit of a spit – hence the fractal energies reverberations.
US Natural Gas (Henry Hub)
Daily: US Natural Gas futures are a great example of rebalancing mania. The market is still correcting the manic 5 post the Ukraine invasion and beyond. Since the breakdown of the correction channel with failed breakups we have continued to multi year lows in a pennant formation after holding the daily 1/8. We now look at our Adam’s theory fractal rules with fractal spits powering these moves lower. Two clear alternatives, we are correcting the highs 5 or that was a 3 and we go higher. Resistance is heavy: 2/8 and cloud above. Kijun, 50 dma and cloud. Support is previous lows. Important to watch how this energy was built for shape correlation.


Like the larger wave on the way up it accelerated through previous highs (flat topped triangle energy) and over the resistance at 8/8 and new highs. We successfully tested that break in a pennant ABC. Previous highs (flat topped triangle energy) and 8/8 and new highs underscore the structure that fed the move and is key longer term in the collapse lower.
Weekly: Natural gas has been busy correcting the past months when it blew through all levels of support after breaking the weekly 50wma and the Kijun gave a kiss of death. From there we formed an island reversal which has resolved to the topside, trapping shorts and bears. Recall it broke down out of the corrective channel (Wave 4 or IV) to new multi-year lows. The instability and volatility stem from the sharp reversals that have failed indicative of speculative fervor like the previous impulsive spikes. Support is the flat Kijun and Tenkans. Resistance the near highs and previous uptrend. Bulls need all the damage down to be rebuilt. Kijun became the accelerator given energy lower and now higher came from a clean break of the Kijun
Part D: Forex Markets
John Maynard Keynes, 1920: “There is no subtler, no surer means of overturning the existing basis of society than to debauch the currency. The process engages all the hidden forces of economic law on the side of destruction and does it in a manner which not one man in a million is able to diagnose.”
- For the week ended Mar 21, 2025, the U.S. Dollar Index little changed at 104.044 (down 4.1% y-t-d).
- On the upside, the Swedish krona increased 1.3%, the Norwegian krone 0.7%, the Canadian dollar 0.3%, the Swiss franc 0.2%, the Australian dollar 0.2%, the British pound 0.2%, and the euro 0.1%.
- On the downside, the South African rand declined 1.1%, the Mexican peso 0.7%, the Brazilian real 0.6%, the Singapore dollar 0.4%, the Japanese yen 0.4%, the New Zealand dollar 0.3%, and the South Korean won 0.3%. The Chinese (onshore) renminbi declined 0.14% versus the dollar (up 0.51% y-t-d).
- March 11 – Bloomberg (David Finnerty): “Macro hedge funds are increasingly seeking currency option trades that exclude the dollar as they navigate the market turbulence stemming from worries about the US economy. Trades involving the euro and haven yen were in demand Monday. The two currencies were easily the most traded on The Depository and Trust Clearing Corp., involved in over half of all trades, as US tech stocks tumbled by the most since 2022. Option data shows long euro positions are the highest since 2020…”

Key Currencies Versus the US Dollar
Australian Dollar – AUDUSD
The Australian dollar traded towards a 5 year low in the New Year in a tumultuous week, it has continued lower after breaking a three-month low of US65.1¢ on news of a Donald Trump’s US election victory before rebounding to US66.51¢ on hopes of fresh China stimulus. The Aussie dollar had been correcting since completing a 5 at the psych 80 level to fall under the weekly cloud in emotive fashion. The Australian dollar fell to test of the August lows of 0.7106 with Omicron fears. When that double bottom support broke it retested the Murrey Math Levels. Resistance the Cloud, Tenkan and Kijun like many commodities. From there it has been a combination of a stronger US dollar, a collapsing Chinese economy & concerns over the US economy.

Japanese Yen – USDJPY
USDJPY is consolidating the break after weakness with Treasury yields to rush to +2/8 and channel convergence. It came a long way from that 108.00 massive support for dollar-yen back through the top of the flat-topped triangle at 151/152 whcih it spins around in 2025. Any change will come from the weekly Kijun. Use your USDJPY Murrey 7/8 8/8 grid for now. EURJPY AUDJPY will determine risk on/off.
Yen weakness provided key support to dollar melt-up dynamics with BOJ slow-motion “normalization” in a world of fast-moving dynamics. The dollar yen traded 160.17 this cycle, the first time above 160 since April 1990. Governor Kazuo Ueda on that move basically ceded the yen fragility issue to the Ministry of Finance (MOF), affirming it wasn’t in the BOJ’s purview. He conveyed little concern for yen weakness, while downplaying its inflationary impact. The market accordingly took the yen out to the woodshed.

Chinese Yuan – USDCNH
China has been battling a weak economy for years and has been flooding its economy with liquidity to no avail, the result, falling yields and a record low for the Yuan against the US dollar. So far it has been defended at a triple top.
“Doubts over US exceptionalism are giving China a much needed break from strongly defending its currency, as the yuan’s strength allows it to dial back support via its daily reference rate. The gap between the People’s Bank of China’s daily reference rate versus narrowed to 675 pips on Monday, the least since early December. While the so-called fixing remains near the strongest level since November, its smaller spread with estimates signals weakening official support for the currency.” March 10 – Bloomberg (Iris Ouyang)
To begin 2025 the onshore yuan weakened past the level that China had been defending throughout December. The yuan breached the psychological milestone of 7.3 per dollar for the first time since late 2023, amid concerns over China’s economic struggles and a widening bond yield discount to the US. The move came even as the central bank maintained its support for the currency with its daily reference rate that Friday.

February 26 – Reuters: “Chinese authorities are rolling out fresh measures to limit capital flight, including increased scrutiny of overseas investments, as the yuan currency comes under mounting pressure. President Donald Trump’s tariffs threats are heightening Sino-U.S. tensions and discouraging inbound foreign investment… China has increased scrutiny of overseas investments by domestic companies and their use of proceeds from Hong Kong share sales… Meanwhile, China’s commercial banks sold the most foreign exchange to their clients since July last month… The conversion ratio – a gauge that measures households and corporates’ willingness to sell dollars for yuan – fell to the lowest level in seven months. Xinquan Chen, an economist at Goldman Sachs, said the current account showed sizeable currency outflows in January.”
January 12 – Bloomberg: “China has ramped up its support for the yuan with tweaks to its capital controls and a vow to crack down on market disruption, after the currency dropped close to a record low against the dollar in offshore trading. The People’s Bank of China and other regulators pledged to strengthen their management of the foreign-exchange market, deal with any behavior that may disrupt the market and prevent the risk of a large move in the yuan… The PBOC also adjusted its rules for cross-border flows…, allowing firms and financial institutions to borrow more from overseas, which may help increase capital inflows and support the yuan.”
South Korean Won – USDKWN
The won has slightly appreciated so far this year after tumbling since October 2024 by a cumulative 12% depreciation to the dollar both on domestic political developments and external concerns related to a less dovish Federal Reserve and trade policy risks. It had dropped to its weakest level in 15 years.

Indonesia Rupiah – USDIDR
“Indonesia’s rupiah fell to its weakest level against the US dollar since the Asian financial crisis of 1998 over mounting fears about the policies of President Prabowo Subianto and their impact on the fiscal position of south-east Asia’s largest economy… Bank Indonesia, the country’s central bank, told the Financial Times that it had intervened in bond and currency markets on Tuesday ‘to ensure the stability of the rupiah exchange rate and maintain the balance of foreign exchange demand and supply, thereby maintaining market confidence’.” March 25 – Financial Times (Joseph Cotterill and A. Anantha Lakshmi)
The Americas
The Canadian dollar and Mexican dollar have weakened since the mention of Trump tariffs on the two countries.
Canadian Dollar – USDCAD
Busy week for Canada the ides of March:
- BoC cut rates
- BoC is unlikely to cut again in April
- Mark Carney was sworn in as Canada’s prime minister.
- Canada election call, fast policy action likely
- Canada delivers carbon tax relief on energy bills but it may not be a boon to most households
- Canadian CPI to begin a trio of highly distorted reports
The Loonie has been in a steady downtrend since 2021, on yield pressures, weakening economic metrics and political uncertainty. The USDCAD hit a 3 year high in June and corrected that in 3 waves led by the AUD and NZD with oil price impacting direction from there the selling of the Loonie resumed. From there it broke the 2020 highs and tested 1.48 before reverting back on tariff gamesmanships in 2025.

Mexico Peso – USDMXN
Mexico’s currency is part of a carry trade that involves investors borrowing in currencies that have low interest rates, such as the Japanese yen or Swiss franc, and buying higher yielding ones such as the Mexican peso or, recently, the U.S. dollar. It has boomed in popularity as interest rates have diverged around the world and market volatility has stayed low. after the Mexican election this year the peso had a dramatic fall against the yen – it dropped 4.4% on that Monday in its biggest daily decline since the COVID-19 crisis.
The peso had climbed to the strongest in almost nine years driven by relatively high local interest rates and low currency volatility until, that sell off.

Brazilian Real – USDBRL
December 19 – Bloomberg (Martha Beck, Vinícius Andrade, Maria Eloisa Capurro and Leda Alvim): “As the currency craters in Brazil, thrusting the country’s markets into the international spotlight for the first time in years, a grim reality is setting in for top economic aides to President Luiz Inacio Lula da Silva. They are, they fear, powerless to do much to stop the panic… The central bank has ramped up intervention in currency markets to try to stem the losses amid what Governor Roberto Campos Neto called an ‘atypical’ outflow. It has stepped in either directly or through swaps almost every day for the past week, spending close to $14 billion to give some support to the real… On Thursday alone it sold $8 billion in back-to-back spot auctions — that’s the biggest daily sale of dollars since at least 1999, when Brazil adopted a floating exchange rate regime…”

Europe
Euro – EURUSD
The EURUSD is up 466 pips or -4.49% vs the USD in the trading week. That is the largest % move going back to March 2009
Euro continued to bump up against that downtrend line from 2020 and spinning around the 50% of that year’s panic sell. The euro trades in what seems like eternal flags in the channel. We watch if Kijun (pink) testing Tenkan (orange) creates any impulse as EURUSD consolidates under the cloud and break up level from 2022. Watch 3 waves to see development for continuation and for impulse off Chikou rebalance. Governed by EURGBP and Bund volatility.

British Pound – GBPUSD
The GBPUSD is up 342 pips or -2.71% vs the USD. The % change is the largest move since November 2022.
British pound rose in a classic rising wedge since its late 2022 spike classic retest until its daily break late 2024 which brought a weekly kiss of death. From there a weekly cloud break with magnet pulls of cloud twist after ABC correction – will need Tenkan to break through Kijun for more strength. The upcoming months will be heavy on UK data and EU, Ukraine speculation which could mean an eventful time for the British pound.

Turkey Lire USDTRY
Political instability erupted in Turkey at the hand of its autocratic and antidemocratic president on March 19. The Turkish lira immediately collapsed 12%, though record ($9bn) intervention reduced the day’s loss to 3.2%. Turkey’s central bank boosted short-term rates two percentage points to 46%. Yet the lira’s 3.1% loss was the largest weekly decline in almost two years. Turkish stocks were slammed 16.6%, with “banking stocks experiencing their worst weekly drop since at least 2001” (Bloomberg). Turkey’s local currency bond yield spiked 293 bps to 29.16%. “Turkish Lira Rout Sours Lucrative Carry Trade.” “Turkey’s Erdogan Warns Opposition Over Calls for Mass Protests.”
March 28 – Bloomberg (Ugur Yilmaz): “Ekrem Imamoglu, the Turkish opposition figure whose detention this month triggered mass protests and a market selloff, criticized Western leaders for their muted response to his arrest. In a piece published in The New York Times…, President Recep Tayyip Erdogan’s main political rival accused the US and Europe of prioritizing geopolitical interests over democratic values. ‘Their silence is deafening,’ Imamoglu wrote of world governments. ‘Washington merely expressed ‘concerns regarding recent arrests and protests’ in Turkey. With few exceptions, European leaders have failed to offer a strong response.’”

Bitcoin
Bitcoin is the world’s biggest digital asset; it had already staged a remarkable comeback in 2023. Then in January the approval of US Bitcoin exchange-traded funds was a further catalyst for gains. Donald Trump’s victory in November turbocharged BTC, sparking a record-breaking rally over the $100,000 level. Along the way, traders poured more than $100 billion into the ETFs, paving the way for similar crypto-related investment vehicles. At the opposite extreme, activity in memecoins, which often trade for a fraction of a cent, exploded.
Trump galvanized the digital-asset community with promises to reverse a US crypto crackdown under President Joe Biden and make America the center of the industry. In the weeks after the election, he announced the newly created post of czar for AI and crypto, and named industry proponent Paul Atkins to replace crypto nemesis Gary Gensler at the Securities and Exchange Commission.
This year also set a record for US ETF fund flows, with Trump’s presidential victory giving already emboldened investors even more incentive to double down. Funds that track the S&P 500 took the most flows, one of this year’s most notable new entrants was BlackRock’s Bitcoin ETF drawing the third-most inflows this year.
Bitcoin traded this week to a new ATH $99,978, ending the week with 2024 gains of 132%. Since the election, Bitcoin has surged 43%, with Ethereum up 39%, Ripple 215%, Cardano 240%, Solana 54%, and Dogecoin 144%. Bloomberg’s monitor page has expanded to include pricing for 58 crypto currencies.
Bitcoin soared 10% to a record $75,959 (ended the week up 80% y-t-d) after the Trump election 2.0. Bitcoin is performing technically to perfection. Impulse begets impulse. To understand panic, understand greed. Bitcoin exploded higher following its correction impulsively upon completing 5 waves up at +2/8. Each Tenkan and Kijun tap saw an explosive kiss of death until we completed 3 waves to around 28,000. From there we have seen extreme volatility to a new record high and retest.

We have seen what you would expect from a 5-wave impulse peak and ABC correction, a violent correction and completion. Use Murrey Math levels for corrections and targets as algorithms control the herd here, support is the cloud and sharp ABC, 1-2 moves. From there prices agitated towards those ATHs as news of a Bitcoin ETF fueled the rally, sound familiar? But this time it wasn’t signaling we are in a 3 high probability but a 5.


On the Risk Radar

Geopolitical Tinderbox Radar
The Week Ahead – Have a Trading Plan
Watch Earnings, Central Bankers and Geopolitics speeches, reports and rate moves.
Next Week’s Risk Dashboard
Global Week Ahead Highlights
- A black mark on the annals of global economic history will arrive this week
- ‘Liberation Day’ will be a libertarian’s worst nightmare
- A protectionist US wall revisits 1930, and the 1500s through 1700s
- Which countries are most vulnerable to US tariffs
- All the ways America heavily protects its auto sector
- Expect retaliation…
- …including direct pre-commitments to do so from Canada
- Four narratives on the way forward
- US nonfarm payrolls: cautious optimism for now
- Fed’s Powell to update outlook post-tariffs and nonfarm…
- …and most of the Fed’s Board will weigh in post-tariffs
- Canadian jobs: tariffs and snow
- BanRep expected to hold again
- RBA to hold
- Eurozone CPI is likely to be soft for now
US Economic Highlights
- Monday: March Chicago PMI (prior 45.5) at 9:45 ET
- Tuesday: February Construction Spending (prior -0.2%) and March ISM Manufacturing Index (prior 50.3%) at 10:00 ET
- Wednesday: Weekly MBA Mortgage Index (prior -2.0%) at 7:00 ET; March ADP Employment Change (prior 77,000) at 8:15 ET; February Factory Orders (prior 1.7%) at 10:00 ET; and weekly crude oil inventories (prior -3.34 mln) at 10:30 ET
- Thursday: Weekly Initial Claims (prior 224,000), Continuing Claims (prior 1.856 mln), and February Trade Balance (prior -$131.4 bln) at 8:30 ET; March ISM Services (prior 53.5%) at 10:00 ET; and weekly natural gas inventories (prior +37 bcf) at 10:30 ET
- Friday: March Nonfarm Payrolls (prior 151,000), Nonfarm Private Payrolls (prior 140,000), Average Hourly Earnings (prior 0.3%), Unemployment Rate (prior 4.1%), and Average Workweek (prior 34.1) at 8:30 ET
Bond Market Highlights
- Monday:
- Tuesday:
- Wednesday:
- Thursday:
Central Bank Highlights
This will be a lighter week for global central banks, key will be the reaction of much of the Fed’s Board of Governors that weighs in after Trump’s tariff announcements—including the Chair.
- Tue: RBA, BanRep Monetary Policy
- Wed: 4:30 p.m. Federal Reserve Board Governor Adriana Kugler will speak virtually on “Inflation Expectations and Monetary Policymaking.”
- Thu: Governor Jefferson (Thursday), Governor Cook .2:30 p.m. Federal Reserve Board Governor Lisa Cook will speak on the economic outlook before the University of Pittsburgh 2025 McKay Lecture event.
- Fri: Chair Powell’s speech on the economic outlook at the SABEW conference in Arlington, Virginia Friday (11:25amET). 12:00 p.m. Federal Reserve Board Governor Michael Barr will speak on “Artificial Intelligence and Banking” before the Federal Reserve Bank of San Francisco. 12:45 p.m. Federal Reserve Board Governor Christopher Waller will participate in a payment’s discussion before the 2025 New York Fed Innovation Conference.
RBA—’Twas the Night Before Tariffs
The Reserve Bank of Australia is widely expected to be on hold on late Monday night (ET) or Tuesday Down Under and one day before Tariff Man leaps out of his phone booth. The cash rate target is likely to stay at 4.1%.
One reason for holding is that they just cut by 25bps with some trepidation at the February 17th meeting. At that decision, the RBA said it expected core inflation to remain in upper half of its 2–3% inflation target range from this June through the next 2+ years. They also cautioned—as have other central banks like the Fed—that easing too quickly could stall progress on disinflation. That was a reason for why Governor Bullock said “I want to be very clear that today’s decision does not imply that further rate cuts along the lines suggested by the markets are coming.” That’s not exactly the kind of language that a central banker on a straight line easing path would have chosen—with or without being on the eve of uncertain tariff effects.
BanRep—Probably a Hold
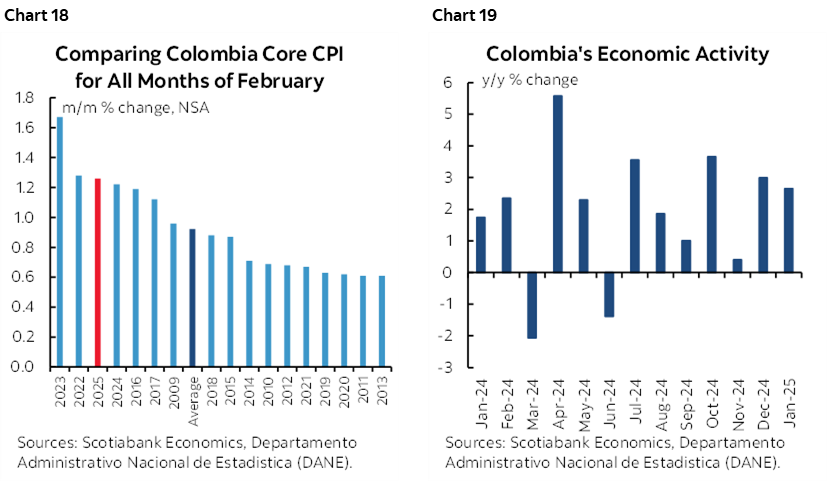
Colombia’s central bank is expected to stay on hold at an overnight lending rate of 9.5% on Tuesday afternoon. This is the view of the median consensus forecast and our economists in Colombia. A significant minority of forecasters leave open the possibility of a rate cut.
One thing that would counsel keeping their powder dry may be to see what actually transpires when the US administration makes its tariff announcements and others react.
And yet core inflation is already recently running a little too warm for comfort (chart 18). Recent growth has also been decent (chart 19).
Key Fed-Speak
This will also be a significant week for Fed-speak that picks up on the recently more hawkish comments from several FOMC officials. Much of the whole Board of Governors will be trudged out to present a united voice from the top of the house in the wake of Trump’s tariff announcements.
Key will be Chair Powell’s speech on the economic outlook in Virginia on Friday (11:25amET). Also on tap will be Governors Waller and Barr shortly after Powell speaks, Governor Kugler (Wednesday), Governor Jefferson (Thursday), Governor Cook (Thursday).
Recall that Chair Powell already effectively ruled out a move in May at the last decision (recap here). Since then, several FOMC officials have sounded incrementally more cautious and patient.
Boston’s Collins supports holding for longer. Richmond’s Barkin signalled discomfort toward assuming that tariffs would merely offer one-off transitory effects on inflation. St. Louis President Musalem cautioned that indirect tariff effects may raise persistent inflationary pressure and said there is no urgency to cut. Atlanta’s Bostic indicated he was previously at two rate cuts this year and now expects only one. Minneapolis President said there is more work to be done in lowering inflation. Chicago’s Goolsbee cautioned that it’s unrealistic to expect to know the rate path from this point forward. San Fran’s Daly said she still thinks two cuts may be reasonable this year but is “100%” focused on inflation.
Commentary via Scotiabank
US Earnings Highlights
- Monday: PVH (PVH) Progress Software (PRGS) Loar Holdings (LOAR) TechTarget (TTGT)
- Tuesday: Sportsman’s Warehouse (SPWH) nCino (NCNO).
- Wednesday: RH (RH) UniFirst (UNF) Blackberry (BB) Penguin Solutions (PENG)
- Thursday: Conagra Brands (CAG) Lamb Weston (LW) Acuity Inc. (AYI), MSC Industrial Direct (MSM), Lindsay (LNN).
- Friday:
US IPO Week Ahead
IMedia player Newsmax (NMAX), luxury watch seller Top Win International (TOPW), and Self Storage REIT (SMA) are expected to start trading during the week. The quiet periods expire on Kestra Medical (KMTS) and Skycorp Solar GRoup (PN).
Source: Renaissance Capital
Focus on yourself and what YOU CAN INFLUENCE, set your trading plan and goals in be set for 2025.
Trade Smart!
Subscribe and Follow
Find us at www.traderscommunity.com
Real Time Economic Calendar provided by Investing.com.
Follow our contributors on Twitter @traderscom @thepitboss16 @knovawave @ClemsnideClem
Note these charts, opinions news and estimates and times are subject to change and for indication only. Trade and invest at your own risk.
Trade Smart!
Focus on yourself and what YOU CAN INFLUENCE, set your trading plan and goals in be set for 2025.
-comment section below data-
Subscribe and Follow
Find us at www.traderscommunity.com
Follow our contributors on Twitter @traderscom @thepitboss16 @knovawave @ClemsnideClem
Note these charts, opinions news and estimates and times are subject to change and for indication only. Trade and invest at your own risk.
Trade Smart!