April 21, 2024
FEAR NOT Brave Investors
Where have we been and where are we going? Join our weekly market thread on Traders Community…

Fear and Greed Feed Volatility
The Week That Was – What Lies Ahead?
Contents
Click on the links below to navigate to the relevant section.
- Part A: Stock markets
- Part B: Bonds
- Fed and Banks
- Part C: Commodities
- Energy – Oil and Gas
- Gold and Silver
- Part D: Foreign Exchange
- Geopolitics and Economics
- Economy Week ahead
Editorial
Another wildly volatilized week in the gambler’s Snakepit across all financial markets with headaches in tech land. It was five sessions of unrelenting volatility. With Friday’s action, the S&P 500 and Nasdaq Composite saw their sixth consecutive loss. On Friday dip buyers were absent. The Russell 2000 fell 2.8%, the S&P 500 declined 3.1%, equal-weighted S&P 500 saw a 1.3% decline, Nasdaq Composite dumped 5.5% and the Dow Jones Industrial Average settled unchanged on the week.
This week with the selling of more speculative, rapid-growth, momentum-type asset classes ratcheted up a notch. We have seen Nvidia continue to sell off through the week with other big Tech stocks. It seems the market realized there was geopolitical risk, rates were high, and we were travelling at record highs in many markets.
The 2-yr note yield settled nine basis points higher at 4.97% and the 10-yr note yield settled 12 basis points higher at 4.62%.
PCE Next Up to Test Rates and Asset Values
The downside bias in stocks was also related to rising interest rates with Fed officials suggesting they are in no hurry to cut rates because recent inflation reports have not given them enough confidence that inflation is on a sustainable path to the 2% target. The Fed’s preferred inflation reading will be updated for the month of March on Friday. The Core PCE report, price deflator for total consumption expenditures differs in its methodology compared to CPI for numerous reasons.
Federal Reserve Chair Powell noted that Fed economists expect 2.8% y/y unchanged from February. If so, and barring material revisions, that would imply that March would be 0.35% m/m SA higher than February and hence on the bubble between 0.3–0.4%. Most estimates in consensus are at 0.3% m/m SA.
That would be higher than some economists that have suggested core PCE could be lower than the already known 0.4% m/m rise in core CPI for the same month of March. The result could raise the three-month moving average to 0.35% m/m SA, or 4.3% m/m at a seasonally adjusted and annualized rate and be a marked departure from the glimmer of a soft patch that was appearing over 2023Q4. A complication could arise if revisions are implied in the Q1 core PCE estimate that lands the day before.

Recall the negative bias in stocks followed a hotter than expected March Consumer Price Index (CPI). Total CPI increased 0.4% month-over-month versus an expected 0.3% increase and core-CPI, which excludes food and energy, increased 0.4% month-over-month versus an expected 0.3% increase. The Producer Price Index (PPI) was cooler-than-expected on a month-over-month basis (actual 0.2%; expected 0.3%), but total PPI still accelerated to 2.1% in March from 1.6% in February.

This week’s Carnage
Eight of the 11 S&P 500 sectors declined. The information technology (-7.3%), consumer discretionary (-4.5%), rate-sensitive real estate sector (-3.6%) and communication services (-3.2%) the largest declines, clipped by weakness in their mega cap constituents. The consumer staples (+1.4%), utilities (+1.9%), and financial (+0.8%) sectors were the only sectors that gained.
Friday trading action was the type that tends to foreshadow a panic.
- Nvidia posted a one-session loss of 10%.
- Netflix sank 9.1%,
- Advanced Micro 5.4%,
- Micron 4.6%,
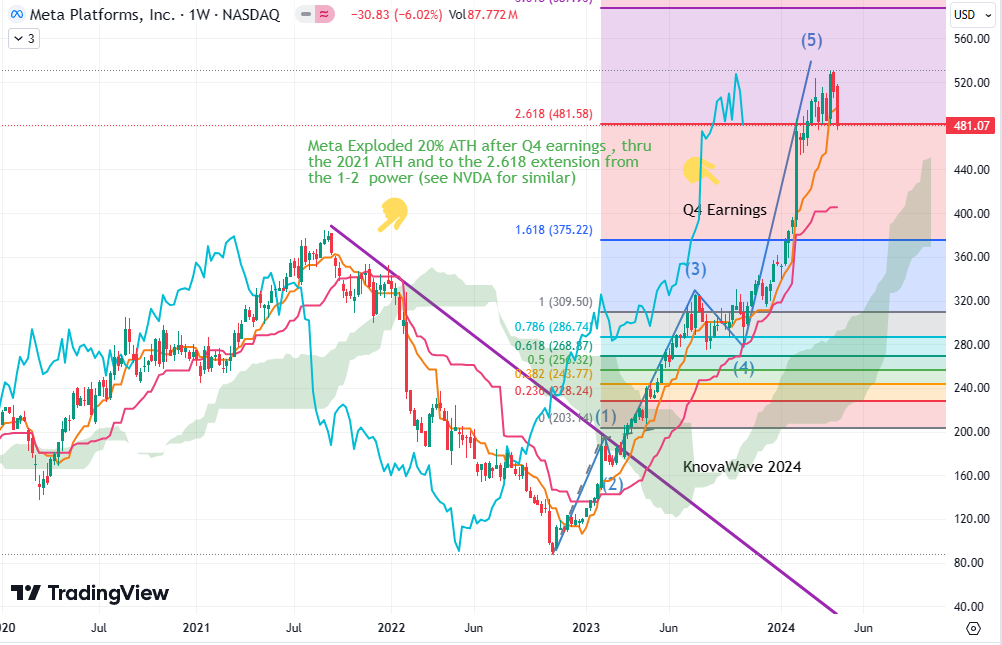
- Meta Platforms 4.1%.
- The Semiconductors’ 4.1% Friday slump pushed the week’s loss to 9.2% – the largest weekly decline since July 2022.
- The Nasdaq100’s (NDX) 5.4% weekly drop was the largest since November 2022.
For the week:
- Vanguard Mega Cap Growth ETF (MGK) dropped 5.8%
- PHLX Semiconductor Index (SOX) sank 9.2%.
- ASML (ASML) declining 10.6% TSMC (TSM) declining 10.4%, respectively, this week after reporting quarterly results. ASML reported weaker-than-expected Q1 bookings and TSMC reported better than expected earnings but warned that the chip industry is enduring a more gradual recovery than expected.
- NVIDIA (NVDA) dropping 13.6% on no specific news. Shares of NVDA are still 53.9% higher since the start of 2024.
- Biotechs dropped 3.9% (down 10.2%).
- S&P 500: -3.1% for the week / +4.1% YTD
- S&P Midcap 400: -2.2% for the week / +2.0% YTD
- Nasdaq Composite: -5.2% for the week / +1.8% YTD
- Dow Jones Industrial Average: UNCH for the week / +0.8% YTD
- Russell 2000: -2.8% for the week / -3.9% YTD
Fragile EM bond markets remained under pressure this week.
In dollar-denominated EM bonds,
- Indonesia yields rose 13 bps to 5.28% (one-month rise 39bps),
- Philippines eight bps to 5.39% (35bps),
- Panama 23 bps to 5.41% (50bps),
- Colombia six bps to 7.69% (52bps),
- Brazil three bps to 6.73% (25bps).
Over the past month, local currency bond yields were up:
- 116 bps in Turkey,
- 66 bps in Colombia,
- 61 bps in Brazil,
- 58 bps in Mexico,
- 52 bps in Hungary,
- 50 bps in Peru,
- 50 bps in the Philippines.
What now for Israel and Iran?
Soaring tensions between Iran & Israel
- Israeli attack on an Iranian compound in Syria,
- Iran launched an unprecedented assault against Israel.
- Israel hit Iran with a missile in the early hours of Friday, in what appears to have been a retaliatory strike after weeks of escalating tensions between the two countries.

- There is also the possibility of a knock-on effect of Russian aggressive opportunism. We saw that with the attack on Ukraine natural gas storage just days before the Iranian invasion.
- Israel thwarted the attack with its multilayered air-defense network that includes systems capable of intercepting a variety of threats including long-range missiles, cruise missiles, drones and short-range rockets. Iran had vowed revenge since the April 1 airstrike in Syria, which Tehran accused Israel of being responsible for. Israel has not commented on it.
- Should Iran escalate and overwhelm Israeli missile defenses and see larges deaths and casualties in cities such as Tel Aviv, which hosts the Kirya, the Israeli military headquarters Netanyahu will be hard pressed to not take much more drastic action in response. It gives Israel a reason to attack Iran’s nuclear program.
- The region is a powder keg and there exists possibility of a full-scale war between Iran and Israel, and probably drag the United States in. US President Joe Biden reportedly warned Netanyahu that the US will not participate in any attack by Israel on Iran. In a Presidential election year Biden will most likely take the route that gets him the most votes.
Geopolitical Tinderbox

What has changed in two years?
We are about two-and-a-half years since bond markets began tightening in anticipation of Federal Reserve rate hikes that began in March 2022 and the economy remains highly resilient. The rise in the two-year and 10-year Treasury yields was based by late 2022 and well ahead of the fed funds target rate that hit last summer. Lags are long and variable, and the US economy is not out of the woods yet particularly given the surge in mortgage rates, the economy has had significant time to adjust to higher market yields and the majority of mortgage holders are in under 3.9%, which presents another issue for Real Estate inventory. Lending conditions have been tightening, but at an ebbing incremental pace Credit spreads remain tight and the S&P500 has only moved slightly off the all-time peak in late March.
The US consumer has delivered but delinquency rates are rising for several credit categories. Looking deeper much of this has been more about normalization toward pre-pandemic patterns compared to when extreme policy supports, and very low rates meant little to no default activity in the pandemic. Scotiabank points out that “We are at a twenty-three year low in the debt-to-disposable income ratio and still toward record low debt service payments to incomes remain supportive of spending and lessen rate sensitivity compared to, say, strained measures into the GFC. The personal saving rate has normalized, but the stock of outstanding cash and checkable deposits on US household balance sheets remains very elevated “

Looking back two years ago from our January 30, 2022, Traders Market Weekly we can see how little has changed and where herd opinion was so wrong.
On Wednesday markets took volatility to another level with the FOMC and Tesla earnings. By his own admission Chair Powell’s toolkit is limited. The Fed is behind the game on inflation, balancing that with supply chain issues starting to ease in the second half of the year and hurting strong economic growth to slow inflation are all real issues.
Tesla made this clear, Tesla’s December quarter revenue of $US17.7 billion beat consensus estimates of $17.1 billion, with earnings per share of $US2.54 about 7.6% above analyst predictions. TSLA gross profit margin on its automotive operations of 30.6% are easily the best in the global car industry and well ahead of the 24.1 per cent margin it started 2021 with. Tesla increased car sales by a head turning 90% and delivered a net profit of $US5.5 billion. However, the stock sold off over 10% the next day. Why? Supply chain concerns. Elon Musk said those supply chain pressures will last well into 2022 and Tesla’s factories will continue to run below capacity, as they’ve done for several quarters. So, in a nutshell this is where the short-term concerns of Elon Musk and Jerome Powell cross over.
The question investors have to ask is what he can do to inflation given most of it is supply driven, which he does have the tools for and how quickly can consumers and businesses alike recalibrate from Supply chain issues? Not to through in the energy crisis engulfing the world and the continuing war drums from Biden with Russia and The Ukraine. Significantly Ukraine’s President Zelensky said that media reports are making the current tension with Russia appear worse than it really is. Wag the dog from Biden crossed your mind? Did we mention Omicron.
From our January 30, 2022, Traders Market Weekly
Well, the Fed is still behind the game on inflation and the tide has turned on Tesla and even more so on electric vehicles. This and inflation are not unrelated. Russia did invade Ukraine and that war is ongoing with the US writing billions in aid checks. This is also inflationary.
Where is the Fear?
The Cboe Volatility Index (VIX) traded at its highest level since November holding above its 200-day moving average., before dipping Friday as Mid East tensions appeared to calm.

“We have a market trying to interpret the Fed who is trying to find out how they can interpret their long-only portfolio at a risk parity where rates cannot rise.”– MoneyNeverSleeps
Our weekly reminder for risk, timely given the V shape to ATH in just a week. The downside is clear with the absence of moral hazard from repeated Federal Reserve market bailouts in an environment of some would say obscene liquidity pumps. Pure greed is the other part, not wanting to miss out on fees. The obvious question is, how deeply ingrained is this attitude through the markets? How do we ween the markets off this continuous dip feed? At this point the Central Banks have kicked that answer down the road.
Our take remains the Fed is not just focused on inflation but risks such as the commercial real estate debacle. the high US dollar and the massive Federal debt refunding cost.
How Extended? The Rally: Since the Fed’s December “dovish pivot” Into March
- S&P500 jumped 17.2%.
- The Semiconductor Index surged 25.3%,
- NYSE Arca Computer Technology Index 19.0%.
- Nvidia has almost doubled at up 98%, with Meta up 52%, Micron 41%, and Netflix 36%.
- Investment-grade spreads (to Treasuries) dropped from 1.04 to 0.88 – outside of a couple of months in 2021, the narrowest since March 2007 (20-year avg. 1.49).
- High yield spreads collapsed from 3.63 to 2.92 – that, excluding the six months beginning in June 2021, are the narrowest since July 2007 (20-yr avg. 4.93).
- “The tightest spreads on AA bonds since 2005” and “Single B Spread Index Makes New 16 year Low.”
- Gold prices have rallied $185, or 9.4% to $2,165, trading this week to an all-time high $2,221.
Last quarter continued the short squeeze, followed by asset chasing that began last year as financial conditions loosened further, building on the Fed’s Q4 dovish pivot. The standouts of course were the AI inspired rally led by NVidia and the crypto rip which saw Bitcoin break to new highs. The spectacular risk asset melt-up was ongoing and global, with record highs in the US, Germany, France and Australia indices to name a few.
We need to grasp all the risks to be wary of but not ignore price reaction. We always talk here about expect the unexpected and now that is front and center, gage the market’s reaction, the market is always right and that’s why we focus on the crowd psychology aspect.
Unsuspecting investors in their millions have or will lose meaningful amounts of their savings. They bought into the mania, threw caution to the wind, and will suffer the consequences regardless of the warnings of unsustainability. The reason we started TradersCommunity was for situations like this many moons ago. Beware of those ‘experts’ who never saw the sell off and chided you for believing it now claim to be gurus measuring risk. It’s a bit late when some of these stocks and markets are down 50-90%. Beware of those who claim long term investment when it all goes wrong. Anyhoo..
Our weekly reminder for risk, timely given the V shape to ATH in just a week. The downside is clear with the absence of moral hazard from repeated Federal Reserve market bailouts in an environment of some would say obscene liquidity pumps. Pure greed is the other part, not wanting to miss out. The obvious question is, how deeply ingrained is this attitude through the markets? How do we ween the markets off this continuous dip feed? At this point the Central Banks have kicked that answer down the road.
PART A – Stock Markets
Highlights – USA
- S&P500 dropped 3.0% (up 4.1% y-t-d),
- Dow was little changed (up 0.8%).
- S&P 400 Midcaps lost 2.2% (up 2.0%),
- Small cap Russell 2000 fell 2.8% (down 3.9%).
- Nasdaq100 sank 5.4% (up 1.3%).
- Utilities rallied 2.0% (up 4.1%).
- Banks recovered 2.0% (up 4.2%),
- Broker/Dealers dipped 0.8% (up 4.0%).
- Transports fell 2.7% (down 5.1%).
- Semiconductors were hit for 9.2% (up 3.1%).
- Biotechs dropped 3.9% (down 10.2%).
- While bullion surged $48, the HUI gold index was little changed (up 8.0%).

Highlights – Europe Stocks
- U.K.’s FTSE equities index declined 1.2% (up 2.1% y-t-d).
- France’s CAC40 was about unchanged (up 6.4%).
- German DAX equities index lost 1.1% (up 5.9%).
- Spain’s IBEX 35 equities index increased 0.4% (up 6.2%).
- Italy’s FTSE MIB index added 0.5% (up 11.8%).
Highlights – Asia Stocks
- Japan’s Nikkei Equities Index sank 6.2% (up 10.8% y-t-d).
- South Korea’s Kospi index sank 3.4% (down 2.4%).
- India’s Sensex equities index fell 1.6% (up 1.2%).
- China’s Shanghai Exchange Index recovered 1.5% (up 3.0%).
Highlights – Australian Stocks
- Australia’s ASX All Ordinaries: Friday -0.98% to 7567.3 (-2.8% for the week).
- NB: Record intraday of 7901.2 points, Record closing high 7896.9
- Up 4.2% this year, an extension of a 7.8 per cent rally in 2023.
- Australian shares fell seven times in eight sessions on Friday to its lowest level in almost three months – it closed at 7555.4 points on January 25.
- The interest rate-sensitive technology and real estate sectors worst performers, down 1.6% and 1.5% respectively.
- Energy the best performer as oil prices rose after Iran flagged an unspecified Israeli attack.
Highlights – Emerging Markets Stocks
- Brazil’s Bovespa index declined 0.7% (down 6.8%),
- Mexico’s Bolsa index lost 1.2% (down 2.7%).
- Turkey’s Borsa Istanbul National 100 index fell 1.2% (up 29.8%).
- Russia’s MICEX equities index increased 0.4% (up 12.0%).
Biggest SPX Stock Winners and Losers Last Week

Technical Analysis
Technical Analysis of key markets via KnovaWave
S&P 500
Daily: We saw a violent ABC for the 5 waves up for SPX continue right into bottom of the median line to give us an (a) or C of a 4. with impulse after completing 5. Reversed hard with energy fueled from the power impulse down from near +1/8 ATH. On the way up (just like down) It accelerated after it broke the Tenkan through the rejected Kijun and then the Kijun to close back over the median and 8/8. Bulls this was a (ii) of a 5. Bears this is a a-b of a C off a completive V of degree. We watch if this low was a (iii), (a) or C. Will determine if sharp ABC completed off all time highs around +1/8. We have to respect the number of alternatives of degree of 5. With such trends keep it simple support is Tenkan and Kijun and watch for ABC. No fear is the driving element.

The break up was from above the 200dma. The balance from sharp reversal after the initial 3 wave down from the SPX wave 5 extension as Covid19 fed impulse accelerated under the Tenkan. From there we had seen the ABC or 1-2-3 spinning around the 61.8% of the move. Support began at the October 2019 lows. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in. A manic wave 5 or 3 of some degree was a resolution for the ages. Note the 100% extension from the emotive element and MM levels when the spit kicks in
Weekly: The weekly shows us the reenergized SPX tripped in 3 to test recent break up at Tenkan from there we had had a powerful rally to ATH. Again notice what happened “Each new high has evolved after testing Tenkan key support which is the next line after Friday’s dump & minor bounce.” We watch for a spit of a spit Extensions are difficult to time, keep it simple.

Key for the impulse higher was the spit or retest of MM 8/8 and Tenkan San, which held with the previous highs and Tenkan. To repeat “We look for 3 waves down and reactions to keep it simple with the alternatives in the daily.” Keep an eye on the put/call ratio with recognition to the sheer size of contracts AND keep in mind the stimulus distortion. The spit per channel fractal and Adams rule launched back over the cloud where we were encased AND we are back testing it. Watch if a spit or clear break support as Chikou rebalances
Dow Jones

NASDAQ 100
Nasdaq move to ATH was after it broke and held the weekly Tenkan to see a spit of a spit fail which is completive of 5 of some degree with Chikou rebalancing. From there we sold off right to Tenkan (as did SPX) and bounced hard Support Tenkan to Kijun. Watch Chikou for divergence for continuation or failure. Divergence with Russell also a clue.


Russell 2000
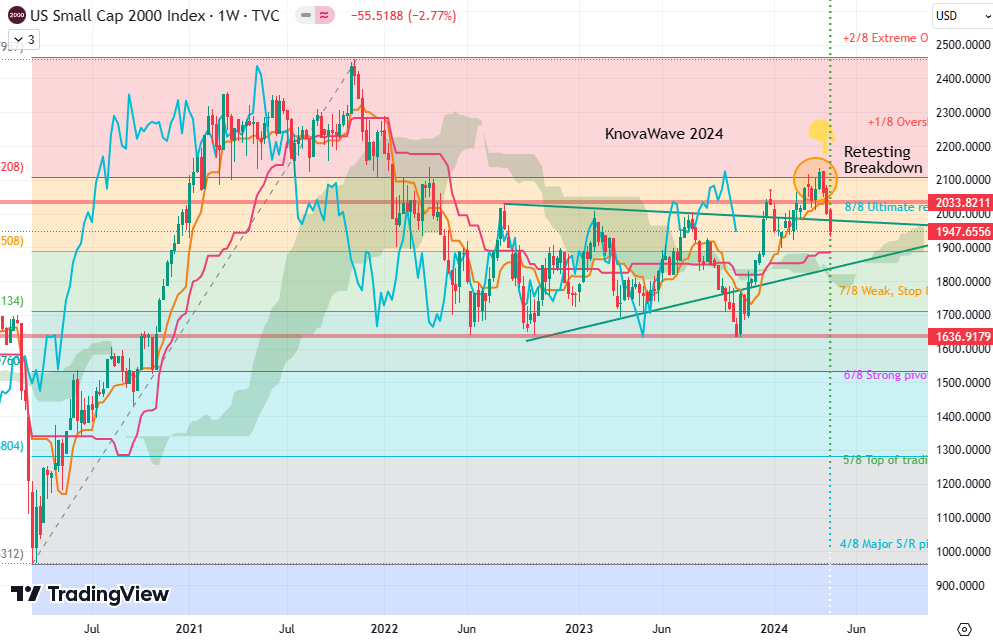
The small cap Russell RUT has been developing a large flag which it did a false break to fuel the selling from there we replicated to the down (Adam’s theory). Unlike SPX and NDX we could not get through Tenkan and Kijun which rejected the bounce. This is the index showing more of the fast money crowd and is trading like it. Closed right at the top of the cloud and at the channel. the flag. Needs to get traction in here for bulls. Support +1/8 through 7/8 (cloud base)
US Stocks Watch
Investors (and algos) will focus on the conference calls and outlooks. Last quarter everyone expected the worse, we saw critical updates on production in coronavirus impacted regions and if there is extended halting of operations weighing on multi-nationals.
Microsoft MSFT

NVidia $NVDA
Following the announcement of NVDA 4/1 split some levels off the energy break NVidia hadn’t looked back with many gaps below until it hit the 2.618 target of the exhaustion phase. We saw another power move off the $200 retest (old $800) & earnings off $300 which retested. It is a clear leader of SOX SMH look for cues there and ABC failures for changes.

Apple $AAPL
Apple gently motored up to new ATH over the massive $160 then $170 thru to $180 gamma level. These levels will be key energy levels. Support from previous highs, resistance now Fibs and Murrey Math levels. Remember the impact $AAPL has, at least short term on all the major indices.

Meta $META
Exxon’s Market Value Tops Tesla’s as Oil Rises, EV Sales Slow
- Tesla’s market value peaked at nearly $1 trillion over Exxon in November 2021
- Exxon Mobil Corp. surpassed Tesla Inc. in market value for the first time in more than a year
- Tesla down 41% this year after sales miss analysts’ estimates
- Path to electrification may be slower than previously thought. Major players like Ford Motor Co. and Hertz Global Holdings Inc. are reassessing their commitments to EVs as they grapple with slow market penetration.
- Exxon has reversed a decade-long decline in oil production and is capitalizing on rising oil prices
- Tesla’s shares had fallen to $147.05, a market capitalization of $469 billion.
- Exxon’s shares has increased to $119.88, a market capitalization of $475 billion.
Tesla $TSLA

Exxon Mobil $XOM

Part B: Bond Markets
Highlights – Treasuries
- U.S. Treasuries saw a modestly higher finish to a week that started with a slide to fresh lows for the year. Treasuries entire complex bounced in the late morning, which kept all tenors in the green until the close.
- This week’s underperformance in longer tenors alleviated some pressure on the 2s10s spread, expanding it by three basis points to -35 bps. Crude oil lost $3.49 for the week, while the U.S. Dollar Index at 106.15, finishing the week little changed.
- Corporate debt issuance is nothing short of breath taking. “The primary US investment-grade corporate bond market logged its busiest first quarter on record, super-charged by investors clamoring for high yields before the Federal Reserve starts cutting interest rates. Blue-chip firms have capitalized on robust investor demand to borrow a record $529.5 billion this year through Wednesday, far outpacing the previous high of $479 billion in the first three months of 2020… Sales hit a record in January and February and March issuance of $142.2 billion has exceeded expectations.” March 28 – Bloomberg (Caleb Mutua)
- Total money market fund assets contracted $112bn to $5.968 TN. Money funds were up $691 billion, or 13.2%, y-o-y.
- Total Commercial Paper dropped $18.6bn to $1.312 TN. CP was up $151bn, or 13.0%, over the past year.
- 2-yr: -2 bps to 4.97% (+9 bps for the week)
- 3-yr: -2 bps to 4.81% (+10 bps for the week)
- 5-yr: -3 bps to 4.66% (+7 bps for the week)
- 10-yr: -3 bps to 4.62% (+12 bps for the week)
- 30-yr: -3 bps to 4.71% (+11 bps for the week)


“The primary US investment-grade corporate bond market logged its busiest first quarter on record, super-charged by investors clamoring for high yields before the Federal Reserve starts cutting interest rates. Blue-chip firms have capitalized on robust investor demand to borrow a record $529.5 billion this year through Wednesday, far outpacing the previous high of $479 billion in the first three months of 2020… Sales hit a record in January and February and March issuance of $142.2 billion has exceeded expectations.” March 28 – Bloomberg (Caleb Mutua)
All good while markets hold up but take note that the loosest financial conditions in history have supported record corporate debt issuance. While easy credit availability has supported economic activity, funding new investment whilst keeping vulnerable companies afloat. The combination of urban shifts through virus and riots fears fueled a booming MBS market and record low mortgage rates pushing strong housing markets into Bubble risk territory. What we are seeing now is the same risk, on steroids is in the commercial real estate market (CRE).

Highlights – Mortgage Market
- Freddie Mac 30-year fixed mortgage rates surged 22 bps to a four-month high 7.10% (up 71bps y-o-y).
- Fifteen-year rates jumped 23 bps to a 20-week high 6.39% (up 67bps).
- Bankrate’s survey of jumbo mortgage borrowing costs had 30-year fixed rates down three bps to 7.47% (up 54bps).
Highlights – Federal Reserve
- Federal Reserve Credit declined $13.6bn last week to $7.388 TN.
- Fed Credit was down $1.501 TN from the June 22nd, 2022, peak.
- Over the past 240 weeks, Fed Credit expanded $3.661 TN, or 98%.
- Fed Credit inflated $4.577 TN, or 163%, over the past 597 weeks.
- Fed holdings for foreign owners of Treasury, Agency Debt rose $10.1bn last week to $3.369 TN.
- “Custody holdings” were up $31.7 billion y-o-y, or 0.9%.
We do know we have massive speculation pockets, viz a viz the Semi stocks and cryptocurrency mania in just the matter of weeks. The Fed is effectively throwing additional fuel on historic speculative manias. Central banks have been adding liquidity to avoid systematic failure.
Highlights – European Bonds
- Italian yields surged 17 bps to 3.93% (up 23bps y-t-d).
- Greek 10-year yields rose 12 bps to 3.55% (up 50bps).
- Spain’s 10-year yields gained 13 bps to 3.31% (up 32bps).
- German bund yields jumped 14 bps to 2.50% (up 48bps).
- French yields rose 15 bps to 3.01% (up 45bps).
- French to German 10-year bond spread was little changed at 51 bps.
- U.K. 10-year gilt yields increased nine bps to 4.23% (up 69bps).
Highlights – Asian Bonds
- Japanese 10-year “JGB” yields were little changed at 0.85% (up 24bps y-t-d).
Part C: Commodities
Highlights
- The Bloomberg Commodities Index was little changed (up 4.5% y-t-d).
- Spot Gold jumped 2.0% to $2,392 (up 15.9%).
- Silver rose 2.9% to $28.689 (up 20.6%).
- WTI crude dropped $2.52, or 2.9%, to $83.14 (up 16%).
- Gasoline slumped 3.3% (up 29%),
- Natural Gas declined 1.0% to $1.75 (down 30%).
- Copper jumped 2.9% (up 21%).
- Wheat declined 1.0% (down 12%),
- Corn dipped 0.5% (down 8%).
- Bitcoin sank $3,730, or 5.6%, to $63,220 (up 49%).

“Commodities will advance this year as central banks in the US and Europe move to reduce interest rates, helping to support industrial and consumer demand, according to Goldman Sachs… Raw materials may return 15% over 2024 as borrowing costs come down, manufacturing recovers, and geopolitical risks persist, analysts including Samantha Dart and Daan Struyven said…. Copper, aluminum, gold and oil products may climb, according to the bank, which also stressed the need for investors to be selective as gains wouldn’t be universal.” March 25 – Bloomberg (Yongchang Chin)
BDI Freight Index
- Baltic Exchange’s main sea freight index, a measure of global shipping costs, was up for the eighth consecutive session on Friday, rising 1% to an over three-week high of 1,919 points. The benchmark index gained about 11% for the week, notching its best performance in over seven weeks, propelled by all vessel segments.
- The panamax index, which typically carries 60,000-70,000 tons of coal or grain cargo, advanced for the seventh straight day, up 2.1% to 1,916 points;
- The supramax index increased 2.1% to 1,394 points.
- The capesize index, known for transporting 150,000-ton cargoes like iron ore and coal, eased 6 points to 2,839 points.
- Source: Baltic Exchange

Copper
Copper continued its rally after rebounding sharply off the 50wma pulled up by the flattening Tenkan and Kijun to close right at the channel break – a key juncture. #HG shrugged off demand concerns from resurgence in Covid-19 supply disruptions. The power spits of +8/8 and +2/8 were rebalanced by the Tenkan breaking the Kijun with 50wma and cloud below. Copper had been a leader in the risk on movement for commodities.
“Industrial metals including copper and zinc have outperformed global stocks this year as signs of a revival in demand from Chinese manufacturers add to concerns over tighter global supply. An index tracking the performance of six industrial metals on the London Metal Exchange has climbed 8% since the start of 2024… The index, which also includes lead, aluminium, tin and nickel, has risen sharply this month…”April 10 – Financial Times (Stephanie Stacey)
“Copper rallied to the highest in 14 months as investors flock to the bellwether industrial metal in response to rising supply risks and hopes for a global recovery in demand. Prices climbed as much 1.5% on Thursday after dovish comments from Federal Reserve Chair Jerome Powell added impetus to a rally that began in early February on fast-mounting risks to supply. Disruptions at major mines have left smelters paying historically steep prices to get hold of mined ore, and Chinese plants — which produce more than half of the world’s refined copper — are moving closer to implementing a joint output cut in response.” April 4 – Bloomberg (Mark Burton and Annie Lee)

Gold
- Gold hit an all-time record this week helped by China’s central bank (PBOC) buying for its reserves for a 17th straight month in March. Bullion held by the People’s Bank of China rose to 72.74 million fine troy ounces last month, according to official data released Sunday.
- Precious metals were the stellar performer in the commodities arena in Q1. Gold surged $167, or 8.1%, to an all-time high $2,230. Silver jumped 4.9% to $24.96.
- Central bank buying has also been a significant driver of its strength since 2022. Global central banks, led by China and India, continued adding to their gold reserves in February, marking a ninth straight month of growth, according to the World Gold Council.
- China’s official reserve assets rose to the highest since November 2015. The country’s foreign exchange reserves rose to $3.2457 trillion by the end of March, the highest since December 2021, as the central bank aims to maintain stable holdings to fend off risks. They rose 0.6% from February and were up 1.9% from a year earlier.

Energy
US Crude Oil (WTI)
Daily: WTI Crude Oil has continued to rally since retesting the pennant breakout last December after completing the correction in 3 waves. From there it broke the pennant and retested to continue to retest the breakdown last October to break above those descending levels for higher. We are in a completive mode for bulls with this impulse, it’s a question of degree on the topside, use the Murrey math 240/60 grid. Completing a C or IV? Support is previous lows and the bull flag. The bear case is the high was a complete 5.

Weekly: WTI crude oil futures held the support line from July 2021, having plunged around 50% off 2022 highs. It has broken to the topside of its sphere of influence to close out the quarter over Kijun and Tenkan which are now support. WTI completed 3 waves and powered through the tenkan and 50wma, h and held the retest. Risk support is the grid. Resistance weekly channel, Murrey Math levels and previous breaks (off monthly). Bear case is Wave 5 complete.
What we broke……. Crude Oil in the past quarter built a huge bull flag. We watch if the recent break was false, or we fail. Very clear pattern.

The key is crowd behavior to help tell the story which in energy is often around geopolitics. A great example of why we watch ABC corrections and from here we get the energy from the break being balanced. This move that was powered by 50 dma Tenkan spit of a spit – hence the fractal energies reverberations.
US Natural Gas (Henry Hub)
Daily: US Natural Gas futures are a great example of rebalancing mania. The market is still correcting the manic 5 post the Ukraine invasion and beyond. Since the breakdown of the correction channel with failed breakups we have continued to multi year lows in a pennant formation after holding the daily 1/8. We now look at our Adam’s theory fractal rules with fractal spits powering these moves lower. Two clear alternatives, we are correcting the highs 5 or that was a 3 and we go higher. Resistance is heavy: 2/8 and cloud above. Kijun, 50 dma and cloud. Support is previous lows. Important to watch how this energy was built for shape correlation.

Like the larger wave on the way up it accelerated through previous highs (flat topped triangle energy) and over the resistance at 8/8 and new highs. We successfully tested that break in a pennant ABC. Previous highs (flat topped triangle energy) and 8/8 and new highs underscore the structure that fed the move and is key longer term in the collapse lower.
Weekly: Natural gas still correcting the past month when blew through all levels of support after breaking the weekly 50wma and the Kijun gave a kiss of death. From there we Broke down out of the corrective channel (Wave 4 or IV) to new multi-year lows. This week we closed right at the weekly Kijun and 1/8. around the 50wma and tenkan in the cloud. The instability stems from the sharp reversals that have failed indicative of speculative fervor like the previous impulsive spikes. Support is the 1/8 Sphere. Bulls need all the damage down to be rebuilt. Kijun is major resistance given energy higher came from a clean break of the Kijun.

Part D: Forex Markets
John Maynard Keynes, 1920: “There is no subtler, no surer means of overturning the existing basis of society than to debauch the currency. The process engages all the hidden forces of economic law on the side of destruction and does it in a manner which not one man in a million is able to diagnose.”
Highlights
In the first quarter the dollar rode high against almost every major currency. We saw central banks, from Japan, China and India intervene, or consider intervening, to bolster their currencies. The yen in view of USDJPY 152 and the yuan struggling to break back below 7.2 USDCNH officials have stepped up efforts to stem any further depreciation.

In Japan it’s been verbal warnings, in China it has been state banks buying yuan and selling dollars.
Remember these two are major competitors for export dollars. With that there’s a school of thought that Beijing could have grown more tolerant of a weak yuan to maintain its competitive edge against the yen.
- For the week the U.S. Dollar Index gained slightly to 106.154 (up 4.8% y-t-d).
- On the upside, the Swiss franc increased 0.4%, the Canadian dollar 0.2%, and the euro 0.1%.
- On the downside, the Mexican peso declined 2.6%, the Brazilian real 1.6%, the South African rand 1.3%, the Norwegian krone 1.1%, the New Zealand dollar 0.9%, the Japanese yen 0.9%, the Australian dollar 0.8%, the British pound 0.7%, the South Korean won 0.5%, and the Swedish krona 0.3%. The Chinese (onshore) renminbi slipped 0.03% versus the dollar (down 1.92% y-t-d).
Australian Dollar – AUDUSD
The Aussie dollar is still correcting since completing a 5 at the pysch 80 level to fall under the weekly cloud in emotive fashion. The Australian dollar fell to test of the August lows of 0.7106 with Omicron fears. Should that double bottom go support ia the Murrey Math Levels. Resistance the Cloud, Tenkan and Kijun like many commodities.

Japanese Yen – USDJPY
USDJPY broke above after weakness with Treasury yields to rush to +2/8 and channel convergence, we have come a long way from that 108.00 massive support for dollar-yen back to test the top of the flat-topped triangle at 151/152. Any change will come from the weekly Kijun. Use your USDJPY Murrey 7/8 8/8 grid for now. EURJPY AUDJPY will determine risk on/off.

“The United States, Japan and South Korea agreed to ‘consult closely’ on foreign exchange markets in their first trilateral finance dialogue on Wednesday, acknowledging concerns from Tokyo and Seoul over their currencies’ recent sharp declines. The rare warning from the three countries’ finance chiefs came as receding expectations of a near-term U.S. interest rate cut pushed the yen to 34-year lows, keeping markets on alert on the chance of an intervention by Japan to prop up the currency.” April 17 – Reuters (Saqib Iqbal Ahmed)
Chinese Yuan – USDCNH

“Chinese businesses are hoarding dollars because they expect their own currency to weaken, and that in turn is exacerbating a slide in the yuan… This feedback loop has been playing out for months in mainland currency markets, spurred on by the dollar’s rising yield. Foreign exchange deposits have climbed $53.7 billion since September to $832.6 billion… Analysts say one of two things needs to happen to end the downward spiral: the Federal Reserve needs to make deep rate cuts or the yuan needs to hit some form of a trough. Both seem distant.” April 17 – Reuters

China manages its currency onshore by setting a daily reference rate against the dollar at 9:15 a.m. local time, around which it is then permitted to trade in a 2% range. The PBOC has kept the daily rate in such a tight range this year that a gauge of volatility in the fixing has dropped to the lowest since before the shock yuan devaluation of 2015.

Canadian Dollar – USDCAD
The Loonie is holding the Tenkan after a 3 year high in June and corrected that in 3 waves led by the AUD and NZD with oil price impacting direction. Watch flat Kijun and Tenkan at 8/8. Use Fibs for support and resistance.

Mexico Peso – USDMXN
“‘Super Peso’ Slides as Middle East Risk Threatens Carry Trade”: “The Mexican peso slumped the most in four years, as increasing conflict in the Middle East sapped demand for the currency that has been one of the favorite targets for carry trades. The peso tumbled more than 6% against the dollar as news began to filter through Friday of an Israel retaliatory strike on Iran, in what some in the market described as a ‘flash crash.’ The currency had climbed to the strongest in almost nine years last month, driven by relatively high local interest rates and low currency volatility.” Bloomberg (Marcus Wong)

Euro – EURUSD
Euro continues to bump up against that downtrend line from 2020 and spinning around the 50% of that year’s panic sell. The euro trades in what seems like eternal flags in the channel. We watch if Kijun (pink) testing Tenkan (orange) creates any impulse as EURUSD consolidates at the cloud. Watch 3 waves to see development for continuation. Watch for impulse off Chikou rebalance. Again governed by EURGBP and Bund volatility.

British Pound – USDGBP
British pound classic retest of daily cloud break with magnet pulls of cloud twist after ABC correction – will need Tenkan to break through Kijun for more strength. The upcoming month will be heavy on UK data and election speculation which could mean an eventful time for the British pound.

Bitcoin
Crypto Q1 24 Highlights
- Bitcoin surged 64% during the quarter,
- Ethereum gained 53%
- Binance Coin soared 95%.
- Having started trading on January 11th, the iShares Bitcoin ETF rose 52%.
Bitcoin is performing technically to perfection. Impulse begets impulse. To understand panic, understand greed. Bitcoin exploded higher following its correction impulsively upon completing 5 waves up at +2/8. Each Tenkan and Kijun tap saw an explosive kiss of death until we completed 3 waves to around 28,000. From there we have seen extreme volatility to a new record high and retest.

We have seen what you would expect from a 5-wave impulse peak and ABC correction, a violent correction and completion. Use Murrey Math levels for corrections and targets as algorithms control the herd here, support is the cloud and sharp ABC, 1-2 moves. From there prices agitated towards those ATHs as news of a Bitcoin ETF fueled the rally, sound familiar? But this time it wasn’t signaling we are in a 3 high probability but a 5.
On the Risk Radar

Geopolitical Tinderbox Radar
The Week Ahead – Have a Trading Plan
Watch Earnings, Central Bankers and Geopolitics speeches, reports and rate moves.
- All eyes on the Fed favorite Core PCE inflation this week on Friday. Federal Reserve Chair Powell noted that Fed economists expect the reading to land at 2.8% y/y unchanged from February. If so, and barring material revisions, that would imply that March would be 0.35% m/m SA higher than February and hence on the bubble between 0.3–0.4%. Most estimates in consensus are at 0.3% m/m SA.
- We also get new home sales (Tuesday): If a surge in model home foot traffic offers any indication, then new home sales during March could take off.
- Durable goods orders (Wednesday): Durables are expected to jump on airplane orders with Boeing posting 113 in March versus 15 in February and just 3 in January; key, however, will be core capital goods orders that are expected to post a small gain.
- Income and spending (Friday): Income growth is expected to accelerate alongside strong growth in personal spending given the already known 1.1% m/m jump in the retail sales control group that serves as input to the total consumption figures and offers substantial correlation.
Several countries are holding elections, headlined by India with its 44-day parliamentary election process on Friday. Narendra Modi’s Bharatiya Janata party looks set to secure another five years in power. In earnings season big banks reports continue with Goldman Sachs, Bank of America, Bank of New York Mellon, Morgan Stanley, Blackstone and American Express. Other big earnings include Netflix and Procter & Gamble.
US Economic Highlights
- Monday: Nothing of note
- Tuesday: Flash April S&P Global U.S. Manufacturing PMI (prior 51.9) and flash April S&P Global U.S. Services PMI (prior 51.7) at 9:45 ET; March New Home Sales (prior 662,000) at 10:00 ET; and $69 bln 2-yr Treasury note auction results at 13:00 ET
- Wednesday: Weekly MBA Mortgage Index (prior 3.3%) at 7:00 ET; March Durable Orders (prior 1.4%) and Durable Orders ex-transport (prior 0.5%) at 8:30 ET; weekly crude oil inventories (prior +2.74 mln) at 10:30 ET; and $70 bln 5-yr Treasury note auction results at 13:00 ET
- Thursday: Advance Q1 GDP (prior 3.4%), advance Q1 GDP Deflator (prior 1.6%), weekly Initial Claims (prior 212,000), Continuing Claims (prior 1.812 mln), advance March goods trade balance (prior -$91.8 bln), advance March Retail Inventories (prior 0.5%), and advance March Wholesale Inventories (prior 0.5%) at 8:30 ET; March Pending Home Sales (prior 1.6%) at 10:00 ET; weekly natural gas inventories (prior +50 bcf) at 10:30 ET; and $44 bln 7-yr Treasury note auction results at 13:00 ET
- Friday: March Personal Income (prior 0.3%), Personal Spending (prior 0.8%), PCE Prices (prior 0.3%), and Core PCE Prices (prior 0.3%) at 8:30 ET; final April University of Michigan Consumer Sentiment Index (prior 77.9) at 10:00 ET
Bond market Highlights
- Monday:
- Tuesday: $69 bln 2-yr Treasury note auction results at 13:00 ET
- Wednesday: $70 bln 5-yr Treasury note auction results at 13:00 ET
- Thursday:
Central Bank Highlights

A number of central banks with decisions this week, Fed-speak is on blackout.
- European Central Bank president Christine Lagarde delivers a guest lecture at Yale University in New Haven 0n Monday
- Bank of England chief economist Huw Pill speaks at the London campus of the University of Chicago, Booth School of Business Tuesday
- China – China’s banks are expected to leave their 1-year and 5-year Loan Prime Rates unchanged at 3.95% and 3.45% respectively on Sunday night (ET). The decision would follow the PBOC’s decision to leave its 1-year Medium-Term Lending Facility Rate unchanged at 2.5% this past week and a small upside surprised on Q1 GDP growth along with an upward revision to the prior quarter.
- Bank Indonesia—Consensus is somewhat divided on what Indonesia’s central bank might do on Wednesday. Most within consensus expect it to hold, but a significant minority expect it to hike by 25bps. The rupiah has sharply depreciated (chart 22) and it’s something that BI takes very seriously given the implications for imported inflation and financial stability.
- The Bank of Canada updates its Summary of Deliberations to the process leading up to the policy communications on April 10th on Wednesday. That meeting ended on a somewhat dovish sounding note that Governor Macklem reinforced in his joint panel appearance with Chair Powell this past week.
- Turkey— Another rate hike after the surprise 500bps hike to 50% on March 21st cannot be ruled out. Turkish core inflation moved up to 75.2% y/y in March to set a new pandemic-era high. Governor Fatih Karahan said this past week while attending IMF/World Bank Spring meetings that another hike could be delivered if inflation is expected to further deteriorate.
- Bank of Japan— No change in the target rate of 0.1% is expected when the statement is released late on Thursday evening (ET) ahead of Governor Ueda’s press conference on Friday. Forecast updates could be key in terms of further informing market pricing for roughly an additional 20bps of tightening later this year. An added key could be guidance on whether and when to begin shrinking the size of the BoJ’s massive balance sheet after ending yield curve control at the last meeting.
- Russia— Russia’s central bank is expected to hold at 16% on Friday.
US Earnings Highlights
The S&P 500 trades at 20.7 times its estimated earnings for the next 12 months, near a more than two-year high of 21.2 hit in late March, according to LSEG Datastream at a time when elevated yields on Treasuries bolster the attractiveness of bonds.
Analysts expect to see earnings growth of 5% in the first quarter, according to LSEG data. That would be the lowest since the second quarter of 2023. They expect margins to be squeezed by high interest rates, rising commodity costs, and falling corporate pricing power due to slowing inflation. Earnings grew by 10.1% in the fourth quarter of 2023.
A big week for earnings ahead, Tesla (TSLA), Meta Platforms (META), Alphabet (GOOGL) and Microsoft (MSFT.O) part of the group of companies that had been dubbed the Magnificent Seven as they led the S&P 500 to a 24% gain last year.

157 S&P500 firms will release earnings reports including names like Meta Platforms, Alphabet, Tesla, Ford, UPS, GE, Boeing, Caterpillar, Intel, and Microsoft. The earnings season is mixed so far with just 70 out of 500 firms out, as the earnings beat ratio remains high, but the revenue beat ratio is a coin-toss and other earnings details by sector and company have been highly variable. via ScotiaBank
- Monday starts us off with Cleveland-Cliffs (CLF), Verizon Communications (VZ), AGNC Investment (AGNC), Nucor Corporation (NUE), SAP SE (SAP), Alexandria Real Estate Equities (ARE), Albertsons Companies (ACI)
- Tuesday includes Tesla (TSLA), General Electric (GE), Visa (V), General Motors Company (GM), Lockheed Martin (LMT), PepsiCo (PEP), Freeport-McMoRan (FCX), Philip Morris International (PM), United Parcel Service (UPS), Texas Instruments (TXN), Halliburton Company (HAL), Spotify Technology S.A. (SPOT), Kimberly-Clark (KMB), JetBlue Airways (JBLU), Xerox (XRX), PulteGroup (PHM), The Boston Beer Company (SAM), Ryder System (R)
- Wednesday Includes Meta Platforms (META), AT&T (T), Ford (F), The Boeing Company (BA), IBM (IBM), QuantumScape Corporation (QS), Lam Research Corporation (LRCX), ServiceNow (NOW), Biogen (BIIB), Chipotle Mexican Grill (CMG), Hilton Worldwide Holdings (HLT), CME Group (CME), Hasbro (HAS), Humana (HUM)
- Thursday includes Alphabet (GOOG) (GOOGL), Microsoft (MSFT), Intel (INTC), Altria Group (MO), Gilead Sciences (GILD), Merck & Co. (MRK), Bristol-Myers Squibb Company (BMY), Caterpillar (CAT), Roku (ROKU), Teladoc Health (TDOC), American Airlines Group (AAL), Snap (SNAP), Southwest Airlines (LUV), Newmont Corporation (NEM), Comcast Corporation (CMCSA), Valero Energy (VLO), AstraZeneca PLC (AZN), Union Pacific (UNP), Royal Caribbean Cruises (RCL), Northrop Grumman (NOC), Deutsche Bank (DB), Capital One (COF)
- Friday includes Chevron (CVX) Exxon Mobil (XOM) AbbVie (ABBV), Phillips 66 (PSX), Colgate-Palmolive Company (CL), Unilever PLC (UL), JinkoSolar Holding (JKS), Charter Communications (CHTR), New York Community Bancorp (NYCB)
World events
Monday
- International Earth Day
- Jewish festival of Passover begins this evening
- US: opening arguments begin in the criminal trial of former US president Donald Trump. In a separate hearing, concerning the Trump Organization civil fraud case, the New York attorney-general’s office is expected to argue that the $175mn bond the company secured to avoid paying millions to the state in damages should not be accepted by the court
Tuesday
- St George’s Day marked in Bosnia and Herzegovina, Bulgaria, Canada, Catalonia, Croatia, Cyprus, England, Georgia, Greece, North Macedonia, Portugal, Romania and Serbia
- 200th day of the Hamas-Israel conflict after Hamas launched an attack on Israel on October 7 last year
Wednesday
- North Macedonia: presidential election first round
- UK: former Democratic Unionist party leader Sir Jeffrey Donaldson appears in court in Newry, Northern Ireland, charged with rape
Thursday
- Australia, New Zealand, UK: Anzac Day
- UK: CBI National Business Dinner, attended by senior figures from business, politics, and media. Traditionally addressed by a senior member of the government. Speakers include Rain Newton-Smith, chief executive of the troubled business lobbying group
Friday
- India: second phase of parliamentary elections begins
Saturday
- South Africa: 30th anniversary of the country’s first fully multiracial elections, marking the final end of apartheid
- US: White House Correspondents’ Association annual dinner, where the president traditionally pokes fun at himself in a light-hearted sketch
Sunday
- DR Congo: provincial governors and vice-governors elections
- Italy: G7 environment, climate and energy ministers meeting begins in Turin
- Japan: by-elections for three seats in the lower chamber of the Diet, the country’s parliament
US IPO Week Ahead
Four listings are currently scheduled for the week ahead.
- Enterprise data management and security platform Rubrik (RBRK) plans to raise $679 million at a $6.1 billion market cap. Its Rubrik Security Cloud platform delivers a cloud native SaaS platform that detects, analyzes, and remediates data security risks and unauthorized user activities. The platform is by a wide range of industries and geographies, and, as of January 31, 2024, Rubrik had more than 6,100 customers. The company has substantially grown its subscriptions, giving it a sticky customer base, but remains highly unprofitable.
- Commodities broker and trading services provider Marex Group (MRX) plans to raise $300 million at a $1.5 billion market cap. The company’s business consists of five segments: clearing, agency and execution, market making, hedging and investment solutions, and corporate. Marex provides connectivity to 58 exchanges, had a base of more than 4,000 clients as of December 31, 2023, and it executed approximately 129 million trades and cleared approximately 856 million contracts in 2023. It has a leading position among global commodities brokers, an industry characterized by difficult to predict trading volumes and volatility.
- Niche aerospace and defense components maker Loar Holdings (LOAR) plans to raise $275 million at a $2.2 billion market cap. Loar specializes in the design, manufacture, and sale of niche aerospace and defense components for aircraft and aerospace and defense systems. Its products span a diverse range of applications supporting nearly every major aircraft platform in use today and include auto throttles, temperature and fluid sensors and switches, and RAM air components, among others. The company has benefitted from strong tailwinds in defense spending, although it is significantly leveraged.
- Hong Kong-based trading platform provider mF International (MFI) plans to raise $7 million at a $59 million market cap. The company has a trading platform which it says currently handles a monthly average transaction value of more than $100 billion.
Focus on yourself and what YOU CAN INFLUENCE, set your trading plan and goals in be set for 2024. One suspects it will be a yearlong Groundhog Day for Biden, Trump, the GOP and the Democrats. Throw on top of that Russia/Ukraine Israel/Gaza and China/Taiwan.
Trade Smart!
Real Time Economic Calendar provided by Investing.com.
-comment section below data-
Subscribe and Follow
Find us at www.traderscommunity.com
Follow our contributors on Twitter @traderscom @thepitboss16 @knovawave @ClemsnideClem
Note these charts, opinions, news and estimates and times are subject to change and for indication only. Trade and invest at your own risk.
Trade Smart!