Norway’s central bank, the Norges Bank’s Monetary Policy and Financial Stability Committee kept rates at 4.50% at its January Meeting. The bank has borrowing costs that are the highest level since December 2008 as it sought to combat persistent inflation. Norges Bank guided it would stay on hold for “some time.” It dropped reference to how “the policy rate will lie around 4.5% until autumn 2024” which could be meaningful, or it could just be a reflection of the fact it was an interim meeting without forecasts or any refreshed explicit forward rate guidance.
Norway’s yield curve underperformed other cheaper European curves and the krone is outperforming, also due to higher oil prices this morning.

The bank had five consecutive hikes by December, equaling the sharpest hike since 2002.
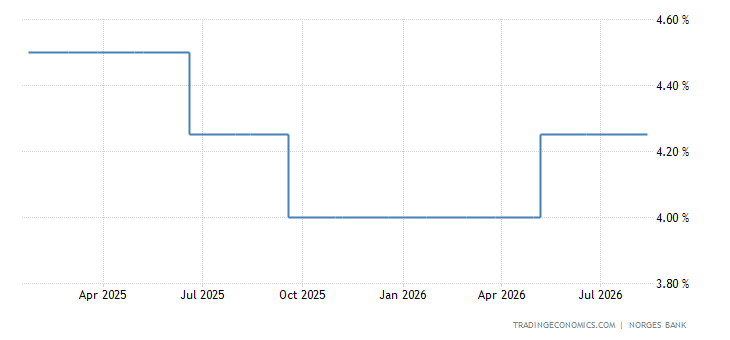
Norges Bank 4.50% was expected by the majority.

Norwegian crown
The Norwegian crown has been consistently weaker than predicted by the central bank, potentially stoking inflation. On a trade-weighted basis, the currency had weakened by around 9% this year until Wednesday’s market close.
Rate decision January 2024
The policy rate is kept unchanged
Introductory statement by Governor Ida Wolden Bache at the press conference following announcement of the policy rate on 25 January 2024.
The Monetary Policy and Financial Stability Committee decided to keep the policy rate unchanged at 4.5 percent.
Norges Bank is tasked with keeping inflation low and stable. The operational target is inflation of close to 2 percent over time. We are also mandated to help keep employment as high as possible and to promote economic stability.
Inflation is still high. In order to return inflation to target, we have raised the policy rate substantially over the past couple of years. In December, the policy rate was raised to 4.5 percent, and we signalled that it would remain at that level for some time ahead. New forecasts have not been prepared for this meeting, but we have assessed new information against the December forecasts. Our assessment is that the outlook has not changed materially since then.
Other central banks have also raised policy rates significantly in recent years in order to bring down inflation. Inflation among trading partner countries declined through last year, partly reflecting lower energy prices but also a slower rise in prices for other goods and services. The market’s interpretation of the outlook indicates that a number of central banks will lower their policy rates in the course of spring.
Chart: The krone has appreciated
The krone depreciated considerably through autumn last year. Since the December monetary policy meeting, the krone has appreciated again and more than expected. The appreciation has coincided with a rise in domestic market interest rates at the same time as international rates have fallen. The krone exchange rate is not a policy target, but we are concerned with the krone exchange rate insofar as it affects the inflation outlook. A stronger krone contributes to reducing import price inflation.
Economic growth in Norway is low. Household consumption appears to have held up better towards the end of last year than we projected in December. On the other hand, the level of new homes sales is low, as is the level of construction activity. In contrast to the construction industry, the oil services industry is experiencing vigorous growth.
The employment rate is high, and unemployment is low. At the same time, there are signs that the labour market is less tight than earlier. Employment growth has declined, and unemployment increased a little through last year. Unemployment has evolved as we projected in December, while employment appears to be slightly higher than projected.
Price inflation has declined since last summer but remains markedly above the inflation target. Energy prices increased through autumn so that overall consumer price inflation has moved back up somewhat. Excluding energy prices and indirect tax changes, inflation moved down to 5.5 percent in December broadly as projected, with a fall in both imported goods inflation and the rate of increase in domestic goods and services prices.
The Committee assesses that the policy rate is now sufficiently high to return inflation to target within a reasonable time horizon. Monetary policy is having a tightening effect, and the economy is cooling down. It will take time before we see the full effects of the past rate hikes. At the same time, business costs have risen considerably in recent years. Continued high wage growth and the krone depreciation through last year will likely restrain disinflation. We therefore believe a continued tight monetary policy stance will be needed for some time ahead. Further out, when inflation comes down and economic conditions so warrant, the Committee can start lowering the policy rate.
There is uncertainty about future developments in the Norwegian economy. If input cost inflation remains elevated or the krone depreciates again, price inflation may remain high longer than projected. In that case, the Committee is prepared to raise the policy rate again. If there is a more pronounced slowdown in the Norwegian economy or inflation declines more rapidly, the policy rate may be lowered earlier than envisaged in December.
Rate effective from 25 January 2024:
- Policy rate: 4.5 %
- Overnight lending rate: 5.5 %
- Reserve rate: 3.5 %
Norway Oil Fund
Norway’s $1.4tn wealth fund is the world’s largest sovereign wealth fund. It began in 1996 when oil revenue from the government was transferred to the fund for the first time. The mission of the fund is to provide financial wealth and stability for future generations of Norwegians once the oil revenues declines.
” The Government Pension Fund Global is saving for future generations in Norway. One day the oil will run out, but the return on the fund will continue to benefit the Norwegian population.” via Norway Fund
Norway’s oil fund owns on average 1.5 per cent of every listed company globally according to the FT.
Inflation and Fund Management
Inflation is identified as an issue at the oil fund, CEO Tangen, who warned that climate change will keep inflation high, said the fund was already using advanced algorithms to reduce trading costs and complexity and to boost internal productivity.
“The way we are putting money into the market, we are using AI models to predict when in the day, or over the month- or quarter-end we should deploy the capital. We are reducing trading activity because we are using AI models,” he said in an interview with FT.
“So, you can reduce the number of trades, and there are huge savings to be had there too,” he said, adding that: “It’s not like it’s on complete autopilot. We are monitoring it. It’s not like we’re the giving the fund to robots, and saying ‘hey, see you later’.”
Source: Norway, Sovereign wealth fund institute, FT
Clearly the small Nordic nation has been very successful in it’s investments and is prudent when comes to monetary policy.
2022 and January 2023 Return Update
At the end of January 2022 Norway’s $1.3tn oil fund had recovered in the first month of 2023 after its worst year since the global financial crisis. The fund had an annual return last year of minus 14.1 per cent, or NKr1.6tn ($159bn). It came with the biggest fall in Norwegian kroner terms on record. The sovereign wealth fund gained 5 per cent in January 2023, chief executive Nicolai Tangen told a press conference.
“It’s potentially one of those moments,” he said, referring to the rebound in 2009 after the financial crisis, “but the outcome this year is more uncertain than normal”.
The fund has also reduced its positions in the troubled Adani group of companies, Tangen said. The fund had holdings as of Monday of about $200mn in Adani companies, compared with its weight in the fund’s index of about $800mn.
The Fund is managed by Norway’s central bank, Norges Bank. Norges Bank Investment Management ” aims to make the most of the fund’s two distinguishing characteristics, its long-term approach and its considerable size, to generate strong returns and safeguard wealth for future generations.”
Equities had a negative return of 15.3 per cent, bonds lost 12.1 per cent while property eked out a 0.1 per cent gain.
Worse performers were technology companies with the worst performers of all the fund’s equity investments were Amazon, Meta, Tesla, Alphabet and Apple as a result of the sell-off in big tech companies that led the pandemic-era rally in 2020-21.
Best performers were energy companies, with ExxonMobil, Chevron, TotalEnergies and Shell plus drugmaker Novo Nordisk for the fund in 2022.
The aim is of the fund is diversification and that was shown with the fund as a whole not losing value in 2022 despite the large negative return as huge inflows from Norway’s oil and gas revenues, boosted by Russia’s war against Ukraine, stood at record levels. Norway’s petroleum revenues soared as the Scandinavian country displaced Russia as the biggest supplier of gas to the EU.
The aim of the fund was diversification from oil and to invest in opportunity. “We invest in almost 9,000 companies and have investments in 77 countries.’ Says Norges Bank on their website.
Outside of Oslo Norges Bank has offices in Luxembourg, Tokyo, London, New York, Singapore and Shanghai to manage their investments. The spread gives you an idea of their focus.
Source: Norges Bank
From The Traders Community Research Desk