Where Independent Traders, Investors, and Dribblers Thrive
Bond Vigilantes Hover as Global Debt Keeps Building
Debt has continued to soar in 2025 around the world this follows global debt increasing by around $7 trillion in 2024 to a record annual high $318 trillion according to the Institute of International Finance (IIF). The sustainability and productive nature of the debt is questionable given total debt as a share of gross domestic product rose for the first time in four years as economic growth slowed. The institute predicted borrowing will remain high through 2025, especially in the US, France, China, India and Brazil. An overheating economy, coupled with tariff and trade war risks, creates a bond market challenge.
Bond Vigilantes Hungry
The IIF said rising debt burdens meant governments should be ‘beware of bond vigilantes,’ who sell bonds aggressively which pushes up interest rates in a bid to force policymakers to rein in budget deficits and debt.
Debt isn’t just government and corporate, US consumer debt outstanding surged by the most on record in December 2024. This came as inflation and interest costs hit consumers pushing massive increases in credit-card balances and non-revolving credit. Total credit jumped $40.8 billion after a revised $5.4 billion decrease a month earlier, according to Federal Reserve data.
The scary thing for those relying on economists and policymakers these numbers topped all estimates by massive amounts. Outstanding credit-card and other revolving debt increased $22.9 billion in December. Non-revolving credit, such as loans for vehicle purchases and school tuition, climbed $18 billion, the most in two years.
Trump walked into a mountain of debt.
The Congressional Budget Office (CBO) issued a report earlier in the month in which it projected a $1.9 trillion budget deficit for fiscal 2025.
President Trump is walking into about $28 TN of outstanding Treasuries, registering at 95% of GDP – having expanded $11.7 TN, or 54%, over the past 19 quarters.
Bank assets expanded $6.4 TN, or 30%, in 19 quarters to approach $28 TN. Broker/Dealer assets inflated 40% in 18 quarters to almost $6 TN. Total system “repo” assets surged 54% in 19 quarters to $7.4 TN.
Having expanded 71% in 19 quarters, MMFA surpassed $7 TN. Total Securities inflated $58.7 TN, or 62%, in five years to $153 TN – or 522% of GDP.
Household Net Worth ballooned $50 TN, or 42%, in 17 quarters to a record $169 TN – or 575% of GDP.
Non-Financial Debt (NFD – from the Fed’s Z.1) expanded at a seasonally adjusted and annualized (SAAR) $3.342 TN in Q1, $3.471 TN in Q2, and $3.642 TN during Q3. For perspective, NFD expanded $2.534 TN in 2007 – an annual record that held all the way to pandemic 2020’s historic $6.797 TN.
We have seen a spectacular monetary inflation, MMFA inflated $2.212 TN, or 49%, since the Fed commenced “tightening” in March 2022, and $3.137 TN, or 86%, since the start of the pandemic (Feb. ’20). Notably 78% ($74.5bn) of last week’s expansion and 75% ($474bn) of the 18-week surge are shown by growth in institutional money funds (as opposed to retail). This is a reflection of the repo market “basis trade” leveraging and securities finance more generally (intermediated through institutional funds). This is why the carry trade is so influential in price action.
But let’s not forget…. So Much Debt…
Scott Bessent at his confirmation hearing recognized the issues. “I believe that President Trump has a generational opportunity to unleash a new economic golden age that will create more jobs, wealth and prosperity for all Americans. My life’s work in the private sector has given me a deep understanding of the economy and markets.”
“The federal government has a significant spending problem, driving deficits that have averaged an historically high 7% of GDP annually during the past four years. We must work to get our fiscal house in order and adjust federal domestic discretionary spending that has grown by an astonishing 40% over the past four years. Productive investment that grows the economy must be prioritized over wasteful spending that drives inflation.”
“This is the single most important economic issue of the day. This is pass/fail. If we do not fix these tax cuts, if we do not renew and extend, then we will be facing an economic calam
Debt …. Keeps Building
U.S. Debt Ceiling
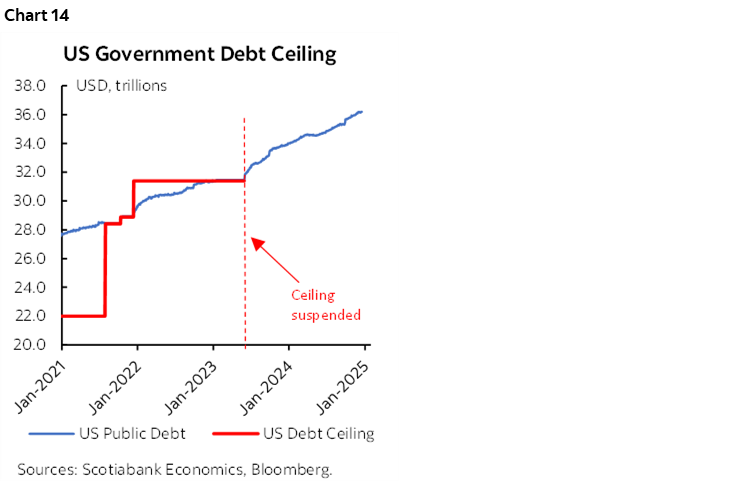
The US debt ceiling was reinstated at the level of public debt on January 1st, 2025, after it was suspended in June 2023. There is over US$36 trillion of the US Treasury’s public debt outstanding (chart 14).
It has risen by about $5 trillion since the debt ceiling was suspended a year-and-a-half ago. Now that is $5 trillion in a booming economy by President Biden. There are some difficult choices into the new year.
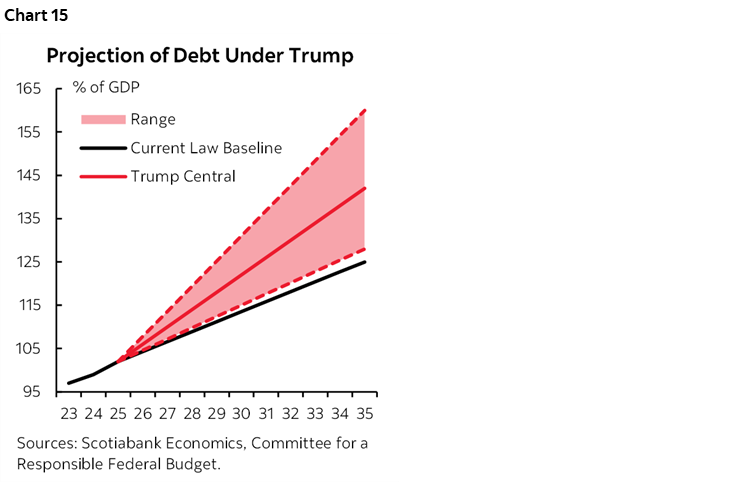
US president Trump wish is to deliver trillions of dollars in tax cuts and there is the question of how to fund them. More debt is the very likely answer as we see below (chart 15). Tax cuts like the ones he proposes don’t pay for themselves and certainly did not after the Tax Cuts and Jobs Act of 2018; Trump inherited a deficit-to-GDP ratio of about 2½% after winning the election in 2016 and raised it to almost double that just before the pandemic struck.
Abolishing the debt ceiling makes sense in that creates needless turmoil in the operation of basic government services and market uncertainties on all-too-frequent basis Scotiabank reasoned. However like everything around US politics, debt and lobbyists not everyone agrees. The more conservative wing of the GOP is resisting and think it applies some discipline. There is the mid-2026 deadline for Musk’s DOGE proposals for enhanced government efficiency. If so, then the consequences could be disruptive to markets which are backed by the basis and carry trade.
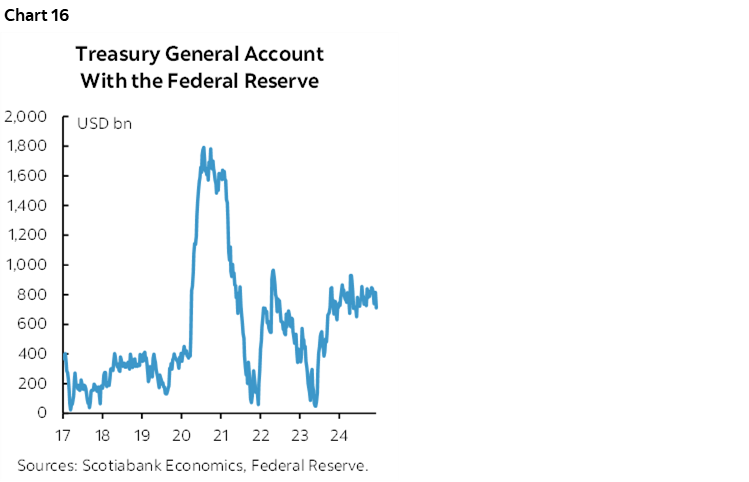
Treasury’s cash hoard in the General Account held at the Federal Reserve (chart 16) stands at about US$775 billion with plans to lower it toward $700B before the debt ceiling is imposed. During prior debt ceiling spats this cash hoard became largely depleted. As the proceeds were disbursed within the banking system it sparked an increase in bank reserves held at the Fed which would repeat this time along with increased demand at the overnight reverse repurchase agreement facility (RRP). This surge in market liquidity was left to chase scarcer Treasuries due to the suspension of net issuance.
2024 Punter Facts to Be Aware of:
At this point logic tells us the bubbles burst, or inflation accelerates late in the cycle. Logic doesn’t apply in manias, however. Bond vigilantes love this scenario.
“Investors plowed more than $1 trillion into U.S.-based exchange-traded funds in 2024, shattering the previous record set three years ago
The rebound from last year’s lackluster flows marked a broad embrace of U.S. assets in a year in which the S&P 500 gained around 25%
Total assets in U.S.-based ETFs reached a record $10.6 trillion at the end of November, according to… ETFGI data, an increase of more than 30% from the start of 2024.
Invesco’s QQQ, which tracks the tech-heavy Nasdaq-100 Index attracting more than $27 billions of fresh cash through mid-December. It was an eye-popping figure after QQQ brought in $7.3 billion in 2023” – Wall Street Journal (Jack Pitcher)
SIFMA data showed total 2024 U.S. corporate (“investment grade/high yield, nonconvertible/convertible, callable/noncallable and fixed rate/floating rate”) issuance surged 30.2% to $1.957 TN.
“BofA Securities was the top arranger of US leveraged loans in 2024 as the value of deals rose 122%. Companies borrowed $2.22 trillion of loans vs. $1 trillion in 2023.” – Bloomberg
“The muni market saw $507.585 billion of debt issued in 2024, up 31.8% from $385.061 in 2023. This surpasses the previous record of $484.601 billion in 2020…” – Bond Buyer
MMFA expanded $873 billion, or 14.6%, in 2024. MMFA ballooned at a blistering 27% pace during the final 22 weeks of the year, a period when the Fed aggressively loosened policy. MMFA expanded an incredible $2.289 TN, or 50%, since the Fed began “tightening” in March 2022 – and $3.214 TN, or 88%, since the start of the pandemic (February 2020).
Non-Financial Debt (NFD – from the Fed’s Z.1) expanded at a seasonally adjusted and annualized (SAAR) $3.342 TN in Q1, $3.471 TN in Q2, and $3.642 TN during Q3. For perspective, NFD expanded $2.534 TN in 2007 – an annual record that held all the way to pandemic 2020’s historic $6.797 TN.
As of September 30th, Treasuries had inflated $1.965 TN, or 7.6%, over the previous year; $3.970 TN, or 16.8%, over two years; and $10.957 TN, or 66%, over 19 quarters.
Total (Debt and Equities) Securities inflated $24.447 TN, or 19.0%, over the previous year, and $58.714 TN, or 62%, over 20 quarters – to a record $153.181 TN.
Total Securities ended Q3 at 522% of GDP, dwarfing cycle peaks 375% (Q3 2007) and 357% (Q1 2000).
Household Net Worth (Assets less Liabilities) inflated $17.277 TN, or 11.4%, in the 12 months ended September 30th – to a record $168.8 TN.
Net Worth inflated $49,873 TN over 17 quarters, or 42%. Household Net Worth ended September at 575% of GDP, above previous cycle peaks 488% (Q1 2007) and 444% (Q1 2000).
Before all this U.S. equities inflated $5.812 TN during Q3 to a record $91.720 TN. One-year growth of $21.105 TN, or 29.9%, compares to 2003’s pre-2008 crisis annual record gain of $4.385 TN. Over the past five years, Equities inflated $40.950 TN, or 80.7%. At 312%, Q3’s Equities-to-GDP ratio compares to previous cycle peaks 187% (Q3 2007) and 210% (Q1 2000).
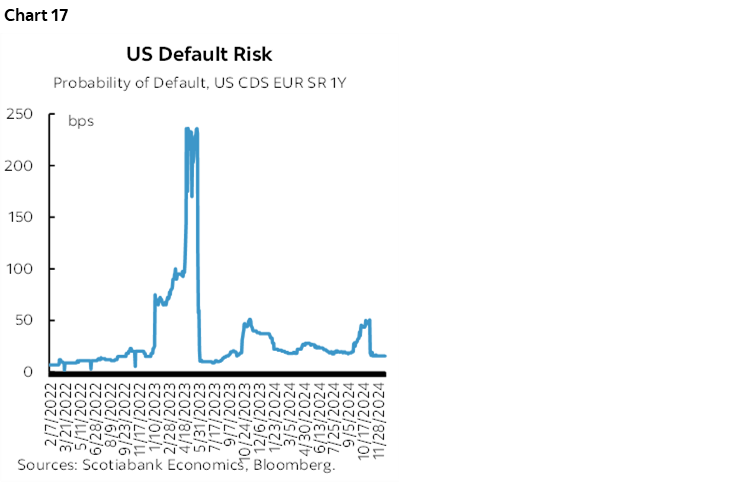
An extreme scenario raises the risk of default that would be reminiscent of what happened to the soaring cost of insuring against US government debt default in CDS markets the last time around (chart 17).
Once the debt ceiling is raised, Treasury can return to issuing debt, reverse other extraordinary measures, and replenish its general account thus reversing consequences for funding markets.
Wealth Inequalities
The US consumer has delivered but delinquency rates are rising for several credit categories. Looking deeper much of this has been more about normalization toward pre-pandemic patterns compared to when extreme policy supports, and very low rates meant little to no default activity in the pandemic. Scotiabank points out that “We are at a twenty-three year low in the debt-to-disposable income ratio and still toward record low debt service payments to incomes remain supportive of spending and lessen rate sensitivity compared to, say, strained measures into the GFC. The personal saving rate has normalized, but the stock of outstanding cash and checkable deposits on US household balance sheets remains very elevated “
In Q3 2024 U.S. household Net Worth (Assets less Liabilities) inflated $4.766 TN (11.6% annualized) to a record $168.800 TN, with one-year growth of $17.277 TN, or 11.4%. For perspective, Net Worth inflated a then record $4.006 TN in 1999, and a mortgage finance Bubble high of $6.871 TN in 2004.
The pre-pandemic record was set with 2019’s $12.710 TN increase. Net Worth inflated $49,873 TN over 17 quarters, or 42%. There’s no mystery surrounding the ongoing pump.
Chart 1 Difference between total household net worth today minus what a simple, stable trend line fitted to the pre-pandemic era would have predicted to happen to net worth by now. Chart 2 shows the cumulative change in household net worth by now compared to a trend line; American households have about US$18.9 trillion in ‘excess’ net worth. via Scotiabank
What’s more is that US households also maintain very high liquidity with cash and near-cash balances sitting at about US$4 trillion, or four times the pre-pandemic level. Idle cash sitting around is tempting to spend. Overall, these points all taken together suggest that the outlook for US consumer spending continues to be strongly supported by ‘excess’ savings.
Well, the Fed is still behind the game on inflation and the tide has turned on Tesla and even more so on electric vehicles. This and inflation are not unrelated. Russia did invade Ukraine, and that war is ongoing with the US writing billions in aid checks. This is also inflationary.
A reminder wealth inequalities become only more pronounced late in the cycle, creating a sprawling divergence between market euphoria and deepening public dissatisfaction. Political class market embracement and accommodation shifts to the appeasement of ever more powerful populist movements. Markets this week at least acknowledge the unfolding power-shift to disgruntled electorates. and voters. In opportune times you need to be flexible and wait like a cobra to strike. There is a number of reasons why Warren Profit has accumulated so much cash heading into these results.
While we are all aware politicians don’t keep promises the “deficits don’t matter” is at precarious extremes. Such profligacy is a dangerous consequence of repeated Fed market bailouts and the resulting subversion of market discipline. One looks towards Elon Musk’s cost cutting if Trump wins as something no one believes, if true, government jobs appear vulnerable given that has been the bulk of the Biden hiring’s recent gains.
Ahead we have Iran’s faux war threats sauced with more anti-western rhetoric and some potential risk to energy markets. Putin and Isreal eye their next moves as they watch on the future of US leadership be unveiled. Through in key central bank meetings and earnings, a busy few months lie ahead.
Two paths to bankruptcy: gradually and suddenly. – Ernest Hemingway
Our basic assumption throughout this most protracted credit bubble was that market discipline would eventually win the day. It has been an incredibly long wait. And we all know the pitfalls of asserting “this time is different.”
Oh, the debt and spending. The US federal government ran a $1.8 TN deficit in 2023, or almost 7% of GDP. Most analysts believe the deficit only grows from here. There are reasonable scenarios where it spirals out of control. Paul Tudor Jones has stated the issue concisely: “We are going to be broke really quickly unless we get serious about dealing with our spending issues.”
Also grabbing our attention is the continuing woes and distractions in China and the unstable emerging markets. The bond markets in the U.S. are also depicting risk adverse behavior. Endless supply coupled with an elevated deflation risk weighing on market sentiment globally
Europe remains on the radar. The euro continued to drift lower to its weakest in about a month, under-performing its major peers. French President Emmanuel Macron and German Chancellor Olaf Scholz both suffered humiliating reverses in the past months. For Scholz it cost him his position and he is no longer Chancellor. Lord knows what is going on in the UK.
Much of this is climbing the wall of worry, FOMO and in the US, households have an abundance of excess savings and high liquidity. These are all factors we watch in our risk matrix. Remember the stock market is not the economy, the stock market is a mountain of human emotion guided by greed and fear.
Eyes on The US Treasury Market
US treasuries, despite the Federal Reserve cutting rates have weakened since with yields consolidating at the higher end with the curve shifting. Below see the 2, 10 and 30 year curves as of the end of February. Yields fell sharply in February as the markets became more concerned at weakening growth from the Trade war and inflationary burdens. The safe haven factor does give US treasuries some comfort, however inflation or undermining of the US would embolden the bond vigilantes. In the US it tends to affect the curve rather than all-out assault like we saw in the attack on Great Britain’s gilts two years ago.
2-yr: -8 bps to 4.00% (-19 bps this week; -24 bps in February)
3-yr: -8 bps to 3.98% (-22 bps this week; -30 bps in February)
5-yr: -8 bps to 4.03% (-23 bps this week; -33 bps in February)
10-yr: -5 bps to 4.23% (-19 bps this week; -34 bps in February)
30-yr: -4 bps to 4.52% (-15 bps this week; -29 bps in February)
NB: At Close 2/28/24
US Long Bond
2024Recap:
US Treasuries gained 0.7% on average through Dec. 18, compared with a 5.1% return in T-bills. It marked a fourth year that bonds underperformed cash, a record since Bloomberg started compiling the data on T-bill returns in 1991. Over the past four years, bills returned a total of 12%, compared with a loss of 10% in government bonds.
US money-market funds — which hold cash-like instruments such as T-bills and commercial paper — have grown by more than $800 billion in 2024, swelling their assets to $7 trillion for the first time as investors piled in. Also, among the hoarders? Warren Buffett’s Berkshire Hathaway Inc., whose Treasury bill holdings more than doubled this year to approach $300 billion as of the third quarter.
2-yr: 4.24% (-1 bp for the year)
3-yr: 4.27% (+26 bps for the year)
5-yr: 4.38% (+53 bps for the year)
10-yr: 4.57% (+69 bps for the year)
30-yr: 4.78% (+75 bps for the year)
Americas Bonds in 2024
Highlights – Federal Reserve
Federal Reserve Credit declined $30.6 billion last week to $6.729 TN. Fed Credit was down $2.161 TN from the June 22, 2022, peak.
Over the past 285 weeks, Fed Credit expanded $3.002 TN, or 81%. Fed Credit inflated $3.918 TN, or 139%, over the past 642 weeks.
Fed holdings for foreign owners of Treasury, Agency Debt dropped $12.3 billion last week at $3.290 TN.
“Custody holdings” were down $64 billion y-o-y, or 1.9%.
Highlights – Mortgage Market
Freddie Mac 30-year fixed mortgage rates dropped nine bps this week to a two-month low of 6.76% (down 18bps y-o-y).
Fifteen-year rates fell 10 bps to 5.94% (down 32bps).
Bankrate’s survey of jumbo mortgage borrowing costs had 30-year fixed rates up 10 bps to 7.04% (down 28bps).
Focus on yourself and what YOU CAN INFLUENCE, set your trading plan and goals in be set for 2025.
We use cookies on our website to give you the most relevant experience by remembering your preferences and repeat visits. By clicking “Accept All”, you consent to the use of ALL the cookies. However, you may visit "Cookie Settings" to provide a controlled consent.
This website uses cookies to improve your experience while you navigate through the website. Out of these, the cookies that are categorized as necessary are stored on your browser as they are essential for the working of basic functionalities of the website. We also use third-party cookies that help us analyze and understand how you use this website. These cookies will be stored in your browser only with your consent. You also have the option to opt-out of these cookies. But opting out of some of these cookies may affect your browsing experience.
Necessary cookies are absolutely essential for the website to function properly. These cookies ensure basic functionalities and security features of the website, anonymously.
Cookie
Duration
Description
cookielawinfo-checkbox-analytics
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Analytics".
cookielawinfo-checkbox-functional
11 months
The cookie is set by GDPR cookie consent to record the user consent for the cookies in the category "Functional".
cookielawinfo-checkbox-necessary
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookies is used to store the user consent for the cookies in the category "Necessary".
cookielawinfo-checkbox-others
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Other.
cookielawinfo-checkbox-performance
11 months
This cookie is set by GDPR Cookie Consent plugin. The cookie is used to store the user consent for the cookies in the category "Performance".
viewed_cookie_policy
11 months
The cookie is set by the GDPR Cookie Consent plugin and is used to store whether or not user has consented to the use of cookies. It does not store any personal data.
Functional cookies help to perform certain functionalities like sharing the content of the website on social media platforms, collect feedbacks, and other third-party features.
Performance cookies are used to understand and analyze the key performance indexes of the website which helps in delivering a better user experience for the visitors.
Analytical cookies are used to understand how visitors interact with the website. These cookies help provide information on metrics the number of visitors, bounce rate, traffic source, etc.
Advertisement cookies are used to provide visitors with relevant ads and marketing campaigns. These cookies track visitors across websites and collect information to provide customized ads.